
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
SCHEDULE 13E-3
RULE 13E-3 TRANSACTION STATEMENT UNDER SECTION 13(E)
OF THE SECURITIES EXCHANGE ACT OF 1934
PERSONALIS, INC.
(Name of the Issuer)
Personalis, Inc.
Tempus AI, Inc.
Aviary Development, Inc.
Toucan Development, LLC
Eric Lefkofsky
(Names of Persons Filing Statement)
Common Stock, par value $0.0001 per share
(Title of Class of Securities)
71535D106
(CUSIP Number of Class of Securities)
| Eric Lefkofsky Chief Executive Officer, Founder and Chairman Tempus AI, Inc. 600 West Chicago Avenue, Suite 510 Chicago, Illinois 60654 (800) 976-5448 |
Christopher Hall Chief Executive Officer Personalis, Inc. 6600 Dumbarton Circle Fremont, California 94555 (650) 752-1300 | |
| (Name, Address, and Telephone Numbers of Person Authorized to Receive Notices and Communications on Behalf of the Persons Filing Statement) | ||
With copies to:
| Bradley C. Faris Latham & Watkins LLP 330 North Wabash Avenue, Suite 2800 Chicago, IL 60611 (312) 876-7700 |
Bill Roegge Laura Berezin Cooley LLP 55 Hudson Yards New York, NY 10001 (212) 479-6000 |
This statement is filed in connection with (check the appropriate box):
| a. |
☒ | The filing of solicitation materials or an information statement subject to Regulation 14A, Regulation 14C or Rule 13e-3(c) under the Securities Exchange Act of 1934. | ||
| b. |
☒ | The filing of a registration statement under the Securities Act of 1933. | ||
| c. |
☐ | A tender offer. | ||
| d. |
☐ | None of the above. | ||
Check the following box if the soliciting materials or information statement referred to in checking box (a) are preliminary copies: ☒
Check the following box if the filing is a final amendment reporting the results of the transaction: ☐
Neither the Securities and Exchange Commission nor any state securities commission has approved or disapproved this transaction, passed upon the merits or fairness of this transaction or passed upon the adequacy or accuracy of the disclosure in this transaction statement on Schedule 13E-3. Any representation to the contrary is a criminal offense.
INTRODUCTION
This Rule 13e-3 Transaction Statement on Schedule 13E-3 (this “Transaction Statement”), together with the exhibits hereto, is being filed with the U.S. Securities and Exchange Commission (the “SEC”) pursuant to Section 13(e) of the Securities Exchange Act of 1934, as amended (the “Exchange Act”), jointly by the following persons (each, a “Filing Person” and collectively, the “Filing Persons”): (i) Personalis, Inc., a Delaware corporation (“Personalis”), and the issuer of the common stock, par value $0.0001 per share (“Personalis Common Stock,” and the holders thereof, the “Personalis Stockholders”), that is subject to the Rule 13e3 transaction; (ii) Tempus AI, Inc., a Nevada corporation (“Tempus”), (iii) Aviary Development, Inc., a Delaware corporation and a wholly owned subsidiary of Tempus (“Merger Sub I”), (iv) Toucan Development, LLC, a Nevada limited liability company and a wholly owned subsidiary of Tempus (“Merger Sub II” and, together with Merger Sub I, the “Merger Subs”), and (v) Eric Lefkofsky.
This Transaction Statement relates to the Agreement and Plan of Merger, dated July 20, 2026 (as it may be amended, amended and restated or otherwise modified from time to time, the “Merger Agreement”), by and among Personalis, Tempus, Merger Sub I, and Merger Sub II, pursuant to which (i) Merger Sub I will merge with and into Personalis (the “First Merger”), with Personalis surviving the First Merger as a wholly owned subsidiary of Tempus (such surviving corporation, the “First Surviving Company”), and (ii) as part of the same overall transaction, immediately after the First Merger becomes effective (such date and time as the First Merger becomes effective, the “Effective Time”), the First Surviving Company will merge with and into Merger Sub II (the “Second Merger” and, together with the First Merger, the “Mergers”), with Merger Sub II surviving the Second Merger as a wholly owned subsidiary of Tempus (the “Surviving Company”).
Under the terms of the Merger Agreement, at the Effective Time, each share of Personalis Common Stock issued and outstanding immediately prior to the Effective Time (other than shares of Personalis Common Stock that are owned or held in treasury by Personalis or are owned by Tempus, Merger Sub I, Merger Sub II or their controlled affiliates (such shares, the “Cancelled Shares”) and shares of Personalis Common Stock that are outstanding immediately prior to the Effective Time and which are held by stockholders who have exercised and perfected appraisal rights for such shares in accordance with the Delaware General Corporation Law, as amended (such shares, the “Dissenting Shares”)) (such shares other than the Cancelled Shares and the Dissenting Shares, the “Eligible Shares”) will be automatically converted into the right to receive, in accordance with, and subject to the terms, conditions and procedures set forth in, the Merger Agreement, the following consideration (collectively, the “Merger Consideration”):
| • | a number of validly issued, fully paid and nonassessable shares of Class A common stock, par value $0.0001 per share (“Tempus Class A Common Stock”) equal to the “Exchange Ratio,” which will be: (a) 0.3356, if the Tempus Stock Price (as defined in the Merger Agreement) is equal to or less than $48.42 (the “Floor Price”); or (b) the quotient of $16.25 divided by the Tempus Stock Price, if the Tempus Stock Price exceeds the Floor Price (in each case, the “Stock Consideration”); provided, however, that, at any time prior to the third business day prior to the closing of the First Merger, Tempus may elect (a “Tempus Cash Election”) to pay cash for up to 50% of the aggregate number of outstanding shares of Personalis Common Stock (subject to potential reduction to preserve the intended tax treatment of the Mergers). If Tempus makes a Tempus Cash Election, each Personalis Stockholder will receive: (i) $16.25 per share in cash, without interest (the “Cash Consideration”) (which may include a fraction of a share and, in that context, will be rounded to the nearest four decimal places), for such holder’s pro rata portion of the shares of Personalis Common Stock subject to the Tempus Cash Election, and (ii) the Stock Consideration for the holder’s remaining shares; |
| • | cash in lieu of any fractional shares of Tempus Class A Common Stock, calculated based on the Tempus Stock Price, without any separately bargained-for consideration; and |
| • | such amounts of post-closing distributions payable in respect of the Tempus Class A Common Stock issuable in the First Merger, if any. |
The First Merger will become effective upon the filing of a certificate of merger with the Secretary of State of the State of Delaware (the “Delaware Secretary of State”), or at such later date and time as is specified in such certificate of merger and agreed by the parties. Immediately after the First Merger, the Second Merger will become effective upon (i) the filing of a certificate of merger with the Delaware Secretary of State, and (ii) the filing of articles of merger with the Nevada Secretary of State, or at such later date and time as is specified therein and agreed by the parties.
1
Holders of Tempus Class A Common Stock and Class B common stock, par value $0.0001 per share, of Tempus (“Tempus Class B Common Stock” and, collectively with Tempus Class A Common Stock, “Tempus Common Stock”) prior to the Mergers will continue to own their existing shares of Tempus Common Stock.
The closing of the First Merger will take place by electronic exchange of deliverables as promptly as practicable, and in any event no later than 8:00 a.m. (New York City time) on the third business day after the satisfaction or, to the extent permitted under the Merger Agreement and applicable law, waiver of the closing conditions set forth in the Merger Agreement (other than those conditions that by their nature are to be satisfied at the closing of the First Merger, but subject to the satisfaction or, to the extent permitted by applicable law, waiver, of such conditions), unless another date, time or place is agreed in writing by Tempus and Personalis (the “Closing”). The date on which the Closing takes place is referred to herein as the “Closing Date.”
The board of directors of Tempus (the “Tempus Board”) has unanimously (a) determined that the Merger Agreement and the various transactions contemplated by the Merger Agreement (the “Transactions”), including the Mergers and the payment of the Merger Consideration, are advisable and in the best interests of Tempus and its stockholders and (b) approved the Merger Agreement and the Transactions, including the Mergers and the Merger Consideration, on the terms and subject to the conditions set forth in the Merger Agreement.
The board of directors of Personalis (the “Personalis Board”) has unanimously (a) determined that the terms of the Merger Agreement and the Transactions, including the Mergers, are fair to, and in the best interests of, Personalis and Personalis Stockholders, (b) determined that it is in the best interests of Personalis and Personalis Stockholders and declared it advisable to enter into the Merger Agreement, (c) approved the execution and delivery by Personalis of the Merger Agreement, the performance by Personalis of its covenants and agreements contained therein and the consummation of the Mergers and the other transactions contemplated thereby upon the terms and subject to the conditions contained therein, and (d) subject to the terms and conditions set forth in the Merger Agreement, resolved to recommend that Personalis Stockholders adopt the Merger Agreement.
In connection with the Mergers, Personalis will hold a special meeting of its stockholders (as the same may be adjourned or postponed, the “Personalis Special Meeting”). At the Personalis Special Meeting, the Personalis Stockholders will be asked to consider and vote on proposals to (i) adopt the Merger Agreement and thereby approve the transactions contemplated thereby, including the Mergers (the “Merger Proposal”), (ii) approve, on a nonbinding, advisory basis, compensation that will or may become payable by Personalis to its named executive officers in connection with the Mergers (the “Merger Compensation Proposal”), and (iii) approve one or more adjournments of the Personalis Special Meeting to a later date or dates, if necessary or appropriate, to solicit additional proxies in the event there are not sufficient votes at the time of the Personalis Special Meeting to approve the Merger Proposal (the “Adjournment Proposal”). Concurrently with the execution of the Merger Agreement, Personalis entered into a Voting Agreement (the “Voting Agreement”) with Merck Sharp & Dohme LLC (“Merck”), which beneficially owns shares of Personalis Common Stock representing approximately 13% of the voting power of the outstanding shares of Personalis Common Stock as of July 20, 2026. Under the Voting Agreement, Merck agreed to, among other things, vote all shares of Personalis Common Stock owned of record or beneficially by Merck, or over which Merck exercises voting power, in favor of the adoption of the Merger Agreement and the approval of the Mergers and the other transactions contemplated by the Merger Agreement, and against any competing Acquisition Proposal, at the Personalis Special Meeting.
Concurrently with the filing of this Transaction Statement, Tempus is filing with the SEC a Registration Statement on Form S-4, which includes a prospectus of Tempus and a proxy statement of Personalis (the “Proxy Statement/Prospectus”) in connection with the Merger Agreement and the transactions contemplated thereby. A copy of the Proxy Statement/Prospectus is attached hereto as Exhibit (a)(1). A copy of the Merger Agreement is attached as Annex A to the Proxy Statement/Prospectus. All references in this Transaction Statement to Items numbered 1001 to 1016 are references to Items contained in Regulation M-A under the Exchange Act. As of the date hereof, the Proxy Statement/Prospectus is in preliminary form and is subject to completion or amendment. Capitalized terms used but not defined in this Transaction Statement have the meanings assigned to them in the Proxy Statement/Prospectus.
2
Pursuant to General Instruction F to Schedule 13E-3, the information contained in the Proxy Statement/Prospectus, including all annexes thereto, is expressly incorporated by reference in its entirety and responses to each item herein are qualified in their entirety by the information contained in the Proxy Statement/Prospectus and the annexes thereto. The cross-references below are being supplied pursuant to General Instructions G to Schedule 13E-3 and show the location in the Proxy Statement/Prospectus of the information required to be included in response to the items of Schedule 13E-3.
Although each of the Filing Persons acknowledges that the Mergers may collectively be deemed to constitute a “going private” transaction for purposes of Rule 13e-3 under the Exchange Act, the filing of this Transaction Statement shall not be construed as an admission by any Filing Person, or by any affiliate of a Filing Person, that Personalis is “controlled” by any of the Filing Persons and/or their respective affiliates.
All information concerning Personalis contained in, or incorporated by reference into, this Transaction Statement and the Proxy Statement/Prospectus was supplied by Personalis. Similarly, all information concerning any other Filing Person contained in, or incorporated by reference into, this Transaction Statement and the Proxy Statement/Prospectus was supplied by such Filing Person.
| ITEM 1. | SUMMARY TERM SHEET |
Regulation M-A Item 1001
The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference:
“SUMMARY TERM SHEET”
“QUESTIONS AND ANSWERS”
| ITEM 2. | SUBJECT COMPANY INFORMATION |
Regulation M-A Item 1002
| (a) | Name and Address. Personalis’ name, and the address and telephone number of its principal executive offices are: |
Personalis, Inc.
6600 Dumbarton Circle
Fremont, California 94555
(650) 752-1300
| (b) | Securities. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“SUMMARY TERM SHEET”
“SPECIAL FACTORS—Certain Effects of the Mergers on the Parent Filing Parties”
“SPECIAL MEETING OF PERSONALIS STOCKHOLDERS—Record Date; Stockholders Entitled to Vote”
“IMPORTANT INFORMATION REGARDING PERSONALIS—Security Ownership of Certain Beneficial Holders and Management of Personalis”
“COMPARISON OF STOCKHOLDERS’ RIGHTS”
| (c) | Trading Market and Price. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“IMPORTANT INFORMATION REGARDING PERSONALIS—Price Range of Personalis Common Stock”
3
| (d) | Dividends. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“THE MERGER AGREEMENT—Conduct of Personalis’ Business Pending the Mergers”
“THE MERGER AGREEMENT—Conduct of Tempus’ Business Pending the Mergers”
“IMPORTANT INFORMATION REGARDING PERSONALIS—Dividends”
“COMPARISON OF STOCKHOLDERS’ RIGHTS”
| (e) | Prior Public Offerings. The information set forth in the Proxy Statement/Prospectus under the following caption is incorporated herein by reference: |
“IMPORTANT INFORMATION REGARDING PERSONALIS—Prior Public Offerings”
“IMPORTANT INFORMATION REGARDING PERSONALIS—Prior Sales of Unregistered Securities”
| (f) | Prior Stock Purchases. The information set forth in the Proxy Statement/Prospectus under the following caption is incorporated herein by reference: |
“IMPORTANT INFORMATION REGARDING PERSONALIS—Prior Sales of Unregistered Securities”
“IMPORTANT INFORMATION REGARDING PERSONALIS—Purchases in Connection with the Mergers”
“IMPORTANT INFORMATION REGARDING TEMPUS—Prior Personalis Stock Purchases”
“IMPORTANT INFORMATION REGARDING SCHEDULE 13E-3 FILING PARTIES OTHER THAN TEMPUS AND PERSONALIS—Prior Personalis Stock Purchases”
| ITEM 3. | IDENTITY AND BACKGROUND OF FILING PERSON |
Regulation M-A Item 1003
(a) – (b) Name and Address; Business and Background of Entities. Personalis is the issuer of the equity securities that are the subject of the Rule 13e-3 transaction reported hereby. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference:
“SUMMARY TERM SHEET—Parties to the Mergers”
“PARTIES TO THE MERGERS”
“IMPORTANT INFORMATION REGARDING PERSONALIS—Business and Background of Directors and Executive Officers of Personalis”
“IMPORTANT INFORMATION REGARDING TEMPUS—Business and Background of Directors and Executive Officers of Tempus”
“IMPORTANT INFORMATION REGARDING SCHEDULE 13E-3 FILING PARTIES OTHER THAN TEMPUS AND PERSONALIS—Name and Address; Business and Background of Schedule 13E-3 Individual Filing Parties Other than Tempus and Personalis”
“WHERE YOU CAN FIND MORE INFORMATION”
| (c) | Business and Background of Natural Persons. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“IMPORTANT INFORMATION REGARDING PERSONALIS—Business and Background of Directors and Executive Officers of Personalis”
“IMPORTANT INFORMATION REGARDING TEMPUS—Business and Background of Directors and Executive Officers of Tempus”
“IMPORTANT INFORMATION REGARDING SCHEDULE 13E-3 FILING PARTIES OTHER THAN TEMPUS AND PERSONALIS—Name and Address; Business and Background of Schedule 13E-3 Individual Filing Parties Other than Tempus and Personalis”
“WHERE YOU CAN FIND MORE INFORMATION”
| ITEM 4. | TERMS OF THE TRANSACTION |
Regulation M-A Item 1004
| (a) | (1) Material Terms – Tender Offers. Not applicable. |
4
| (a) | (2) Material Terms – Merger or Similar Transactions. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“SUMMARY TERM SHEET”
“RISK FACTORS”
“QUESTIONS AND ANSWERS”
“SPECIAL FACTORS—General”
“SPECIAL FACTORS—Background of the Mergers”
“SPECIAL FACTORS—Purpose and Reasons of Personalis for the Mergers; Recommendation of the Personalis Board; Fairness”
“SPECIAL FACTORS—Reasons for the Mergers of the Parent Filing Parties; Fairness”
“SPECIAL FACTORS—Intent to Vote”
“SPECIAL FACTORS—Unaudited Prospective Financial Information – Personalis”
“SPECIAL FACTORS—Unaudited Prospective Financial Information – Tempus”
“SPECIAL FACTORS—Opinion of Morgan Stanley & Co. LLC”
“SPECIAL FACTORS—Plans for Personalis After the Mergers”
“SPECIAL FACTORS—Certain Effects of the Mergers on Personalis”
“SPECIAL FACTORS—Certain Effects of the Mergers on the Parent Filing Parties”
“SPECIAL FACTORS—Governance of Personalis After the Mergers”
“SPECIAL FACTORS—Interests of Tempus Directors and Officers in the Mergers”
“SPECIAL FACTORS—Interests of Personalis Directors and Officers in the Mergers”
“SPECIAL FACTORS—Regulatory Approvals”
“SPECIAL FACTORS—Accounting Treatment of the Mergers”
“SPECIAL FACTORS—Delisting and Deregistration of Personalis Common Stock”
“SPECIAL FACTORS—Litigation Relating to the Mergers”
“THE MERGER AGREEMENT”
“COMPARISON OF STOCKHOLDERS’ RIGHTS”
“SPECIAL MEETING OF PERSONALIS STOCKHOLDERS—Required Vote”
“MATERIAL U.S. FEDERAL INCOME TAX CONSEQUENCES OF THE MERGERS”
“Annex A: Merger Agreement”
| (c) | Different Terms. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“SUMMARY TERM SHEET”
“QUESTIONS AND ANSWERS”
“SPECIAL FACTORS—Interests of Tempus Directors and Officers in the Mergers”
“SPECIAL FACTORS—Interests of Personalis Directors and Officers in the Mergers”
“THE MERGER AGREEMENT—Treatment of Personalis Equity Awards”
“THE MERGER AGREEMENT—Employee Matters”
“THE MERGER AGREEMENT—Indemnification; Directors and Officers Insurance”
“PROPOSAL 2—NON-BINDING ADVISORY VOTE ON MERGER COMPENSATION PROPOSAL”
“Annex A: Merger Agreement”
| (d) | Appraisal Rights. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“SUMMARY TERM SHEET—Appraisal Rights”
“RISK FACTORS”
“QUESTIONS AND ANSWERS”
“SPECIAL MEETING OF PERSONALIS STOCKHOLDERS—Appraisal Rights”
“THE MERGER AGREEMENT—Appraisal Rights”
“COMPARISON OF STOCKHOLDERS’ RIGHTS”
“APPRAISAL RIGHTS”
5
| (e) | Provisions for Unaffiliated Security Holders. The information set forth in the Proxy Statement/Prospectus under the following caption is incorporated herein by reference: |
“SPECIAL FACTORS—Availability of Documents”
| (f) | Eligibility for Listing or Trading. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“SUMMARY TERM SHEET—Listing of Tempus’ Class A Common Stock and Delisting and Deregistration of Personalis Common Stock”
“QUESTIONS AND ANSWERS”
“THE MERGER AGREEMENT—Conditions to the Mergers”
“DELISTING AND DEREGISTRATION OF PERSONALIS COMMON STOCK”
| ITEM 5. | PAST CONTACTS, TRANSACTIONS, NEGOTIATIONS AND AGREEMENTS |
Regulation M-A Item 1005
| (a) | (1) – (2) Transactions. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“SUMMARY TERM SHEET”
“SPECIAL FACTORS—Interests of Tempus Directors and Officers in the Mergers”
“SPECIAL FACTORS—Interests of Personalis Directors and Officers in the Mergers”
“SPECIAL FACTORS—Certain Related Party Agreements between Tempus and Other Filing Parties”
“IMPORTANT INFORMATION REGARDING PERSONALIS—Prior Sales of Unregistered Securities”
“IMPORTANT INFORMATION REGARDING PERSONALIS—Past Contacts, Transactions, Negotiations and Agreements”
(b)–(c) Significant Corporate Events; Negotiations or Contacts. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference:
“SUMMARY TERM SHEET”
“SPECIAL FACTORS—Background of the Mergers”
“SPECIAL FACTORS—Purpose and Reasons of Personalis for the Mergers; Recommendation of the Personalis Board; Fairness”
“SPECIAL FACTORS—Reasons for the Mergers of the Parent Filing Parties; Fairness”
“SPECIAL FACTORS—Interests of Tempus Directors and Officers in the Mergers”
“SPECIAL FACTORS—Interests of Personalis Directors and Officers in the Mergers”
“SPECIAL FACTORS—Certain Related Party Agreements between Tempus and Other Filing Parties”
“THE MERGER AGREEMENT”
“IMPORTANT INFORMATION REGARDING PERSONALIS—Prior Sales of Unregistered Securities”
“IMPORTANT INFORMATION REGARDING PERSONALIS—Past Contacts, Transactions, Negotiations and Agreements”
“Annex A: Merger Agreement”
| (e) | Agreements Involving the Subject Company’s Securities. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“SUMMARY TERM SHEET”
“QUESTIONS AND ANSWERS”
“SPECIAL FACTORS—Background of the Mergers”
“SPECIAL FACTORS—Certain Effects of the Mergers on Personalis”
“SPECIAL FACTORS—Certain Effects of the Mergers on the Parent Filing Parties”
“SPECIAL FACTORS—Interests of Tempus Directors and Officers in the Mergers”
“SPECIAL FACTORS—Interests of Personalis Directors and Officers in the Mergers”
“THE MERGER AGREEMENT”
6
“THE VOTING AGREEMENT”
“IMPORTANT INFORMATION REGARDING PERSONALIS—Prior Sales of Unregistered Securities”
“IMPORTANT INFORMATION REGARDING PERSONALIS—Past Contacts, Transactions, Negotiations and Agreements”
“Annex A: Merger Agreement”
“Annex F: Voting Agreement”
| ITEM 6. | PURPOSES OF THE TRANSACTION AND PLANS OR PROPOSALS. |
Regulation M-A Item 1006
| (b) | Use of Securities Acquired. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“SUMMARY TERM SHEET”
“QUESTIONS AND ANSWERS”
“SPECIAL FACTORS—Reasons for the Mergers of the Parent Filing Parties; Fairness”
“SPECIAL FACTORS—Certain Effects of the Mergers on Personalis”
“SPECIAL FACTORS—Certain Effects of the Mergers on the Parent Filing Parties”
“SPECIAL FACTORS—Delisting and Deregistration of Personalis Common Stock”
“THE MERGER AGREEMENT—Merger Consideration; Proration”
“DELISTING AND DEREGISTRATION OF PERSONALIS COMMON STOCK”
“Annex A: Merger Agreement”
| (c) | (1) – (8) Plans. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“SUMMARY TERM SHEET”
“QUESTIONS AND ANSWERS”
“SPECIAL FACTORS—Background of the Mergers”
“SPECIAL FACTORS—Purpose and Reasons of Personalis for the Mergers; Recommendation of the Personalis Board; Fairness”
“SPECIAL FACTORS—Reasons for the Mergers of the Parent Filing Parties; Fairness”
“SPECIAL FACTORS—Plans for Personalis After the Mergers”
“SPECIAL FACTORS—Certain Effects of the Mergers on Personalis”
“SPECIAL FACTORS—Certain Effects of the Mergers on the Parent Filing Parties”
“SPECIAL FACTORS—Governance of Personalis After the Mergers”
“SPECIAL FACTORS—Interests of Tempus Directors and Officers in the Mergers”
“SPECIAL FACTORS—Interests of Personalis Directors and Officers in the Mergers”
“SPECIAL FACTORS—Delisting and Deregistration of Personalis Common Stock”
“THE MERGER AGREEMENT”
“DELISTING AND DEREGISTRATION OF PERSONALIS COMMON STOCK”
“Annex A: Merger Agreement”
“Annex F: Voting Agreement”
| ITEM 7. | PURPOSES, ALTERNATIVES, REASONS AND EFFECTS |
Regulation M-A Item 1013
| (a) | Purposes. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“SUMMARY TERM SHEET”
“QUESTIONS AND ANSWERS”
“SPECIAL FACTORS—Background of the Mergers”
“SPECIAL FACTORS—Purpose and Reasons of Personalis for the Mergers; Recommendation of the Personalis Board; Fairness”
7
“SPECIAL FACTORS—Reasons for the Mergers of the Parent Filing Parties; Fairness”
“SPECIAL FACTORS—Plans for Personalis After the Mergers”
“SPECIAL FACTORS—Certain Effects of the Mergers on Personalis”
“SPECIAL FACTORS—Certain Effects of the Mergers on the Parent Filing Parties”
“SPECIAL FACTORS—Interests of Tempus Directors and Officers in the Mergers”
“SPECIAL FACTORS—Interests of Personalis Directors and Officers in the Mergers”
| (b) | Alternatives. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“SPECIAL FACTORS—Background of the Mergers”
“SPECIAL FACTORS—Purpose and Reasons of Personalis for the Mergers; Recommendation of the Personalis Board; Fairness”
“SPECIAL FACTORS—Reasons for the Mergers of the Parent Filing Parties; Fairness”
“SPECIAL FACTORS—Unaudited Prospective Financial Information – Personalis”
“SPECIAL FACTORS—Unaudited Prospective Financial Information – Tempus”
| (c) | Reasons. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“SUMMARY TERM SHEET”
“QUESTIONS AND ANSWERS”
“SPECIAL FACTORS—Background of the Mergers”
“SPECIAL FACTORS—Purpose and Reasons of Personalis for the Mergers; Recommendation of the Personalis Board; Fairness”
“SPECIAL FACTORS—Reasons for the Mergers of the Parent Filing Parties; Fairness”
“SPECIAL FACTORS—Unaudited Prospective Financial Information – Personalis”
“SPECIAL FACTORS—Unaudited Prospective Financial Information – Tempus”
“SPECIAL FACTORS—Opinions of Personalis’ Financial Advisors”
“SPECIAL FACTORS—Opinion of Morgan Stanley & Co. LLC”
“SPECIAL FACTORS—Plans for Personalis After the Mergers”
“SPECIAL FACTORS—Certain Effects of the Mergers on Personalis”
“SPECIAL FACTORS—Certain Effects of the Mergers on the Parent Filing Parties”
“SPECIAL FACTORS—Interests of Personalis Directors and Officers in the Mergers”
“Annex B: Opinion of Centerview Partners LLC”
“Annex C: Opinion of TD Securities (USA) LLC”
“Annex D: Opinion of Morgan Stanley & Co. LLC”
| (d) | Effects. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“SUMMARY TERM SHEET”
“QUESTIONS AND ANSWERS”
“SPECIAL FACTORS—Background of the Mergers”
“SPECIAL FACTORS—Purpose and Reasons of Personalis for the Mergers; Recommendation of the Personalis Board; Fairness”
“SPECIAL FACTORS—Reasons for the Mergers of the Parent Filing Parties; Fairness”
“SPECIAL FACTORS—Plans for Personalis After the Mergers”
“SPECIAL FACTORS—Certain Effects of the Mergers on Personalis”
“SPECIAL FACTORS—Certain Effects of the Mergers on the Parent Filing Parties”
“SPECIAL FACTORS—Governance of Personalis After the Mergers”
“SPECIAL FACTORS—Interests of Tempus Directors and Officers in the Mergers”
“SPECIAL FACTORS—Interests of Personalis Directors and Officers in the Mergers”
“SPECIAL FACTORS—Accounting Treatment of the Mergers”
“SPECIAL FACTORS—Delisting and Deregistration of Personalis Common Stock”
“THE MERGER AGREEMENT”
“IMPORTANT INFORMATION REGARDING PERSONALIS—Costs to Personalis of the Mergers”
8
“MATERIAL U.S. FEDERAL INCOME TAX CONSEQUENCES OF THE MERGERS”
“COMPARISON OF STOCKHOLDERS’ RIGHTS”
“APPRAISAL RIGHTS”
“DELISTING AND DEREGISTRATION OF PERSONALIS COMMON STOCK”
“Annex A: Merger Agreement”
| ITEM 8. | FAIRNESS OF THE TRANSACTION |
Regulation M-A Item 1014
(a) – (b) Fairness; Factors Considered in Determining Fairness. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference:
“SUMMARY TERM SHEET”
“QUESTIONS AND ANSWERS”
“SPECIAL FACTORS—Background of the Mergers”
“SPECIAL FACTORS—Purpose and Reasons of Personalis for the Mergers; Recommendation of the Personalis Board; Fairness”
“SPECIAL FACTORS—Reasons for the Mergers of the Parent Filing Parties; Fairness”
“SPECIAL FACTORS—Opinions of Personalis’ Financial Advisors”
“SPECIAL FACTORS—Opinion of Morgan Stanley & Co. LLC”
“Annex B: Opinion of Centerview Partners LLC”
“Annex C: Opinion of TD Securities (USA) LLC”
“Annex D: Opinion of Morgan Stanley & Co. LLC”
| (c) | Approval of Security Holders. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“SUMMARY TERM SHEET”
“QUESTIONS AND ANSWERS”
“SPECIAL FACTORS—Purpose and Reasons of Personalis for the Mergers; Recommendation of the Personalis Board; Fairness”
“SPECIAL MEETING OF PERSONALIS STOCKHOLDERS—Required Vote”
“COMPARISON OF STOCKHOLDERS’ RIGHTS”
“PROPOSAL 1—THE MERGER PROPOSAL”
| (d) | Unaffiliated Representative. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“SPECIAL FACTORS—Background of the Mergers”
“SPECIAL FACTORS—Purpose and Reasons of Personalis for the Mergers; Recommendation of the Personalis Board; Fairness”
“SPECIAL FACTORS—Certain Effects of the Mergers on Personalis”
“SPECIAL FACTORS—Certain Effects of the Mergers on the Parent Filing Parties”
“SPECIAL FACTORS—Interests of Personalis Directors and Officers in the Mergers”
| (e) | Approval of Directors. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“SUMMARY TERM SHEET”
“QUESTIONS AND ANSWERS”
“SPECIAL FACTORS—Background of the Mergers”
“SPECIAL FACTORS—Purpose and Reasons of Personalis for the Mergers; Recommendation of the Personalis Board; Fairness”
“SPECIAL FACTORS—Interests of Personalis Directors and Officers in the Mergers”
“PROPOSAL 1—THE MERGER PROPOSAL”
9
| (f) | Other Offers. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“SPECIAL FACTORS—Background of the Mergers”
“SPECIAL FACTORS—Purpose and Reasons of Personalis for the Mergers; Recommendation of the Personalis Board; Fairness”
| ITEM 9. | REPORTS, OPINIONS, APPRAISALS AND NEGOTIATIONS |
Regulation M-A Item 1015
(a) – (b) Report, Opinion or Appraisal; Preparer and Summary of the Report, Opinion or Appraisal.
Each of the following discussion materials are filed as Exhibits (c)(4) through (c)(17) hereto and are incorporated herein by reference, as follows:
| i. | Joint preliminary discussion materials prepared by Centerview Partners LLC and TD Securities (USA) LLC and provided to the Personalis Board, dated February 2, 2026 |
| ii. | Joint preliminary discussion materials prepared by Centerview Partners LLC and TD Securities (USA) LLC and provided to the Personalis Board, dated February 6, 2026 |
| iii. | Joint preliminary discussion materials prepared by Centerview Partners LLC and TD Securities (USA) LLC and provided to the Personalis Board, dated April 28, 2026 |
| iv. | Joint preliminary discussion materials prepared by Centerview Partners LLC and TD Securities (USA) LLC and provided to the Personalis Board, dated May 29, 2026 |
| v. | Joint preliminary discussion materials prepared by Centerview Partners LLC and TD Securities (USA) LLC and provided to the Personalis Board, dated June 5, 2026 |
| vi. | Joint preliminary discussion materials prepared by Centerview Partners LLC and TD Securities (USA) LLC and provided to the Personalis Board, dated June 19, 2026 |
| vii. | Joint preliminary discussion materials prepared by Centerview Partners LLC and TD Securities (USA) LLC and provided to the Personalis Board, dated June 25, 2026 |
| viii. | Joint preliminary discussion materials prepared by Centerview Partners LLC and TD Securities (USA) LLC and provided to the Personalis Board, dated June 30, 2026 |
| ix. | Joint preliminary discussion materials prepared by Centerview Partners LLC and TD Securities (USA) LLC and provided to the Personalis Board, dated July 2, 2026 |
| x. | Joint preliminary discussion materials prepared by Centerview Partners LLC and TD Securities (USA) LLC and provided to the Personalis Board, dated July 10, 2026 |
| xi. | Joint preliminary discussion materials prepared by Centerview Partners LLC and TD Securities (USA) LLC and provided to the Personalis Board, dated July 15, 2026 |
| xii. | Joint preliminary discussion materials prepared by Centerview Partners LLC and TD Securities (USA) LLC and provided to the Personalis Board, dated July 18, 2026 |
| xiii. | Discussion materials prepared by Centerview Partners LLC and provided to the Personalis Board, dated July 19, 2026 |
| xiv. | Discussion materials prepared by TD Securities (USA) LLC and provided to the Personalis Board, dated July 19, 2026 |
10
The discussion materials prepared by Morgan Stanley & Co. LLC and provided to the Tempus Board, dated July 18, 2026 and July 19, 2026 are filed as Exhibit (c)(18) and Exhibit (c)(19), respectively, hereto and are incorporated herein by reference.
The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference:
“SUMMARY TERM SHEET”
“SPECIAL FACTORS—Background of the Mergers”
“SPECIAL FACTORS—Purpose and Reasons of Personalis for the Mergers; Recommendation of the Personalis Board; Fairness”
“SPECIAL FACTORS—Opinions of Personalis’ Financial Advisors”
“SPECIAL FACTORS—Opinion of Morgan Stanley & Co. LLC”
“Annex B: Opinion of Centerview Partners LLC”
“Annex C: Opinion of TD Securities (USA) LLC”
“Annex D: Opinion of Morgan Stanley & Co. LLC”
| (c) | Availability of Documents. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“SPECIAL FACTORS—Availability of Documents”
“WHERE YOU CAN FIND MORE INFORMATION”
The reports, opinions or appraisals referenced in this Item 9 are filed herewith and will be made available for inspection and copying at the principal executive offices of Personalis during its regular business hours by any interested equity security holder of Personalis Common Stock or by any representative who has been so designated in writing upon written request and at the expense of the requesting holder of Personalis Common Stock.
| ITEM 10. | SOURCE AND AMOUNTS OF FUNDS OR OTHER CONSIDERATION |
Regulation M-A Item 1007
(a) – (b) Source of Funds; Conditions. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference:
“SUMMARY TERM SHEET”
“RISK FACTORS—Risks Related to the Combined Company Upon Completion of the Mergers—The combined company’s debt may limit its financial flexibility and adversely affect its financial condition, liquidity and results of operations.”
“SPECIAL FACTORS—Background of the Mergers”
“SPECIAL FACTORS—Purpose and Reasons of Personalis for the Mergers; Recommendation of the Personalis Board; Fairness”
“SPECIAL FACTORS—Financing of the Mergers”
“THE MERGER AGREEMENT—Merger Consideration; Proration”
| (c) | Expenses. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“SUMMARY TERM SHEET—Termination Fees and Expenses”
“RISK FACTORS—Risks Related to the Mergers—Tempus and Personalis may incur substantial transaction-related costs in connection with the Mergers.”
“THE MERGER AGREEMENT—Expenses”
“THE MERGER AGREEMENT—Termination Fee”
“IMPORTANT INFORMATION REGARDING PERSONALIS—Costs to Personalis of the Mergers”
11
| (d) | Borrowed Funds. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“SPECIAL FACTORS—Financing of the Mergers”
“RISK FACTORS”
“THE MERGER AGREEMENT—Merger Consideration; Proration”
| ITEM 11. | INTEREST IN SECURITIES OF THE SUBJECT COMPANY |
Regulation M-A Item 1008
| (a) | Securities Ownership. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“SUMMARY TERM SHEET—Parties to the Mergers”
“PARTIES TO THE MERGERS”
“THE MERGER AGREEMENT”
“IMPORTANT INFORMATION REGARDING PERSONALIS—Business and Background of Directors and Executive Officers of Personalis”
“IMPORTANT INFORMATION REGARDING PERSONALIS—Security Ownership of Certain Beneficial Holders and Management of Personalis”
“IMPORTANT INFORMATION REGARDING TEMPUS—Security Ownership of Certain Beneficial Holders and Management of Tempus”
“IMPORTANT INFORMATION REGARDING TEMPUS—Business and Background of Directors and Executive Officers of Tempus”
“IMPORTANT INFORMATION REGARDING SCHEDULE 13E-3 FILING PARTIES OTHER THAN TEMPUS AND PERSONALIS—Name and Address; Business and Background of Schedule 13E-3 Individual Filing Parties Other Than Tempus and Personalis”
| (b) | Securities Transactions. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“THE MERGER AGREEMENT”
“THE VOTING AGREEMENT”
“IMPORTANT INFORMATION REGARDING TEMPUS—Prior Personalis Stock Purchases”
“IMPORTANT INFORMATION REGARDING SCHEDULE 13E-3 FILING PARTIES OTHER THAN TEMPUS AND PERSONALIS—Prior Personalis Stock Purchases”
“Annex A: Merger Agreement”
“Annex F: Voting Agreement”
| ITEM 12. | THE SOLICITATION OR RECOMMENDATION |
Regulation M-A Item 1012
| (d) | Intent to Tender or Vote in a Going-Private Transaction. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“SUMMARY TERM SHEET”
“QUESTIONS AND ANSWERS—What is the vote required to approve each proposal at the Personalis Special Meeting?”
“SPECIAL FACTORS—Intent to Vote”
“SPECIAL MEETING OF PERSONALIS STOCKHOLDERS—Voting by the Personalis Directors and Executive Officers”
“THE MERGER AGREEMENT”
“THE VOTING AGREEMENT”
12
| (e) | Recommendations of Others. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference: |
“SUMMARY TERM SHEET”
“QUESTIONS AND ANSWERS—How does the Personalis Board recommend that the Personalis Stockholders vote?”
“SPECIAL FACTORS—Purpose and Reasons of Personalis for the Mergers; Recommendation of the Personalis Board; Fairness”
“SPECIAL FACTORS—Interests of Personalis Directors and Officers in the Mergers”
“THE MERGER AGREEMENT—No Change in Board Recommendation; No Entry into Alternative Transactions”
“PROPOSAL 1—THE MERGER PROPOSAL”
| ITEM 13. | FINANCIAL STATEMENTS |
Regulation M-A Item 1010
| (a) | Financial Information. The audited consolidated financial statements of Personalis for the fiscal years ended December 31, 2025 and 2024 are incorporated herein by reference to Personalis’ Annual Report on Form 10-K for the fiscal year ended December 31, 2025, filed on February 26, 2026 (see “Item 8. Financial Statements and Supplementary Data” beginning on page 69). The consolidated financial statements set forth in Item 1 of Personalis’ Quarterly Report on Form 10-Q for the quarterly period ended June 30, 2026, filed on August 4, 2026, are incorporated herein by reference. |
The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference:
“SPECIAL FACTORS—Certain Effects of the Mergers on Personalis”
“SPECIAL FACTORS—Certain Effects of the Mergers on the Parent Filing Parties”
“SPECIAL FACTORS—Unaudited Prospective Financial Information – Personalis”
“SPECIAL FACTORS—Unaudited Prospective Financial Information – Tempus”
“IMPORTANT INFORMATION REGARDING PERSONALIS—Book Value per Share”
“WHERE YOU CAN FIND MORE INFORMATION”
| (b) | Pro Forma Information. Not applicable. |
| ITEM 14. | PERSONS/ASSETS, RETAINED, EMPLOYED, COMPENSATED OR USED |
Regulation M-A Item 1009
(a) – (b) Solicitations or Recommendations; Employees and Corporate Assets. The information set forth in the Proxy Statement/Prospectus under the following captions is incorporated herein by reference:
“SUMMARY TERM SHEET”
“QUESTIONS AND ANSWERS”
“SPECIAL FACTORS—Background of the Mergers”
“SPECIAL FACTORS—Purpose and Reasons of Personalis for the Mergers; Recommendation of the Personalis Board; Fairness”
“SPECIAL FACTORS—Interests of Personalis Directors and Officers in the Mergers”
“SPECIAL MEETING OF PERSONALIS STOCKHOLDERS—General”
“SPECIAL MEETING OF PERSONALIS STOCKHOLDERS—Solicitations of Proxies”
13
| ITEM 15. | ADDITIONAL INFORMATION |
Regulation M-A Item 1011
| (b) | Golden Parachute Compensation. The information set forth in the Proxy Statement/Prospectus under the following caption is incorporated herein by reference. |
“SUMMARY TERM SHEET”
“QUESTIONS AND ANSWERS”
“SPECIAL FACTORS—Certain Effects of the Mergers on Personalis”
“SPECIAL FACTORS—Certain Effects of the Mergers on the Parent Filing Parties”
“SPECIAL FACTORS—Interests of Tempus Directors and Officers in the Mergers”
“SPECIAL FACTORS—Interests of Personalis Directors and Officers in the Mergers”
“THE MERGER AGREEMENT—Effects of the Mergers; Directors and Officers”
“THE MERGER AGREEMENT—Treatment of Personalis Equity Awards”
“PROPOSAL 2—NON-BINDING ADVISORY VOTE ON MERGER COMPENSATION PROPOSAL”
“Annex A: Merger Agreement”
| (c) | Other Material Information. The information set forth in the Proxy Statement/Prospectus, including all annexes thereto, is incorporated herein by reference. |
| ITEM 16. | EXHIBITS |
Regulation M-A Item 1016
14
15
| ** | Certain portions of this exhibit have been redacted and separately filed with the Securities and Exchange Commission pursuant to a request for confidential treatment. |
16
SIGNATURES
After due inquiry and to the best of each of the undersigned’s knowledge and belief, each of the undersigned certifies that the information set forth in this statement is true, complete and correct.
Dated as of August 31, 2026
| PERSONALIS, INC. | ||
| By: | /s/ Christopher Hall | |
| Name: | Christopher Hall | |
| Title: | Chief Executive Officer | |
| TEMPUS AI, INC. | ||
| By: | /s/ James Rogers | |
| Name: | James Rogers | |
| Title: | Chief Financial Officer | |
| AVIARY DEVELOPMENT, INC. | ||
| By: | /s/ James Rogers | |
| Name: | James Rogers | |
| Title: | Treasurer | |
| TOUCAN DEVELOPMENT, LLC | ||
| By: | /s/ Andrew K. Polovin | |
| Name: | Andrew K. Polovin | |
| Title: | Manager | |
| ERIC LEFKOFSKY | ||
| By: | /s/ Eric Lefkofsky | |
| Name: | Eric Lefkofsky | |
17
–Preliminary Draft: For Discussion Purposes Only – Exhibit (c)(4) Project Aviary Presentation to the Board of Directors February 2, 2026
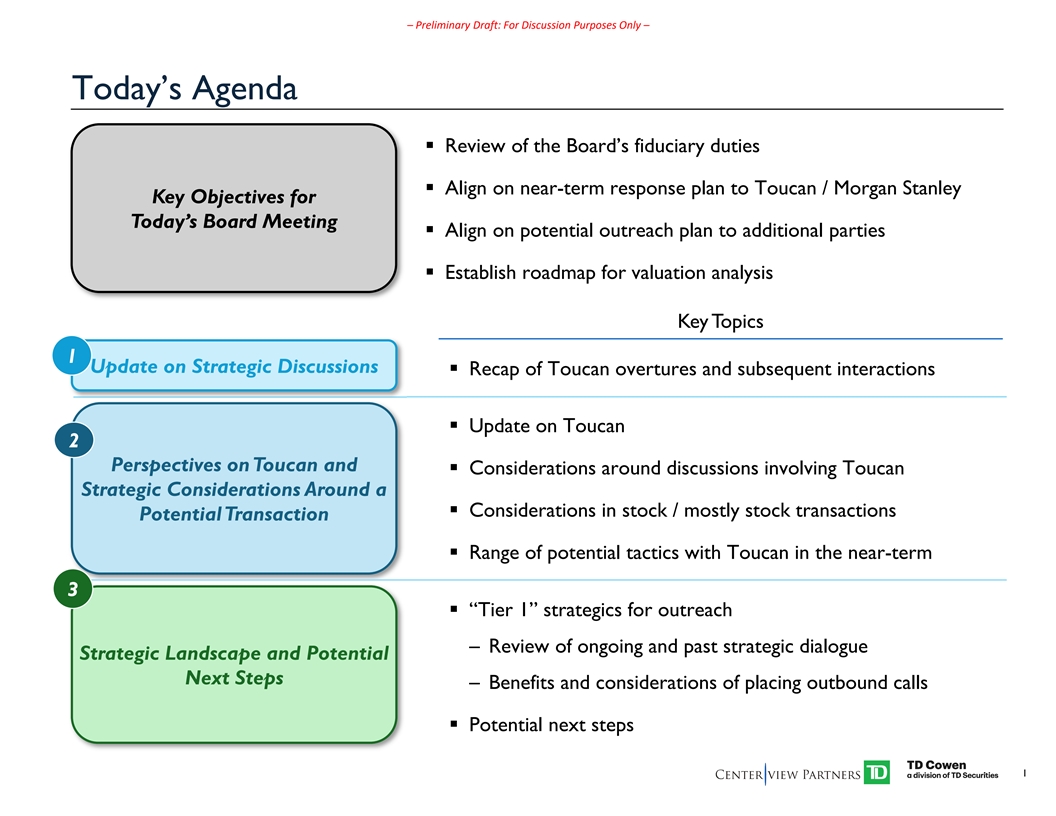
–Preliminary Draft: For Discussion Purposes Only – Today’s Agenda § Review of the Board’s fiduciary duties § Align on near-term response plan to Toucan / Morgan Stanley Key Objectives for Today’s Board Meeting § Align on potential outreach plan to additional parties § Establish roadmap for valuation analysis Key T opics 1 Update on Strategic Discussions § Recap of Toucan overtures and subsequent interactions § Update on Toucan 2 Perspectives on Toucan and § Considerations around discussions involving Toucan Strategic Considerations Around a § Considerations in stock / mostly stock transactions Potential Transaction § Range of potential tactics with Toucan in the near-term 3 § “Tier 1” strategics for outreach – Review of ongoing and past strategic dialogue Strategic Landscape and Potential Next Steps – Benefits and considerations of placing outbound calls § Potential next steps 1
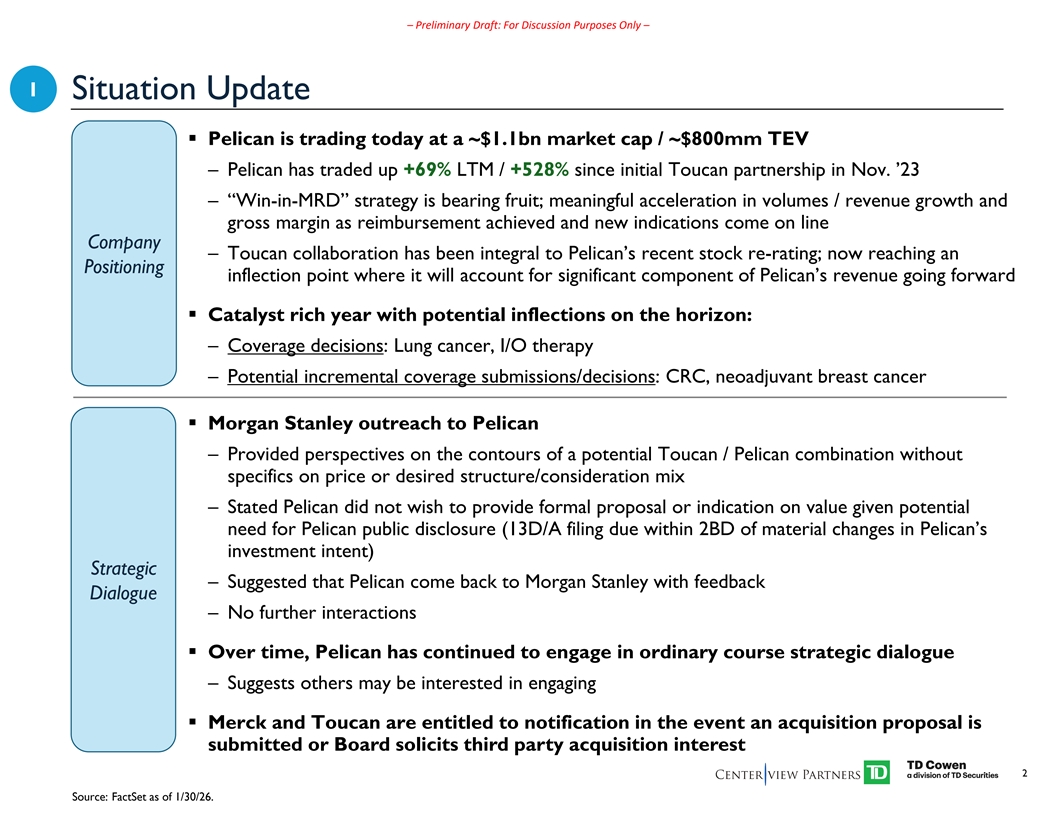
–Preliminary Draft: For Discussion Purposes Only – 1 Situation Update § Pelican is trading today at a ~$1.1bn market cap / ~$800mm TEV – Pelican has traded up +69% LTM / +528% since initial Toucan partnership in Nov. ’23 – “Win-in-MRD” strategy is bearing fruit; meaningful acceleration in volumes / revenue growth and gross margin as reimbursement achieved and new indications come on line Company – Toucan collaboration has been integral to Pelican’s recent stock re-rating; now reaching an Positioning inflection point where it will account for significant component of Pelican’s revenue going forward § Catalyst rich year with potential inflections on the horizon: – Coverage decisions: Lung cancer, I/O therapy – Potential incremental coverage submissions/decisions: CRC, neoadjuvant breast cancer § Morgan Stanley outreach to Pelican – Provided perspectives on the contours of a potential Toucan / Pelican combination without specifics on price or desired structure/consideration mix – Stated Pelican did not wish to provide formal proposal or indication on value given potential need for Pelican public disclosure (13D/A filing due within 2BD of material changes in Pelican’s investment intent) Strategic – Suggested that Pelican come back to Morgan Stanley with feedback Dialogue – No further interactions § Over time, Pelican has continued to engage in ordinary course strategic dialogue – Suggests others may be interested in engaging § Merck and Toucan are entitled to notification in the event an acquisition proposal is submitted or Board solicits third party acquisition interest 2 Source: FactSet as of 1/30/26.
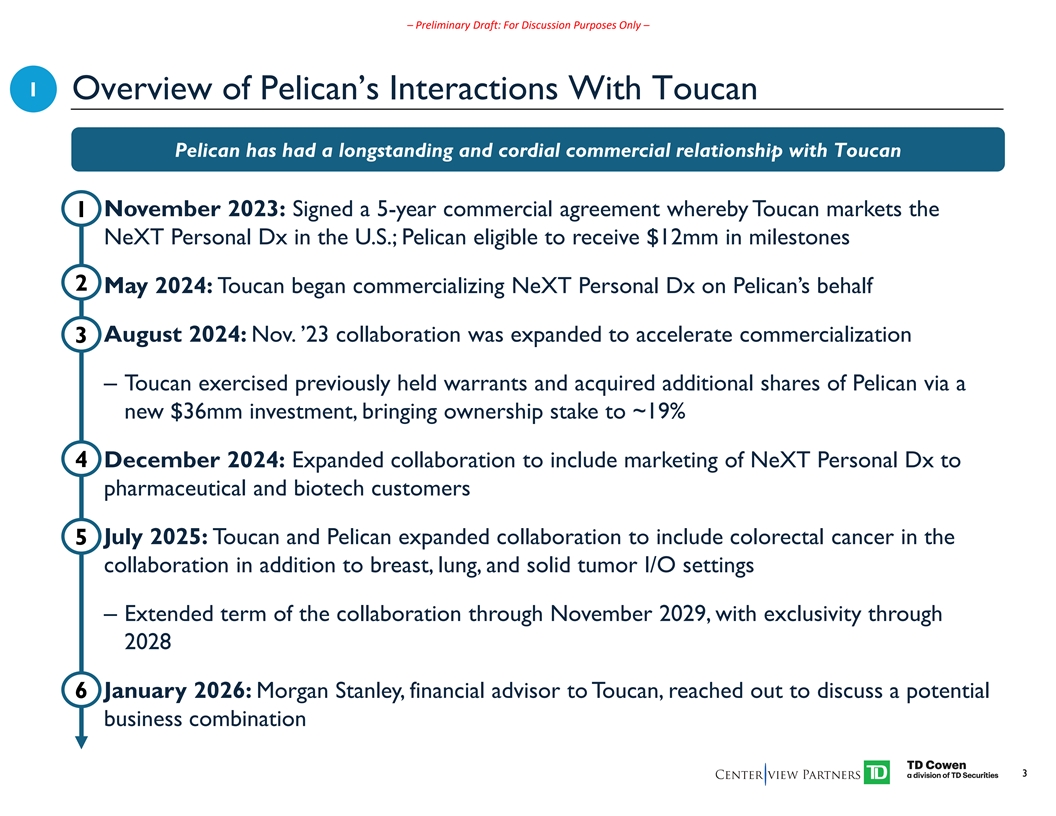
–Preliminary Draft: For Discussion Purposes Only – 1 Overview of Pelican’s Interactions With Toucan Pelican has had a longstanding and cordial commercial relationship with Toucan § November 2023: Signed a 5-year commercial agreement whereby Toucan markets the 1 NeXT Personal Dx in the U.S.; Pelican eligible to receive $12mm in milestones 2 § May 2024: Toucan began commercializing NeXT Personal Dx on Pelican’s behalf 3§ August 2024: Nov. ’23 collaboration was expanded to accelerate commercialization – Toucan exercised previously held warrants and acquired additional shares of Pelican via a new $36mm investment, bringing ownership stake to ~19% 4§ December 2024: Expanded collaboration to include marketing of NeXT Personal Dx to pharmaceutical and biotech customers § July 2025: Toucan and Pelican expanded collaboration to include colorectal cancer in the 5 collaboration in addition to breast, lung, and solid tumor I/O settings – Extended term of the collaboration through November 2029, with exclusivity through 2028 6§ January 2026: Morgan Stanley, financial advisor to Toucan, reached out to discuss a potential business combination 3
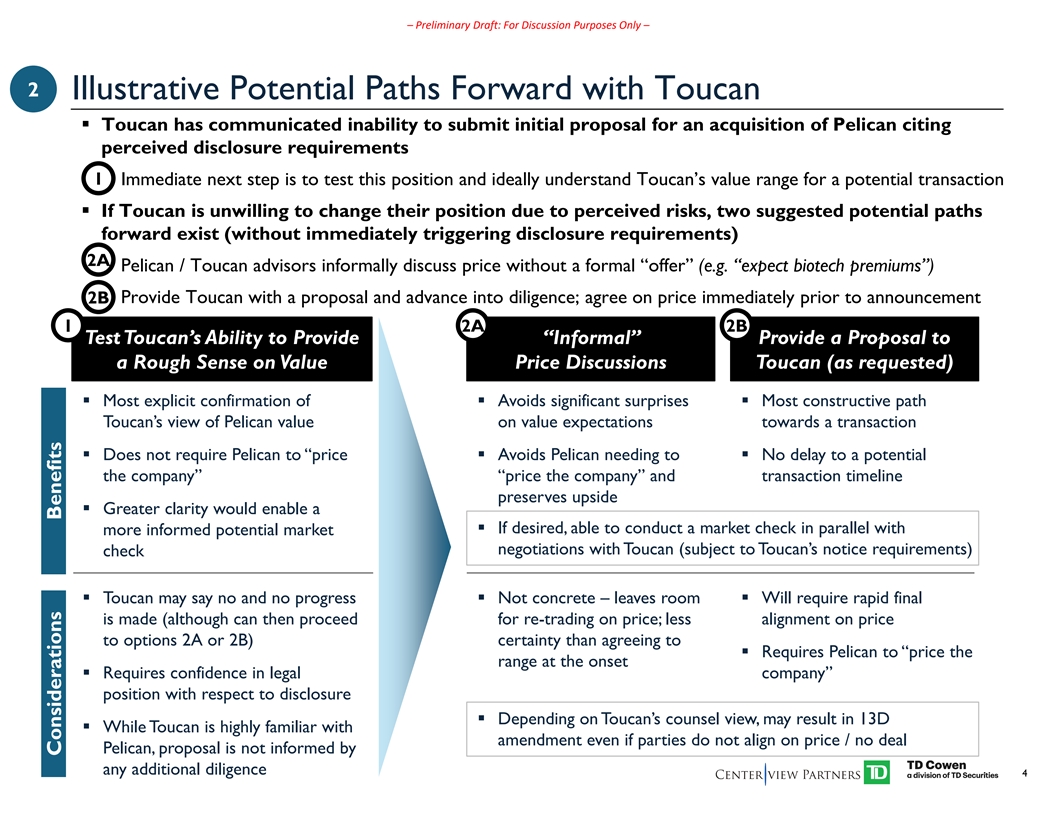
–Preliminary Draft: For Discussion Purposes Only – 2 Illustrative Potential Paths Forward with Toucan § Toucan has communicated inability to submit initial proposal for an acquisition of Pelican citing perceived disclosure requirements 1– Immediate next step is to test this position and ideally understand Toucan’s value range for a potential transaction § If Toucan is unwilling to change their position due to perceived risks, two suggested potential paths forward exist (without immediately triggering disclosure requirements) 2A – Pelican / Toucan advisors informally discuss price without a formal “offer” (e.g. “expect biotech premiums”) 2B – Provide Toucan with a proposal and advance into diligence; agree on price immediately prior to announcement 1 2A 2B Test Toucan’s Ability to Provide “Informal” Provide a Proposal to a Rough Sense on Value Price Discussions Toucan (as requested) § Most explicit confirmation of § Avoids significant surprises § Most constructive path Toucan’s view of Pelican value on value expectations towards a transaction § Does not require Pelican to “price § Avoids Pelican needing to § No delay to a potential the company” “price the company” and transaction timeline preserves upside § Greater clarity would enable a § If desired, able to conduct a market check in parallel with more informed potential market negotiations with Toucan (subject to Toucan’s notice requirements) check § Toucan may say no and no progress § Not concrete – leaves room § Will require rapid final is made (although can then proceed for re-trading on price; less alignment on price to options 2A or 2B) certainty than agreeing to § Requires Pelican to “price the range at the onset § Requires confidence in legal company” position with respect to disclosure § Depending on Toucan’s counsel view, may result in 13D § While Toucan is highly familiar with amendment even if parties do not align on price / no deal Pelican, proposal is not informed by any additional diligence 4 Considerations Benefits
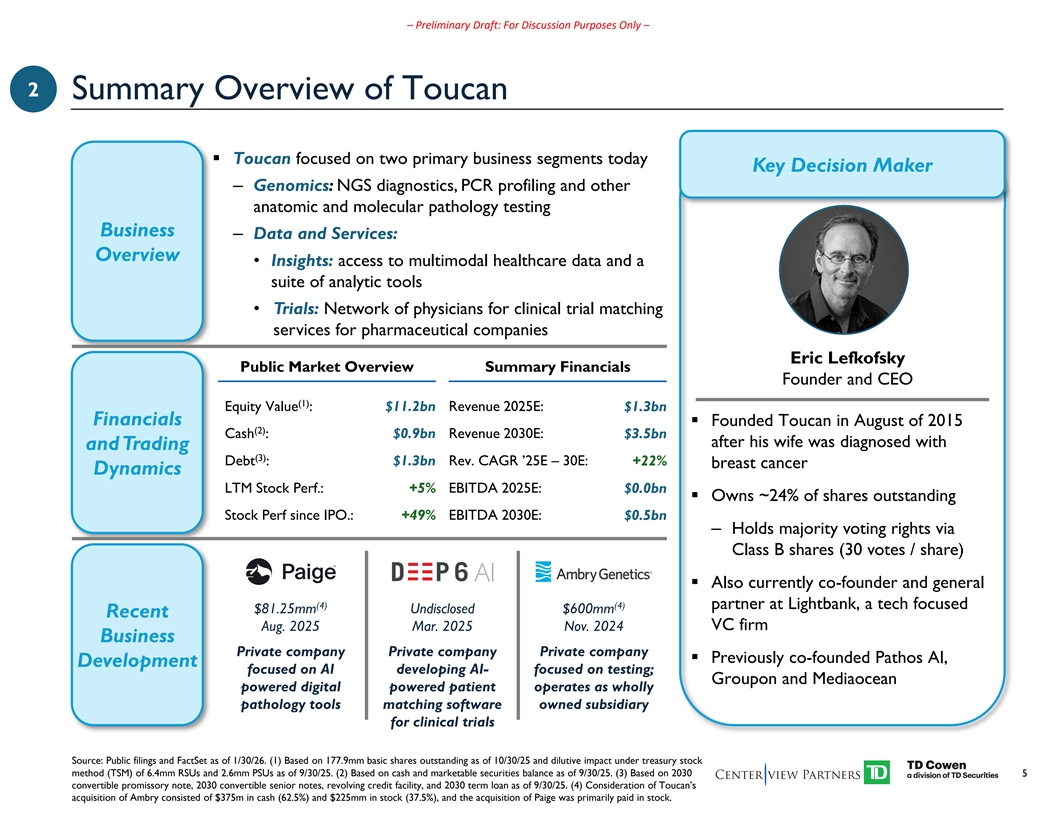
–Preliminary Draft: For Discussion Purposes Only – 2 Summary Overview of Toucan § Toucan focused on two primary business segments today Key Decision Maker – Genomics: NGS diagnostics, PCR profiling and other anatomic and molecular pathology testing Business – Data and Services: Overview • Insights: access to multimodal healthcare data and a suite of analytic tools • Trials: Network of physicians for clinical trial matching services for pharmaceutical companies Eric Lefkofsky Public Market Overview Summary Financials Founder and CEO (1) Equity Value : $11.2bn Revenue 2025E: $1.3bn Financials § Founded Toucan in August of 2015 (2) Cash : $0.9bn Revenue 2030E: $3.5bn after his wife was diagnosed with and Trading (3) Debt : $1.3bn Rev. CAGR ’25E – 30E: +22% breast cancer Dynamics LTM Stock Perf.: +5% EBITDA 2025E: $0.0bn § Owns ~24% of shares outstanding Stock Perf since IPO.: +49% EBITDA 2030E: $0.5bn – Holds majority voting rights via Class B shares (30 votes / share) § Also currently co-founder and general (4) (4) partner at Lightbank, a tech focused $81.25mm Undisclosed $600mm Recent Aug. 2025 Mar. 2025 Nov. 2024 VC firm Business Private company Private company Private company § Previously co-founded Pathos AI, Development focused on AI developing AI- focused on testing; Groupon and Mediaocean powered digital powered patient operates as wholly pathology tools matching software owned subsidiary for clinical trials Source: Public filings and FactSet as of 1/30/26. (1) Based on 177.9mm basic shares outstanding as of 10/30/25 and dilutive impact under treasury stock method (TSM) of 6.4mm RSUs and 2.6mm PSUs as of 9/30/25. (2) Based on cash and marketable securities balance as of 9/30/25. (3) Based on 2030 5 convertible promissory note, 2030 convertible senior notes, revolving credit facility, and 2030 term loan as of 9/30/25. (4) Consideration of Toucan’s acquisition of Ambry consisted of $375m in cash (62.5%) and $225mm in stock (37.5%), and the acquisition of Paige was primarily paid in stock.
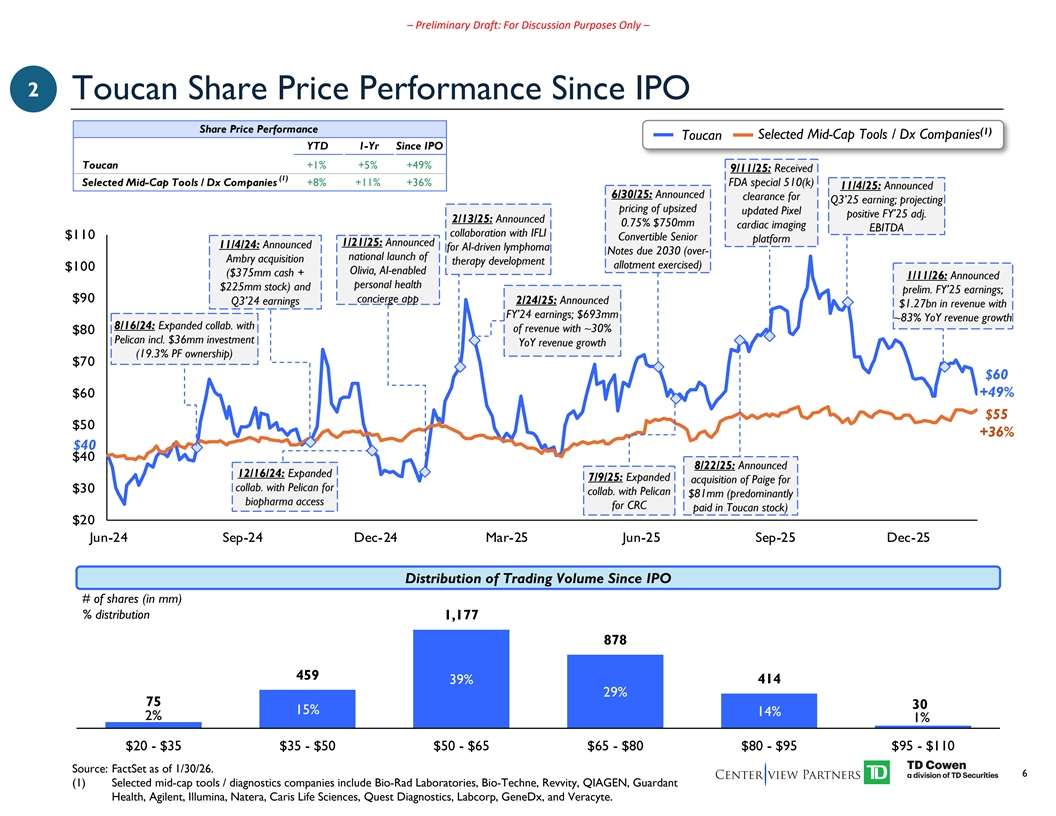
–Preliminary Draft: For Discussion Purposes Only – 2 Toucan Share Price Performance Since IPO Share Price Performance (1) Selected Mid-Cap Tools / Dx Companies Toucan YTD 1-Yr Since IPO Toucan +1% +5% +49% 9/11/25: Received (1) Selected Mid-Cap Tools / Dx Companies +8% +11% +36% FDA special 510(k) 11/4/25: Announced 6/30/25: Announced clearance for Q3’25 earning; projecting pricing of upsized updated Pixel positive FY’25 adj. 2/13/25: Announced 0.75% $750mm cardiac imaging EBITDA collaboration with IFLI $110 Convertible Senior platform 1/21/25: Announced 11/4/24: Announced for AI-driven lymphoma Notes due 2030 (over- national launch of Ambry acquisition therapy development allotment exercised) $100 Olivia, AI-enabled ($375mm cash + 1/11/26: Announced personal health $225mm stock) and prelim. FY’25 earnings; $90 concierge app 2/24/25: Announced Q3’24 earnings $1.27bn in revenue with FY’24 earnings; $693mm ~83% YoY revenue growth 8/16/24: Expanded collab. with of revenue with ~30% $80 Pelican incl. $36mm investment YoY revenue growth (19.3% PF ownership) $70 $60 $60 +49% $55 $50 +36% $40 $40 8/22/25: Announced 12/16/24: Expanded 7/9/25: Expanded acquisition of Paige for collab. with Pelican for $30 collab. with Pelican $81mm (predominantly biopharma access for CRC paid in Toucan stock) $20 Jun-24 Sep-24 Dec-24 Mar-25 Jun-25 Sep-25 Dec-25 Distribution of Trading Volume Since IPO # of shares (in mm) % distribution 1,177 878 459 39% 414 29% 75 30 15% 14% 2% 1% $20 - $35 $35 - $50 $50 - $65 $65 - $80 $80 - $95 $95 - $110 Source: FactSet as of 1/30/26. 6 (1) Selected mid-cap tools / diagnostics companies include Bio-Rad Laboratories, Bio-Techne, Revvity, QIAGEN, Guardant Health, Agilent, Illumina, Natera, Caris Life Sciences, Quest Diagnostics, Labcorp, GeneDx, and Veracyte.
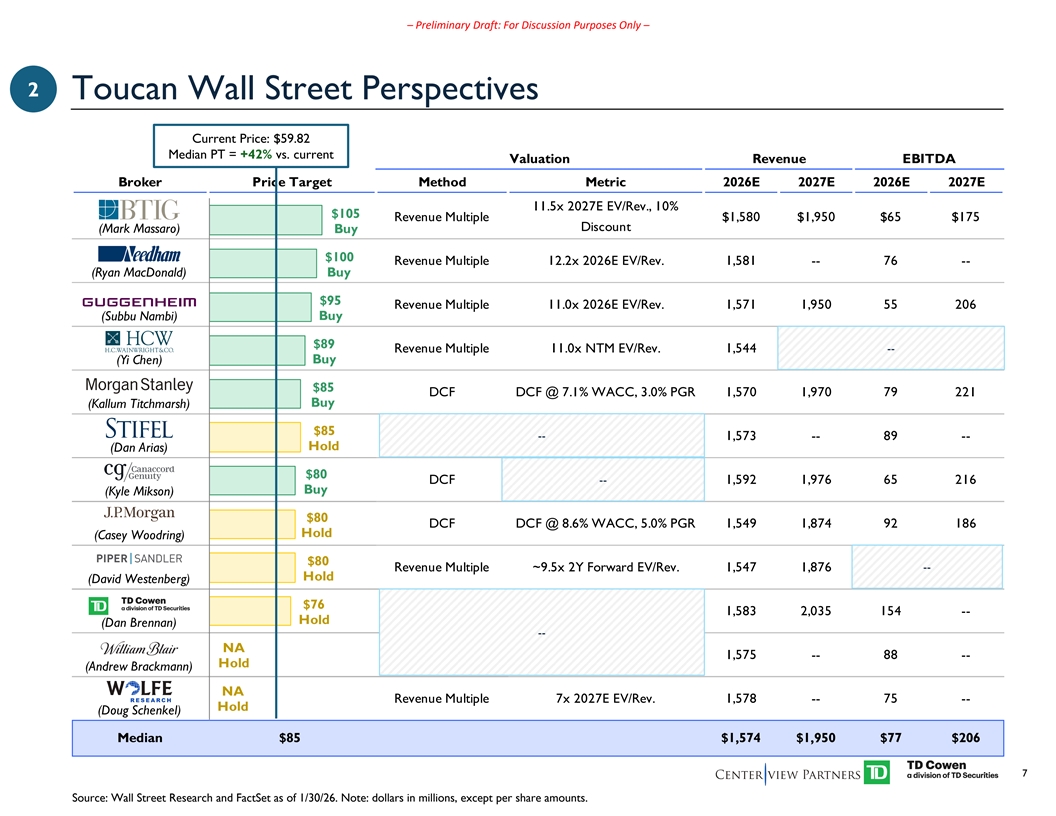
–Preliminary Draft: For Discussion Purposes Only – 2 Toucan Wall Street Perspectives Current Price: $59.82 Median PT = +42% vs. current Valuation Revenue EBITDA Broker Price Target Method Metric 2026E 2027E 2026E 2027E 11.5x 2027E EV/Rev., 10% $105 Revenue Multiple $1,580 $1,950 $65 $175 Discount (Mark Massaro) Buy $100 Revenue Multiple 12.2x 2026E EV/Rev. 1,581 -- 76 -- (Ryan MacDonald) Buy $95 Revenue Multiple 11.0x 2026E EV/Rev. 1,571 1,950 55 206 (Subbu Nambi) Buy $89 -- Revenue Multiple 11.0x NTM EV/Rev. 1,544 -- -- -- (Yi Chen) Buy $85 DCF DCF @ 7.1% WACC, 3.0% PGR 1,570 1,970 79 221 Buy (Kallum Titchmarsh) $85 -- 1,573 -- 89 -- Hold (Dan Arias) $80 DCF -- 1,592 1,976 65 216 Buy (Kyle Mikson) $80 DCF DCF @ 8.6% WACC, 5.0% PGR 1,549 1,874 92 186 Hold (Casey Woodring) $80 -- Revenue Multiple ~9.5x 2Y Forward EV/Rev. 1,547 1,876 -- -- Hold (David Westenberg) $76 1,583 2,035 154 -- Hold (Dan Brennan) -- NA 1,575 -- 88 -- Hold (Andrew Brackmann) NA Revenue Multiple 7x 2027E EV/Rev. 1,578 -- 75 -- Hold (Doug Schenkel) Median $85 $1,574 $1,950 $77 $206 7 Source: Wall Street Research and FactSet as of 1/30/26. Note: dollars in millions, except per share amounts.
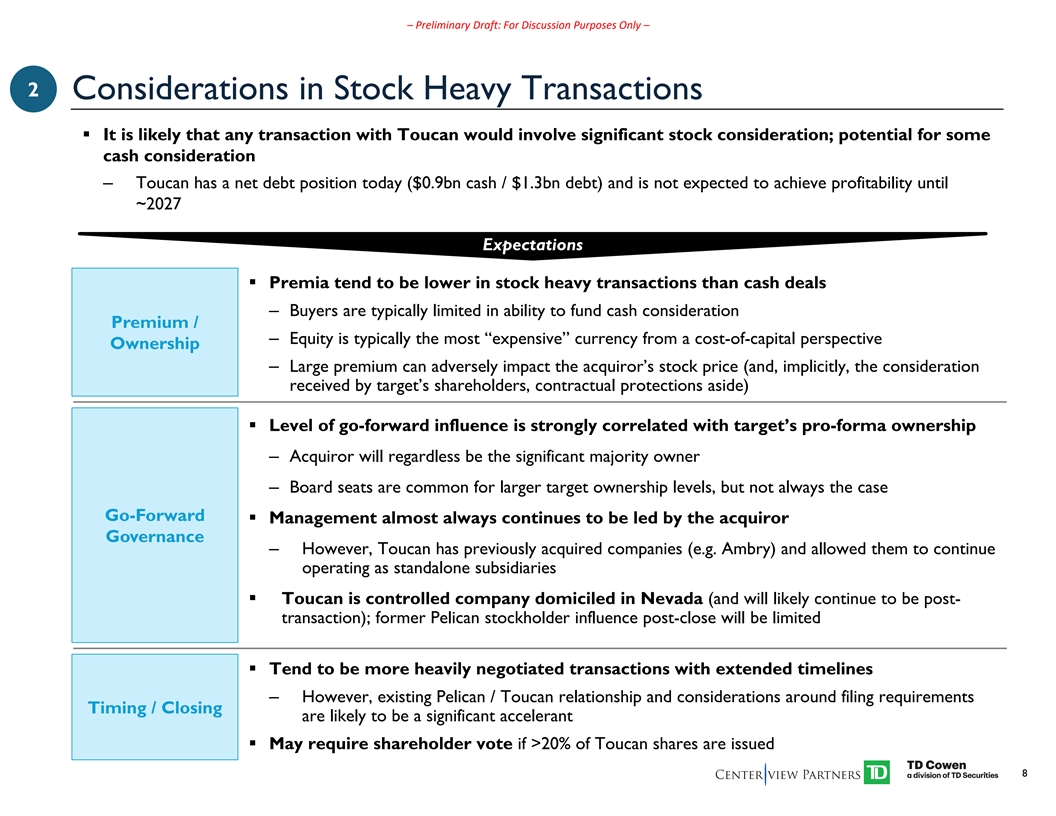
–Preliminary Draft: For Discussion Purposes Only – 2 Considerations in Stock Heavy Transactions § It is likely that any transaction with Toucan would involve significant stock consideration; potential for some cash consideration – Toucan has a net debt position today ($0.9bn cash / $1.3bn debt) and is not expected to achieve profitability until ~2027 Expectations § Premia tend to be lower in stock heavy transactions than cash deals – Buyers are typically limited in ability to fund cash consideration Premium / – Equity is typically the most “expensive” currency from a cost-of-capital perspective Ownership – Large premium can adversely impact the acquiror’s stock price (and, implicitly, the consideration received by target’s shareholders, contractual protections aside) § Level of go-forward influence is strongly correlated with target’s pro-forma ownership – Acquiror will regardless be the significant majority owner – Board seats are common for larger target ownership levels, but not always the case Go-Forward § Management almost always continues to be led by the acquiror Governance – However, Toucan has previously acquired companies (e.g. Ambry) and allowed them to continue operating as standalone subsidiaries § Toucan is controlled company domiciled in Nevada (and will likely continue to be post- transaction); former Pelican stockholder influence post-close will be limited § Tend to be more heavily negotiated transactions with extended timelines – However, existing Pelican / Toucan relationship and considerations around filing requirements Timing / Closing are likely to be a significant accelerant § May require shareholder vote if >20% of Toucan shares are issued 8
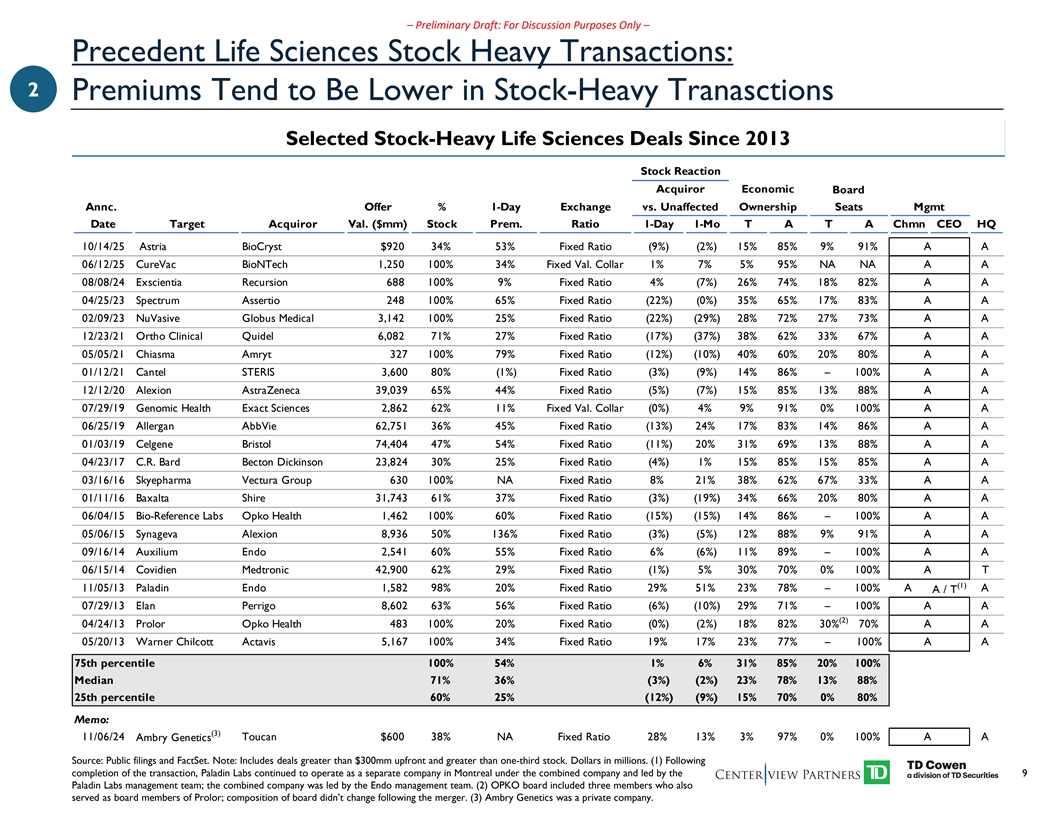
–Preliminary Draft: For Discussion Purposes Only – Precedent Life Sciences Stock Heavy Transactions: 2 Premiums Tend to Be Lower in Stock-Heavy Tranasctions Selected Stock-Heavy Life Sciences Deals Since 2013 Stock Reaction Acquiror Economic Board Annc. Offer%1-DayExchangevs. Unaffected OwnershipSeatsMgmt Date Target Acquiror Val. ($mm) Stock Prem. Ratio 1-Day 1-Mo T A T A Chmn CEO HQ 10/14/25 Astria BioCryst $920 34% 53% Fixed Ratio (9%) (2%) 15% 85% 9% 91% A A 06/12/25 CureVac BioNTech 1,250 100% 34% Fixed Val. Collar 1% 7% 5% 95% NA NA A A 08/08/24 Exscientia Recursion 688 100% 9% Fixed Ratio 4% (7%) 26% 74% 18% 82% A A 04/25/23 Spectrum Assertio 248 100% 65% Fixed Ratio (22%) (0%) 35% 65% 17% 83% A A 02/09/23 NuVasive Globus Medical 3,142 100% 25% Fixed Ratio (22%) (29%) 28% 72% 27% 73% A A 12/23/21 Ortho Clinical Quidel 6,082 71% 27% Fixed Ratio (17%) (37%) 38% 62% 33% 67% A A 05/05/21 Chiasma Amryt 327 100% 79% Fixed Ratio (12%) (10%) 40% 60% 20% 80% A A 01/12/21Cantel STERIS 3,600 80% (1%) Fixed Ratio (3%) (9%) 14% 86% – 100% A A 12/12/20Alexion AstraZeneca 39,039 65% 44% Fixed Ratio (5%) (7%) 15% 85% 13% 88% A A 07/29/19 Genomic Health Exact Sciences 2,862 62% 11% Fixed Val. Collar (0%) 4% 9% 91% 0% 100% A A 06/25/19Allergan AbbVie 62,751 36% 45% Fixed Ratio (13%) 24% 17% 83% 14% 86% A A 01/03/19Celgene Bristol 74,404 47% 54% Fixed Ratio (11%) 20% 31% 69% 13% 88% A A 04/23/17 C.R. Bard Becton Dickinson 23,824 30% 25% Fixed Ratio (4%) 1% 15% 85% 15% 85% A A 03/16/16 Skyepharma Vectura Group 630 100% NA Fixed Ratio 8% 21% 38% 62% 67% 33% A A 01/11/16Baxalta Shire 31,743 61% 37% Fixed Ratio (3%) (19%) 34% 66% 20% 80% A A 06/04/15 Bio-Reference Labs Opko Health 1,462 100% 60% Fixed Ratio (15%) (15%) 14% 86% – 100% A A 05/06/15Synageva Alexion 8,936 50% 136% Fixed Ratio (3%) (5%) 12% 88% 9% 91% A A 09/16/14Auxilium Endo 2,541 60% 55% Fixed Ratio 6% (6%) 11% 89% – 100% A A 06/15/14Covidien Medtronic 42,900 62% 29% Fixed Ratio (1%) 5% 30% 70% 0% 100% A T (1) 11/05/13Paladin Endo 1,582 98% 20% Fixed Ratio 29% 51% 23% 78% – 100% A A A / T 07/29/13Elan Perrigo 8,602 63% 56% Fixed Ratio (6%) (10%) 29% 71% – 100% A A (2) 04/24/13 Prolor Opko Health 483 100% 20% Fixed Ratio (0%) (2%) 18% 82% 30% 70% A A 05/20/13 Warner Chilcott Actavis 5,167 100% 34% Fixed Ratio 19% 17% 23% 77% – 100% A A 75th percentile 100% 54% 1% 6% 31% 85% 20% 100% Median 71% 36% (3%) (2%) 23% 78% 13% 88% 25th percentile 60% 25% (12%) (9%) 15% 70% 0% 80% Memo: (3) 11/06/24 Toucan $600 38% NA Fixed Ratio 28% 13% 3% 97% 0% 100% A A Ambry Genetics Source: Public filings and FactSet. Note: Includes deals greater than $300mm upfront and greater than one-third stock. Dollars in millions. (1) Following completion of the transaction, Paladin Labs continued to operate as a separate company in Montreal under the combined company and led by the 9 Paladin Labs management team; the combined company was led by the Endo management team. (2) OPKO board included three members who also served as board members of Prolor; composition of board didn’t change following the merger. (3) Ambry Genetics was a private company.
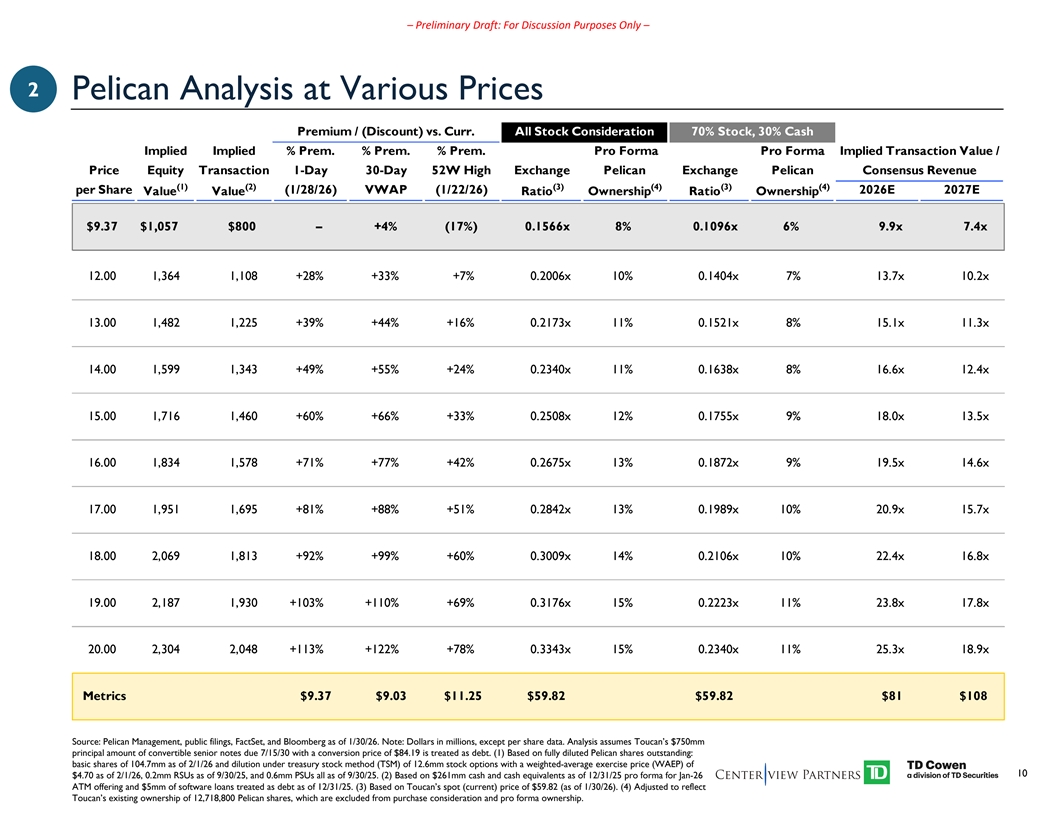
–Preliminary Draft: For Discussion Purposes Only – 2 Pelican Analysis at Various Prices Premium / (Discount) vs. Curr. All Stock Consideration 70% Stock, 30% Cash Implied Implied % Prem. % Prem. % Prem. Pro Forma Pro Forma Implied Transaction Value / Price Equity Transaction 1-Day 30-Day 52W High Exchange Pelican Exchange Pelican Consensus Revenue (1) (2) (3) (4) (3) (4) per Share (1/28/26) VWAP (1/22/26) 2026E 2027E Value Value Ratio Ownership Ratio Ownership $9.37 $1,057 $800 – +4% (17%) 0.1566x 8% 0.1096x 6% 9.9x 7.4x 12.00 1,364 1,108 +28% +33% +7% 0.2006x 10% 0.1404x 7% 13.7x 10.2x 13.00 1,482 1,225 +39% +44% +16% 0.2173x 11% 0.1521x 8% 15.1x 11.3x 14.00 1,599 1,343 +49% +55% +24% 0.2340x 11% 0.1638x 8% 16.6x 12.4x 15.00 1,716 1,460 +60% +66% +33% 0.2508x 12% 0.1755x 9% 18.0x 13.5x 16.00 1,834 1,578 +71% +77% +42% 0.2675x 13% 0.1872x 9% 19.5x 14.6x 17.00 1,951 1,695 +81% +88% +51% 0.2842x 13% 0.1989x 10% 20.9x 15.7x 18.00 2,069 1,813 +92% +99% +60% 0.3009x 14% 0.2106x 10% 22.4x 16.8x 19.00 2,187 1,930 +103% +110% +69% 0.3176x 15% 0.2223x 11% 23.8x 17.8x 20.00 2,304 2,048 +113% +122% +78% 0.3343x 15% 0.2340x 11% 25.3x 18.9x Metrics $9.37 $9.03 $11.25 $59.82 $59.82 $81 $108 Source: Pelican Management, public filings, FactSet, and Bloomberg as of 1/30/26. Note: Dollars in millions, except per share data. Analysis assumes Toucan’s $750mm principal amount of convertible senior notes due 7/15/30 with a conversion price of $84.19 is treated as debt. (1) Based on fully diluted Pelican shares outstanding: basic shares of 104.7mm as of 2/1/26 and dilution under treasury stock method (TSM) of 12.6mm stock options with a weighted-average exercise price (WAEP) of 10 $4.70 as of 2/1/26, 0.2mm RSUs as of 9/30/25, and 0.6mm PSUs all as of 9/30/25. (2) Based on $261mm cash and cash equivalents as of 12/31/25 pro forma for Jan-26 ATM offering and $5mm of software loans treated as debt as of 12/31/25. (3) Based on Toucan’s spot (current) price of $59.82 (as of 1/30/26). (4) Adjusted to reflect Toucan’s existing ownership of 12,718,800 Pelican shares, which are excluded from purchase consideration and pro forma ownership.
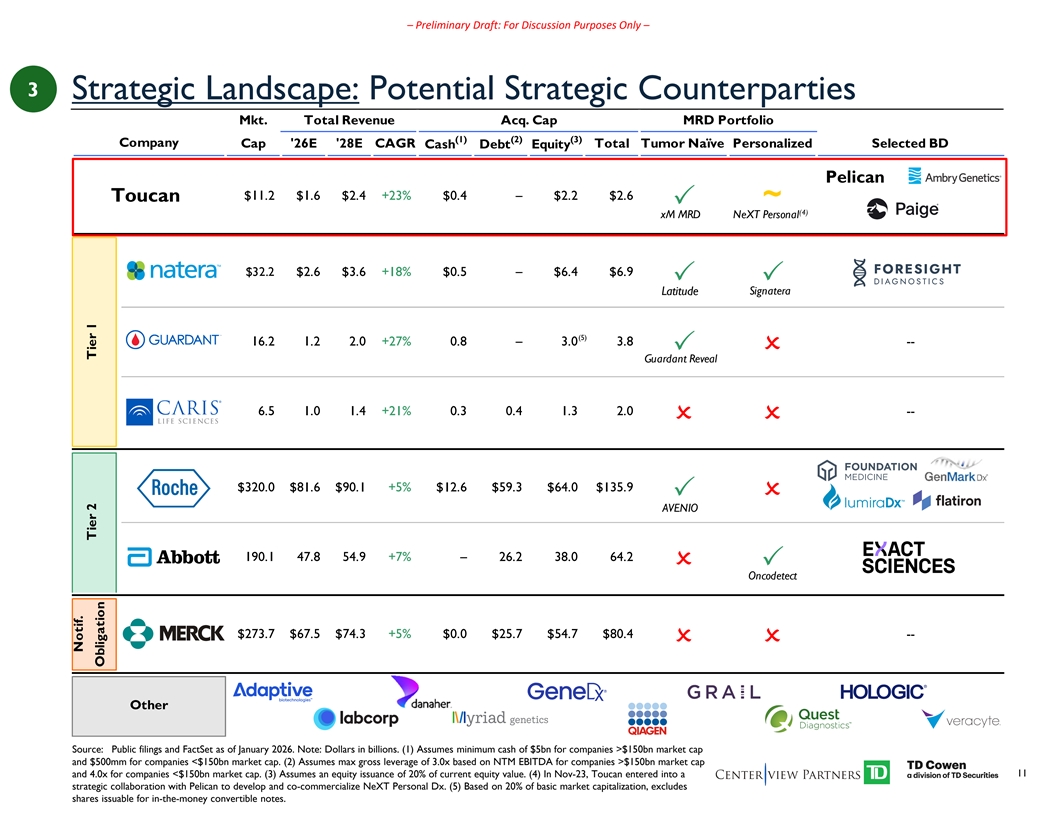
–Preliminary Draft: For Discussion Purposes Only – 3 Strategic Landscape: Potential Strategic Counterparties Mkt. Total Revenue Acq. Cap MRD Portfolio (1) (2) (3) Company Cap '26E '28E CAGR Total Tumor Naïve Personalized Selected BD Cash Debt Equity Pelican $11.2 $1.6 $2.4 +23% $0.4 –$2.2$2.6 Toucan ~ P (4) xM MRD NeXT Personal $32.2 $2.6 $3.6 +18% $0.5 –$6.4$6.9 PP Latitude Signatera (5) 16.2 1.2 2.0 +27% 0.8 – 3.0 3.8 -- PO Guardant Reveal 6.5 1.0 1.4 +21% 0.3 0.4 1.3 2.0 -- OO $320.0 $81.6 $90.1 +5% $12.6 $59.3 $64.0 $135.9 PO AVENIO 190.1 47.8 54.9 +7% – 26.2 38.0 64.2 OP Oncodetect $273.7 $67.5 $74.3 +5% $0.0 $25.7 $54.7 $80.4 -- OO Other Source: Public filings and FactSet as of January 2026. Note: Dollars in billions. (1) Assumes minimum cash of $5bn for companies >$150bn market cap and $500mm for companies <$150bn market cap. (2) Assumes max gross leverage of 3.0x based on NTM EBITDA for companies >$150bn market cap and 4.0x for companies <$150bn market cap. (3) Assumes an equity issuance of 20% of current equity value. (4) In Nov-23, Toucan entered into a 11 strategic collaboration with Pelican to develop and co-commercialize NeXT Personal Dx. (5) Based on 20% of basic market capitalization, excludes shares issuable for in-the-money convertible notes. Notif. Tier 2 Tier 1 Obligation
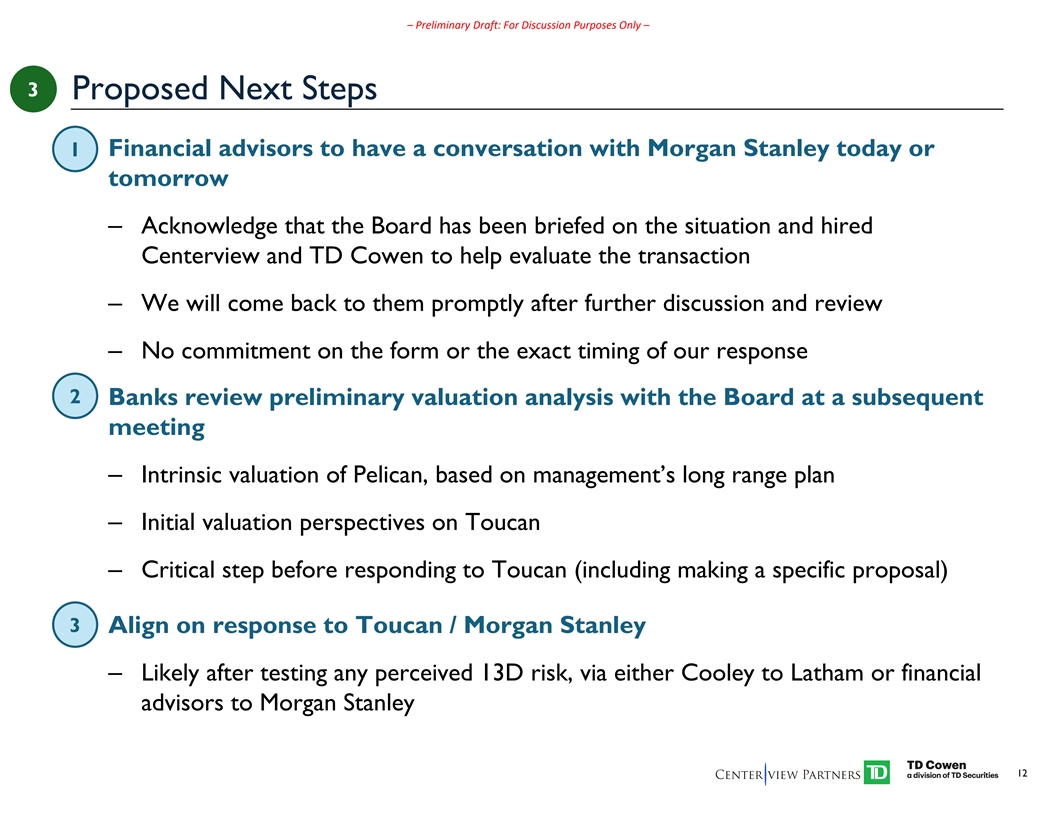
–Preliminary Draft: For Discussion Purposes Only – 3 Proposed Next Steps § Financial advisors to have a conversation with Morgan Stanley today or 1 tomorrow – Acknowledge that the Board has been briefed on the situation and hired Centerview and TD Cowen to help evaluate the transaction – We will come back to them promptly after further discussion and review – No commitment on the form or the exact timing of our response 2 § Banks review preliminary valuation analysis with the Board at a subsequent meeting – Intrinsic valuation of Pelican, based on management’s long range plan – Initial valuation perspectives on Toucan – Critical step before responding to Toucan (including making a specific proposal) 3 § Align on response to Toucan / Morgan Stanley – Likely after testing any perceived 13D risk, via either Cooley to Latham or financial advisors to Morgan Stanley 12
Appendix
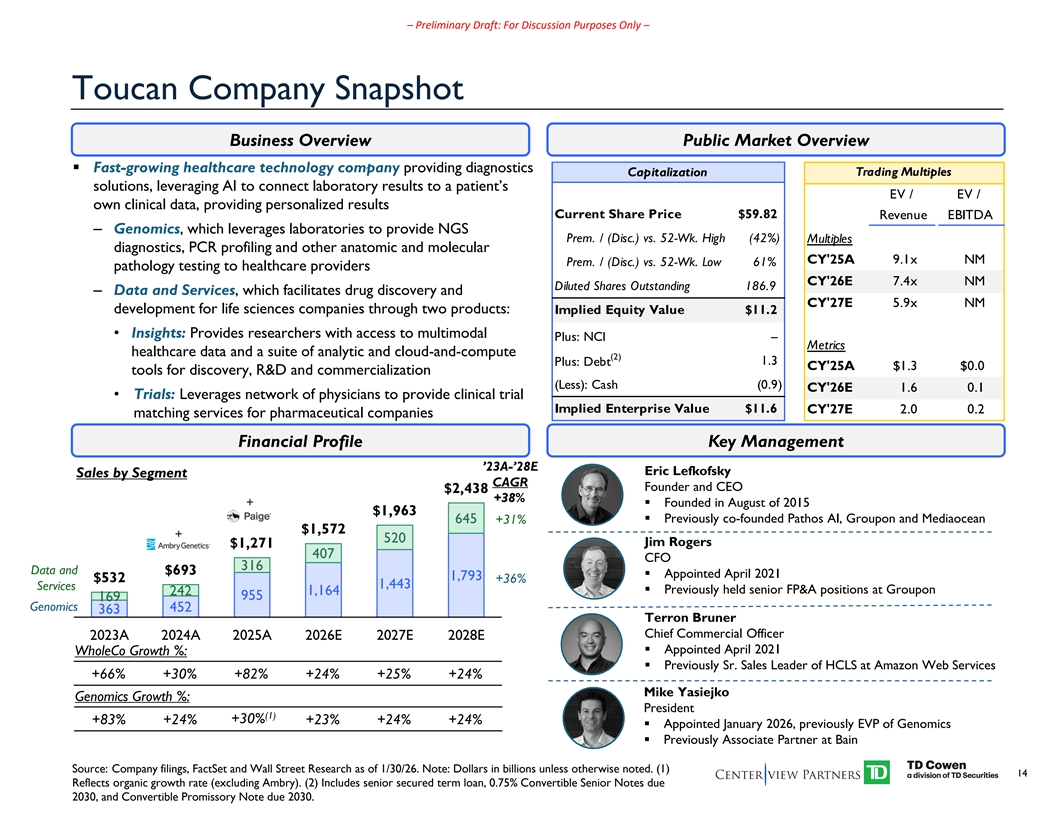
–Preliminary Draft: For Discussion Purposes Only – Toucan Company Snapshot Business Overview Public Market Overview § Fast-growing healthcare technology company providing diagnostics Capitalization Trading Multiples solutions, leveraging AI to connect laboratory results to a patient’s EV / EV / own clinical data, providing personalized results Current Share Price $59.82 Revenue EBITDA – Genomics, which leverages laboratories to provide NGS Prem. / (Disc.) vs. 52-Wk. High (42%) Multiples diagnostics, PCR profiling and other anatomic and molecular CY'25A 9.1x NM Prem. / (Disc.) vs. 52-Wk. Low 61% pathology testing to healthcare providers CY'26E 7.4x NM Diluted Shares Outstanding 186.9 – Data and Services, which facilitates drug discovery and CY'27E 5.9x NM development for life sciences companies through two products: Implied Equity Value $11.2 • Insights: Provides researchers with access to multimodal Plus: NCI – Metrics healthcare data and a suite of analytic and cloud-and-compute (2) 1.3 Plus: Debt CY'25A $1.3 $0.0 tools for discovery, R&D and commercialization (Less): Cash (0.9) CY'26E 1.6 0.1 • Trials: Leverages network of physicians to provide clinical trial Implied Enterprise Value $11.6 CY'27E 2.0 0.2 matching services for pharmaceutical companies Financial Profile Key Management ’23A-’28E Eric Lefkofsky Sales by Segment CAGR Founder and CEO $2,438 +38% +§ Founded in August of 2015 $1,963 § Previously co-founded Pathos AI, Groupon and Mediaocean 645 +31% $1,572 + 520 Jim Rogers $1,271 407 CFO 316 Data and $693 § Appointed April 2021 1,793 $532 +36% 1,443 Services § Previously held senior FP&A positions at Groupon 1,164 242 955 169 Genomics 452 363 Terron Bruner Chief Commercial Officer 2023A 2024A 2025A 2026E 2027E 2028E § Appointed April 2021 WholeCo Growth %: § Previously Sr. Sales Leader of HCLS at Amazon Web Services +66% +30% +82% +24% +25% +24% Mike Yasiejko Genomics Growth %: President (1) +83% +24% +30% +23% +24% +24% § Appointed January 2026, previously EVP of Genomics § Previously Associate Partner at Bain Source: Company filings, FactSet and Wall Street Research as of 1/30/26. Note: Dollars in billions unless otherwise noted. (1) 14 Reflects organic growth rate (excluding Ambry). (2) Includes senior secured term loan, 0.75% Convertible Senior Notes due 2030, and Convertible Promissory Note due 2030.
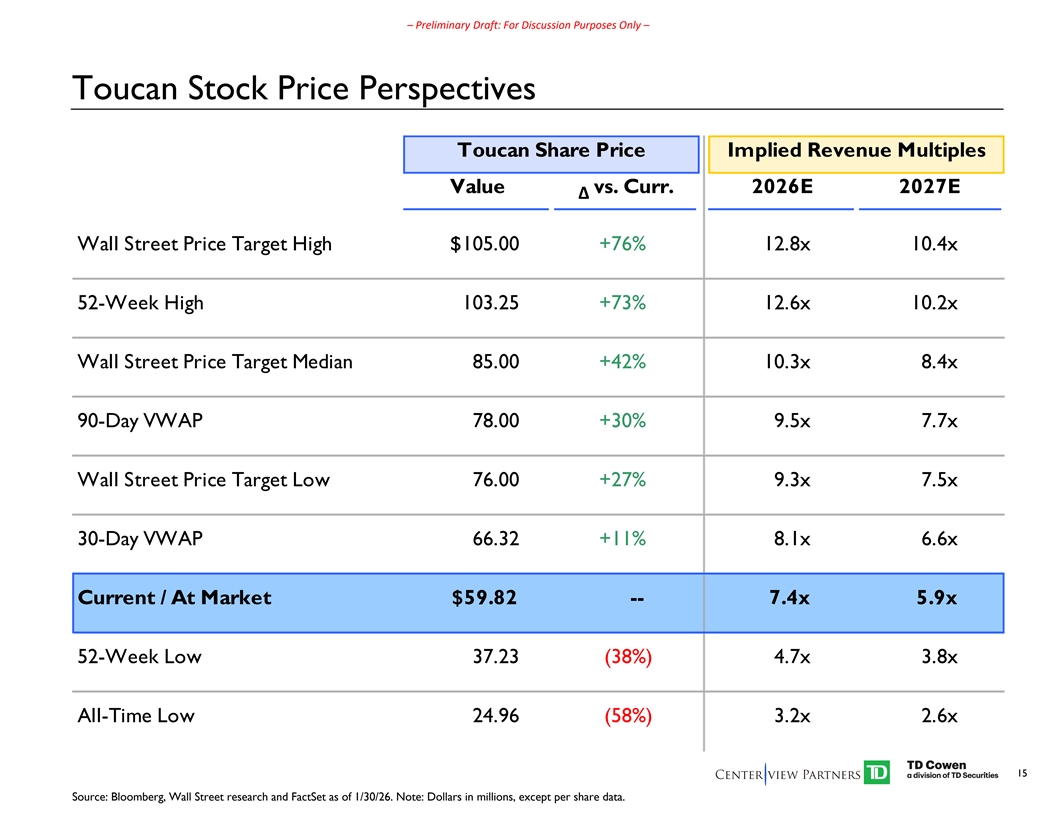
–Preliminary Draft: For Discussion Purposes Only – Toucan Stock Price Perspectives Toucan Share Price Implied Revenue Multiples Value vs. Curr. 2026E 2027E Δ Wall Street Price Target High $105.00 +76% 12.8x 10.4x 52-Week High 103.25 +73% 12.6x 10.2x Wall Street Price Target Median 85.00 +42% 10.3x 8.4x 90-Day VWAP 78.00 +30% 9.5x 7.7x Wall Street Price Target Low 76.00 +27% 9.3x 7.5x 30-Day VWAP 66.32 +11% 8.1x 6.6x Current / At Market $59.82 -- 7.4x 5.9x 52-Week Low 37.23 (38%) 4.7x 3.8x All-Time Low 24.96 (58%) 3.2x 2.6x 15 Source: Bloomberg, Wall Street research and FactSet as of 1/30/26. Note: Dollars in millions, except per share data.
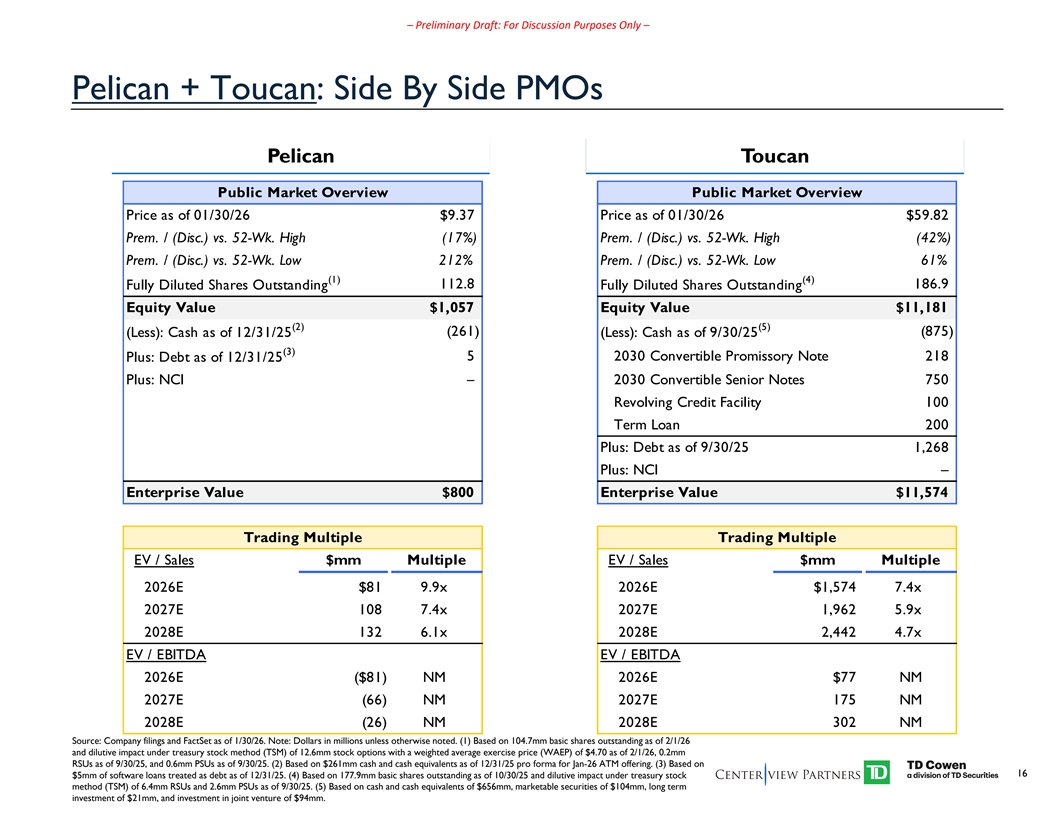
–Preliminary Draft: For Discussion Purposes Only – Pelican + Toucan: Side By Side PMOs Pelican Toucan Public Market Overview Public Market Overview Price as of 01/30/26 $9.37 Price as of 01/30/26 $59.82 Prem. / (Disc.) vs. 52-Wk. High (17%) Prem. / (Disc.) vs. 52-Wk. High (42%) Prem. / (Disc.) vs. 52-Wk. Low 212% Prem. / (Disc.) vs. 52-Wk. Low 61% (1) (4) Fully Diluted Shares Outstanding 112.8 Fully Diluted Shares Outstanding 186.9 Equity Value $1,057 Equity Value $11,181 (2) (5) (261) (875) (Less): Cash as of 12/31/25 (Less): Cash as of 9/30/25 (3) 5 2030 Convertible Promissory Note 218 Plus: Debt as of 12/31/25 Plus: NCI – 2030 Convertible Senior Notes 750 Revolving Credit Facility 100 Term Loan 200 Plus: Debt as of 9/30/25 1,268 Plus: NCI – Enterprise Value $800 Enterprise Value $11,574 Trading Multiple Trading Multiple EV / Sales $mm Multiple EV / Sales $mm Multiple 2026E $81 9.9x 2026E $1,574 7.4x 2027E 108 7.4x 2027E 1,962 5.9x 2028E 132 6.1x 2028E 2,442 4.7x EV / EBITDA EV / EBITDA 2026E ($81) NM 2026E $77 NM 2027E (66) NM 2027E 175 NM 2028E (26) NM 2028E 302 NM Source: Company filings and FactSet as of 1/30/26. Note: Dollars in millions unless otherwise noted. (1) Based on 104.7mm basic shares outstanding as of 2/1/26 and dilutive impact under treasury stock method (TSM) of 12.6mm stock options with a weighted average exercise price (WAEP) of $4.70 as of 2/1/26, 0.2mm RSUs as of 9/30/25, and 0.6mm PSUs as of 9/30/25. (2) Based on $261mm cash and cash equivalents as of 12/31/25 pro forma for Jan-26 ATM offering. (3) Based on 16 $5mm of software loans treated as debt as of 12/31/25. (4) Based on 177.9mm basic shares outstanding as of 10/30/25 and dilutive impact under treasury stock method (TSM) of 6.4mm RSUs and 2.6mm PSUs as of 9/30/25. (5) Based on cash and cash equivalents of $656mm, marketable securities of $104mm, long term investment of $21mm, and investment in joint venture of $94mm.
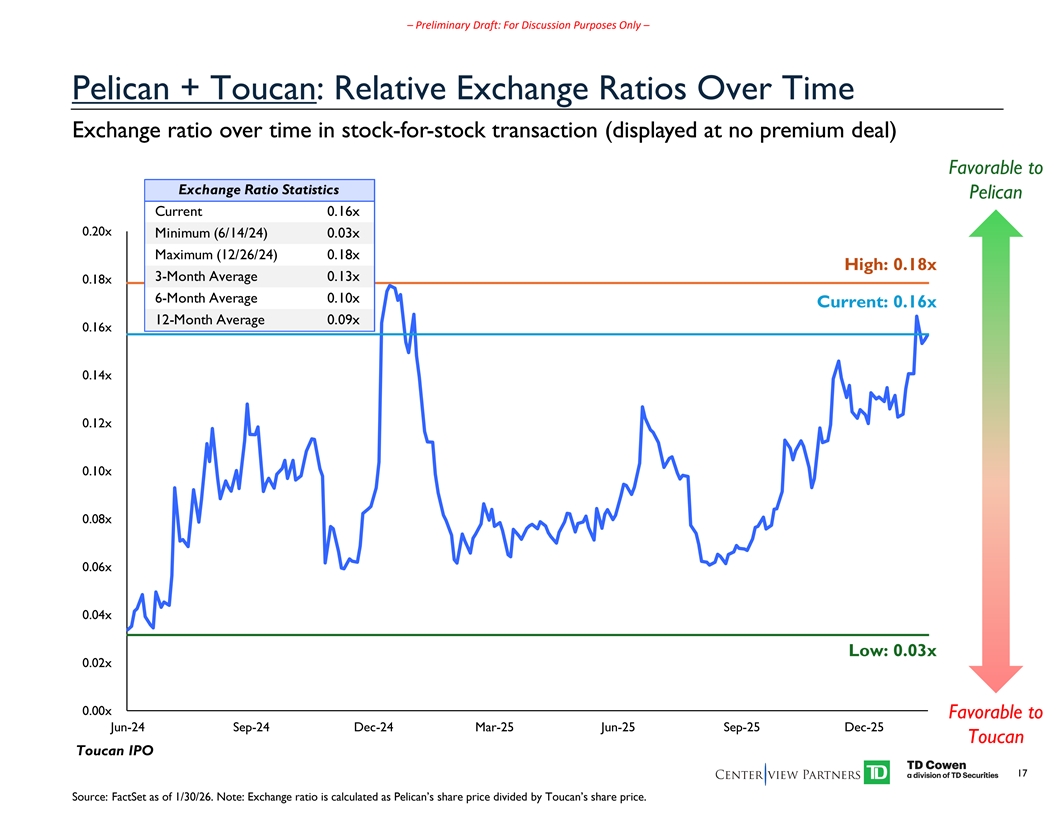
–Preliminary Draft: For Discussion Purposes Only – Pelican + Toucan: Relative Exchange Ratios Over Time Exchange ratio Exchange ratio o ov ver er time in stock-f time in stock-fo or r- -stoc stock transaction k transaction (displa (display yed at no pr ed at no premium deal) emium deal) Favorable to Exchange Ratio Statistics Pelican Current 0.16x 0.20x Minimum (6/14/24) 0.03x Maximum (12/26/24) 0.18x High: 0.18x 3-Month Average 0.13x 0.18x 6-Month Average 0.10x Current: 0.16x 12-Month Average 0.09x 0.16x 0.14x 0.12x 0.10x 0.08x 0.06x 0.04x Low: 0.03x 0.02x 0.00x Favorable to Jun-24 Sep-24 Dec-24 Mar-25 Jun-25 Sep-25 Dec-25 Toucan Toucan IPO 17 Source: FactSet as of 1/30/26. Note: Exchange ratio is calculated as Pelican’s share price divided by Toucan’s share price.
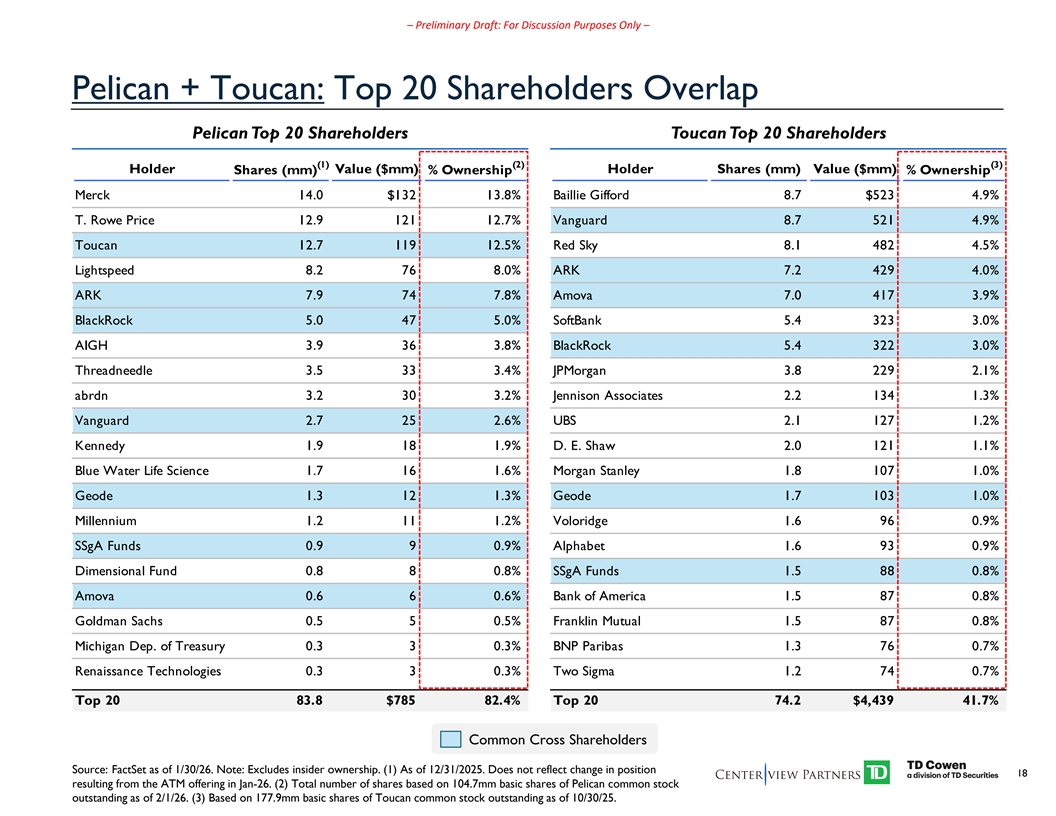
–Preliminary Draft: For Discussion Purposes Only – Pelican + Toucan: Top 20 Shareholders Overlap Pelican Top 20 Shareholders Toucan Top 20 Shareholders (1) (2) (3) Holder Value ($mm) Holder Shares (mm) Value ($mm) Shares (mm) % Ownership % Ownership Merck 14.0 $132 13.8% Baillie Gifford 8.7 $523 4.9% T. Rowe Price 12.9 121 12.7% Vanguard 8.7 521 4.9% Toucan 12.7 119 12.5% Red Sky 8.1 482 4.5% Lightspeed 8.2 76 8.0% ARK 7.2 429 4.0% ARK 7.9 74 7.8% Amova 7.0 417 3.9% BlackRock 5.0 47 5.0% SoftBank 5.4 323 3.0% AIGH 3.9 36 3.8% BlackRock 5.4 322 3.0% Threadneedle 3.5 33 3.4% JPMorgan 3.8 229 2.1% abrdn 3.2 30 3.2% Jennison Associates 2.2 134 1.3% Vanguard 2.7 25 2.6% UBS 2.1 127 1.2% Kennedy 1.9181.9% D. E. Shaw 2.0 121 1.1% Blue Water Life Science 1.7 16 1.6% Morgan Stanley 1.8 107 1.0% Geode 1.3121.3% Geode 1.7 103 1.0% Millennium 1.2 11 1.2% Voloridge 1.6 96 0.9% SSgA Funds 0.9 9 0.9% Alphabet 1.6 93 0.9% Dimensional Fund 0.8 8 0.8% SSgA Funds 1.5 88 0.8% Amova 0.6 6 0.6% Bank of America 1.5 87 0.8% Goldman Sachs 0.5 5 0.5% Franklin Mutual 1.5 87 0.8% Michigan Dep. of Treasury 0.3 3 0.3% BNP Paribas 1.3 76 0.7% Renaissance Technologies 0.3 3 0.3% Two Sigma 1.2 74 0.7% Top 20 83.8 $785 82.4% Top 20 74.2 $4,439 41.7% Common Cross Shareholders Source: FactSet as of 1/30/26. Note: Excludes insider ownership. (1) As of 12/31/2025. Does not reflect change in position 18 resulting from the ATM offering in Jan-26. (2) Total number of shares based on 104.7mm basic shares of Pelican common stock outstanding as of 2/1/26. (3) Based on 177.9mm basic shares of Toucan common stock outstanding as of 10/30/25.
Exhibit (c)(5) Project Aviary Presentation to the Board of Directors February 6, 2026
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Centerview Disclaimer This presentation has been prepared by Centerview Partners LLC (“Centerview”) for use solely by the Board of Directors of Personalis (“Pelican” or the “Company”) in connection with its evaluation of a potential sale of Pelican and for no other purpose. The information contained herein is based upon information supplied by or on behalf of Pelican and publicly available information, and portions of the information contained herein may be based upon statements, estimates and forecasts provided by Pelican. Centerview has relied upon the accuracy and completeness of the foregoing information, and has not assumed any responsibility for any independent verification of such information or for any independent evaluation or appraisal of any of the assets or liabilities (contingent or otherwise) of Pelican or any other entity, or concerning the solvency or fair value of Pelican or any other entity. With respect to financial forecasts, Centerview has assumed that such forecasts have been reasonably prepared on bases reflecting the best currently available estimates and judgments of the management of Pelican as to the future financial performance of Pelican, and at your direction Centerview has relied upon such forecasts, as provided by Pelican management, with respect to Pelican. Centerview assumes no responsibility for and expresses no view as to such forecasts or the assumptions on which they are based. The information set forth herein is based upon economic, monetary, market and other conditions as in effect on, and the information made available to us as of, the date hereof, unless indicated otherwise and Centerview assumes no obligation to update or otherwise revise these materials. The financial analysis in this presentation is complex and is not necessarily susceptible to a partial analysis or summary description. In performing this financial analysis, Centerview has considered the results of its analysis as a whole and did not necessarily attribute a particular weight to any particular portion of the analysis considered. Furthermore, selecting any portion of Centerview’s analysis, without considering the analysis as a whole, would create an incomplete view of the process underlying its financial analysis. Centerview may have deemed various assumptions more or less probable than other assumptions, so the reference ranges resulting from any particular portion of the analysis described above should not be taken to be Centerview’s view of the actual value of Pelican. These materials and the information contained herein are confidential, were not prepared with a view toward public disclosure, and may not be disclosed publicly or made available to third parties without the prior written consent of Centerview. These materials and any other advice, written or oral, rendered by Centerview are intended solely for the benefit and use of the Board of Directors of Pelican (in its capacity as such) in its consideration of the proposed transaction, and are not for the benefit of, and do not convey any rights or remedies for any holder of securities of Pelican or any other person. Centerview will not be responsible for and has not provided any tax, accounting, actuarial, legal or other specialist advice. These materials are not intended to provide the sole basis for evaluating the proposed transaction, and this presentation does not represent a fairness opinion, recommendation, valuation or opinion of any kind, and is necessarily incomplete and should be viewed solely in conjunction with the oral presentation provided by Centerview. 2
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – TD Cowen Disclaimer These materials were prepared exclusively for the benefit and internal use of the TD Securities client (the “Company” or “you”) to whom they are directly addressed and delivered in order to assist the Company in evaluating, on a preliminary basis, the feasibility of a possible transaction or transactions. These materials were compiled or prepared on a confidential basis solely and exclusively for the use of the Company and not with a view to public disclosure or to conform to any disclosure standards under any securities laws or other laws, rules or regulations. The information is for discussion purposes only, and must not be copied or reproduced, or disclosed, , distributed or passed to others at any time without the prior written consent of TD Securities. These materials may not be used for any purpose other than as may be specifically contemplated by a written agreement with TD Securities. These materials and the information contained herein do not purport to be all-inclusive or to contain all of the information, or to identify or suggest all of the risks (direct or indirect), that may be associated with any possible transaction or transactions or that may be necessary to evaluate any possible transaction or transactions. The information in this presentation reflects prevailing conditions and our views as of this date, all of which are accordingly subject to change. TD Securities’ opinions and estimates constitute TD Securities’ judgment and should be regarded as indicative, preliminary and for illustrative purposes only. In preparing the materials, TD Securities has relied upon documents and information prepared for or supplied to TD Securities by the Company and other sources, without independent verification by TD Securities. Any estimates and projections contained herein have been based upon estimates and projections contained in such documents and third-party sources, and there is no assurance that such estimates and projections will be realized. None of TD Securities, its affiliates or its or their respective officers, directors, employees, advisors or representatives (“Representatives”) makes any representation or warranty (express or implied) as to the accuracy or completeness of any information contained herein or any other written or oral communication transmitted or made available to you in connection with an evaluation of a possible transaction, and nothing contained herein or therein is, or shall be construed or relied upon as, a representation or warranty, whether as to the past, present or future. TD Securities does not have any obligation to update or otherwise revise the materials and information contained herein (though all information contained herein is subject to revision). TD Securities believes that these materials must be considered as a whole and that selecting portions of the analyses and the factors considered by TD Securities, without considering all of the factors and analyses together, could create a misleading view of the presentation. The preparation of a presentation such as this is complex and is not necessarily susceptible of partial analysis or summary description. Any attempt to do so could lend to undue emphasis on any particular factor or analysis. Any market valuations contained herein are indicative values as of the time and date indicated for illustrative purposes only. TD Securities does not warrant their completeness or accuracy. Any price or valuation constitutes our judgment and is subject to change without notice. Investors should understand that statements regarding future prospects may not be realized. TD Securities cannot guarantee that different prices and/or valuations would not be available elsewhere and suggests that valuations from other sources be obtained for comparison. Actual quotations could differ subject to market conditions. TD Securities’ policies prohibit employees from offering, directly or indirectly, a favorable research rating or specific price target, or offering to change a rating or price target, to a subject company as consideration or inducement for the receipt of business or for compensation. TD Securities also prohibits its research analysts from being compensated for involvement in investment banking transactions except to the extent that such participation is intended to benefit investors. Nothing herein should be construed as tax, accounting, regulatory or legal advice. TD Securities is not acting in any fiduciary, advisory, agency or similar capacity to the Company. Prior to entering into any possible transaction, you should determine the financial suitability, risks and merits of such transaction, including all economic, legal, tax, accounting or any other consequences associated therewith. Neither TD Securities nor any of its Representatives will be liable to the Company or any third party, whether for negligence, breach of contract or otherwise, for any loss or damage of whatsoever nature suffered by the Company or a third party (including, without limitation, direct loss or damage, indirect or consequential loss or damage, loss of goodwill, loss of business opportunity, loss of data or loss of profit) arising from TD Securities providing you with these materials or the information contained herein or any other written or oral communication transmitted or made available to you in connection with an evaluation of a possible transaction. TD Securities and its affiliates expressly disclaim any and all liability relating to, resulting from or based, in whole or in part, on such information, errors therein or omissions therefrom. These materials do not constitute a commitment, express or implied, by TD Securities or any of its affiliates to enter into any transaction, underwrite, subscribe for, purchase or place any securities or to extend or arrange credit or to otherwise provide any financing or other services. Nothing in these materials should be construed as, and may not be used in connection with, an offer to sell, or a solicitation of an offer to buy or hold, an interest in any security or investment product. Final terms and conditions, if any, and any obligation of TD Securities or any of its affiliates with respect to any possible transaction discussed herein will be subject to (among other things): (i) satisfactory completion, in TD Securities’ sole discretion, of customary business, financial and legal due diligence input and inquiry, (ii) execution of definitive documentation containing terms and conditions customary to TD Securities for similar transactions, (iii) market conditions, (iv) approval by the appropriate TD internal committee and (v) any other conditions that TD Securities may deem appropriate. “TD Securities” is a trademark of The Toronto-Dominion Bank (“TD”) and represents certain investment banking, capital markets and wholesale banking activities conducted through certain subsidiaries and branches of TD. “TD Cowen” is a division of TD Securities and represents a marketing name of certain businesses within TD Securities. TD Securities Inc. is regulated by the Canadian Investment Regulatory Organization of Canada. TD Securities Inc. is a member of the Canadian Investor Protection Fund and a member of Canadian Marketplaces. The following affiliated entities are registered U.S. broker dealers with the U.S Securities and Exchange Commission and are members of the Financial Industry Regulatory Authority and of the Securities Investor Protection Corporation: TD Securities (USA) LLC, TD Prime Services LLC, TD Securities Automated Trading LLC, TD Arranged Services LLC and Westminster Research Associates LLC. TD is registered as a swap dealer with the U.S. Commodity Futures Trading Commission and is a member of the National Futures Association. TD is also registered as a security -based swap dealer with the U.S. Securities and Exchange Commission. Cowen Financial Products LLC is registered as a security-based swap dealer with the U.S. Securities and Exchange Commission. TD, TD Bank Europe Limited and TD Execution Services Limited are regulated for investment business conducted in the UK by the UK Financial Conduct Authority. TD Global Finance unlimited company is regulated for investment business conducted in Ireland by the Central Bank of Ireland. TD and Toronto Dominion (South East Asia) Limited are regulated by the Monetary Authority of Singapore. All logos are property of their respective owners and are for identification purposes only. Use of these names, logos, and brands does not imply endorsement. Copyright © 2025 The Toronto-Dominion Bank and/or its affiliates. All rights reserved. ® The TD logo and other TD trademarks are the property of The Toronto-Dominion Bank or its subsidiaries. 3
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Situation Update and Today’s Objectives ▪ Centerview and TD Cowen authorized to contact Morgan Stanley at 2/2 Board meeting – Conversation on 2/3 relaying that the Board is forming a response and will respond to Toucan’s outreach in due course Updates Since Last Board Meeting ▪ Cooley conducted outreach to and held preliminary discussions with Latham ▪ Pelican Management updated its preliminary long-term forecast and furnished it to Centerview and TD Cowen to provide preliminary valuation perspectives ▪ Review Pelican preliminary valuation perspectives – Focus on preliminary intrinsic valuation and associated sensitivities today Today’s Objectives ▪ Authorize a more formal response to Morgan Stanley ▪ Review preliminary perspectives on Toucan 4
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican Public Market Perspectives 5
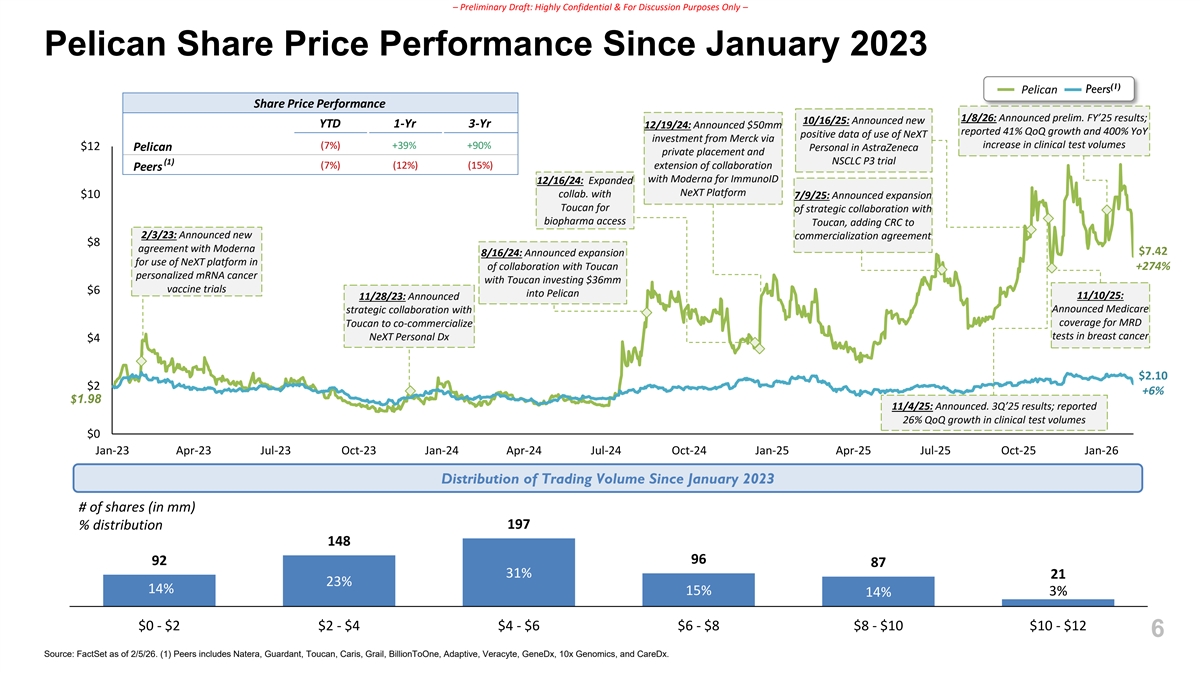
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican Share Price Performance Since January 2023 (1) Pelican Peers Share Price Performance 1/8/26: Announced prelim. FY’25 results; 10/16/25: Announced new YTD 1-Yr 3-Yr 12/19/24: Announced $50mm reported 41% QoQ growth and 400% YoY positive data of use of NeXT investment from Merck via (7%) +39% +90% increase in clinical test volumes $12 Pelican Personal in AstraZeneca private placement and (1) NSCLC P3 trial (7%) (12%) (15%) extension of collaboration Peers with Moderna for ImmunoID 12/16/24: Expanded NeXT Platform collab. with $10 7/9/25: Announced expansion Toucan for of strategic collaboration with biopharma access Toucan, adding CRC to 2/3/23: Announced new commercialization agreement $8 agreement with Moderna $7.42 8/16/24: Announced expansion for use of NeXT platform in of collaboration with Toucan +274% personalized mRNA cancer with Toucan investing $36mm vaccine trials $6 into Pelican 11/10/25: 11/28/23: Announced Announced Medicare strategic collaboration with coverage for MRD Toucan to co-commercialize NeXT Personal Dx tests in breast cancer $4 $2.10 $2 +6% $1.98 11/4/25: Announced. 3Q’25 results; reported 26% QoQ growth in clinical test volumes $0 Jan-23 Apr-23 Jul-23 Oct-23 Jan-24 Apr-24 Jul-24 Oct-24 Jan-25 Apr-25 Jul-25 Oct-25 Jan-26 Distribution of Trading Volume Since January 2023 # of shares (in mm) 197 % distribution 148 96 92 87 31% 21 23% 14% 15% 3% 14% $0 - $2 $2 - $4 $4 - $6 $6 - $8 $8 - $10 $10 - $12 6 Source: FactSet as of 2/5/26. (1) Peers includes Natera, Guardant, Toucan, Caris, Grail, BillionToOne, Adaptive, Veracyte, GeneDx, 10x Genomics, and CareDx.
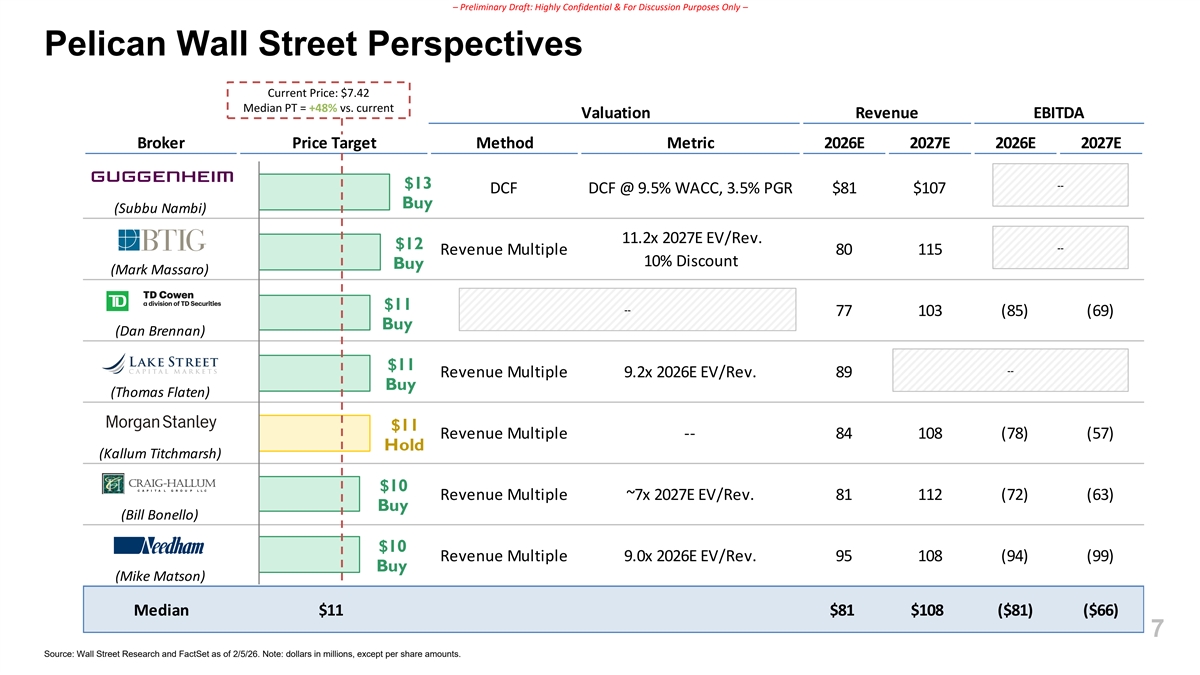
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican Wall Street Perspectives Current Price: $7.42 Median PT = +48% vs. current Valuation Revenue EBITDA Broker Price Target Method Metric 2026E 2027E 2026E 2027E $13 -- DCF DCF @ 9.5% WACC, 3.5% PGR $81 $107 n.a. n.a. Buy (Subbu Nambi) 11.2x 2027E EV/Rev. $12 -- Revenue Multiple 80 115 n.a. n.a. 10% Discount Buy (Mark Massaro) $11 -- -- -- 77 103 (85) (69) Buy (Dan Brennan) $11 -- Revenue Multiple 9.2x 2026E EV/Rev. 89 n.a. n.a. n.a. Buy (Thomas Flaten) $11 Revenue Multiple -- 84 108 (78) (57) Hold (Kallum Titchmarsh) $10 Revenue Multiple ~7x 2027E EV/Rev. 81 112 (72) (63) Buy (Bill Bonello) $10 Revenue Multiple 9.0x 2026E EV/Rev. 95 108 (94) (99) Buy (Mike Matson) Median $11 $81 $108 ($81) ($66) 7 Source: Wall Street Research and FactSet as of 2/5/26. Note: dollars in millions, except per share amounts.
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Pelican Management Financial Projections 8
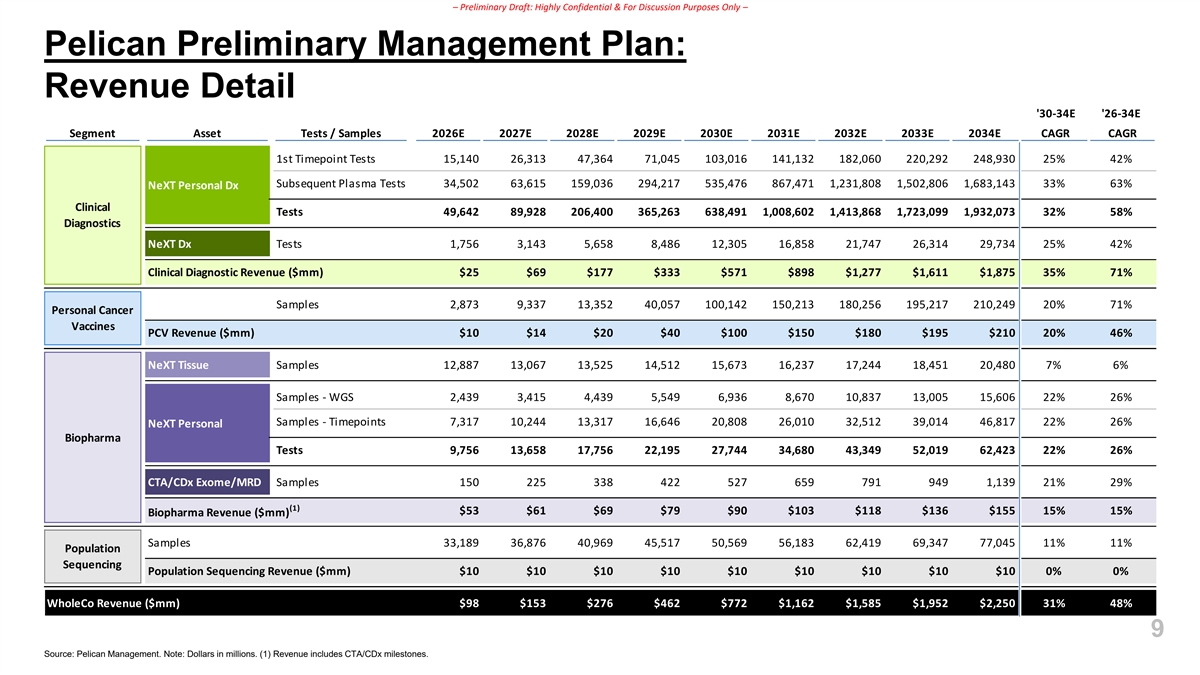
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican Preliminary Management Plan: Revenue Detail '30-34E '26-34E Segment Asset Tests / Samples 2026E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E CAGR CAGR 1st Timepoint Tests 15,140 26,313 47,364 71,045 103,016 141,132 182,060 220,292 248,930 25% 42% Subsequent Plasma Tests 34,502 63,615 159,036 294,217 535,476 867,471 1,231,808 1,502,806 1,683,143 33% 63% NeXT Personal Dx Clinical Tests 49,642 89,928 206,400 365,263 638,491 1,008,602 1,413,868 1,723,099 1,932,073 32% 58% Diagnostics NeXT Dx Tests 1,756 3,143 5,658 8,486 12,305 16,858 21,747 26,314 29,734 25% 42% Clinical Diagnostic Revenue ($mm) $25 $69 $177 $333 $571 $898 $1,277 $1,611 $1,875 35% 71% Samples 2,873 9,337 13,352 40,057 100,142 150,213 180,256 195,217 210,249 20% 71% Personal Cancer Vaccines PCV Revenue ($mm) $10 $14 $20 $40 $100 $150 $180 $195 $210 20% 46% NeXT Tissue Samples 12,887 13,067 13,525 14,512 15,673 16,237 17,244 18,451 20,480 7% 6% Samples - WGS 2,439 3,415 4,439 5,549 6,936 8,670 10,837 13,005 15,606 22% 26% Samples - Timepoints 7,317 10,244 13,317 16,646 20,808 26,010 32,512 39,014 46,817 22% 26% NeXT Personal Biopharma Tests 9,756 13,658 17,756 22,195 27,744 34,680 43,349 52,019 62,423 22% 26% CTA/CDx Exome/MRD Samples 150 225 338 422 527 659 791 949 1,139 21% 29% (1) $53 $61 $69 $79 $90 $103 $118 $136 $155 15% 15% Biopharma Revenue ($mm) Samples 33,189 36,876 40,969 45,517 50,569 56,183 62,419 69,347 77,045 11% 11% Population Sequencing Population Sequencing Revenue ($mm) $10 $10 $10 $10 $10 $10 $10 $10 $10 0% 0% WholeCo Revenue ($mm) $98 $153 $276 $462 $772 $1,162 $1,585 $1,952 $2,250 31% 48% 9 Source: Pelican Management. Note: Dollars in millions. (1) Revenue includes CTA/CDx milestones.
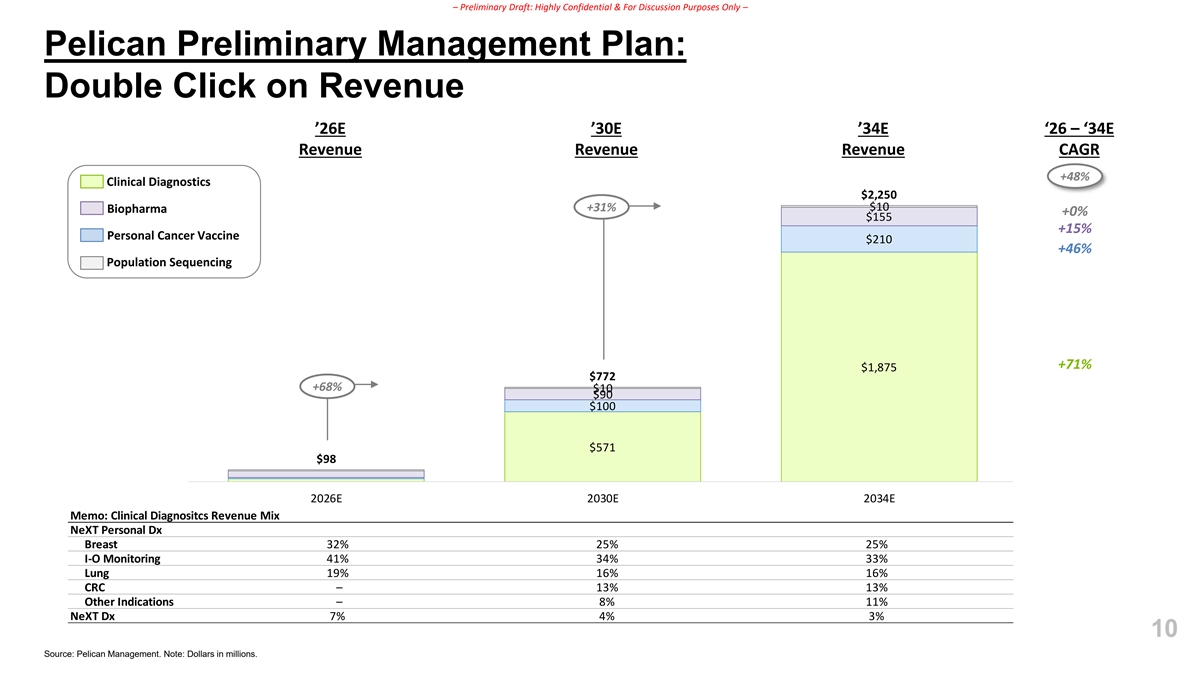
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican Preliminary Management Plan: Double Click on Revenue ’26E ’30E ’34E ‘26 – ‘34E Revenue Revenue Revenue CAGR +48% Clinical Diagnostics $2,250 +31% $10 Biopharma +0% $155 +15% Personal Cancer Vaccine $210 +46% Population Sequencing +71% $1,875 $772 +68% $10 $90 $100 $571 $98 2026E 2030E 2034E Memo: Clinical Diagnositcs Revenue Mix NeXT Personal Dx Breast 32% 25% 25% I-O Monitoring 41% 34% 33% Lung 19% 16% 16% CRC – 13% 13% Other Indications – 8% 11% NeXT Dx 7% 4% 3% 10 Source: Pelican Management. Note: Dollars in millions.
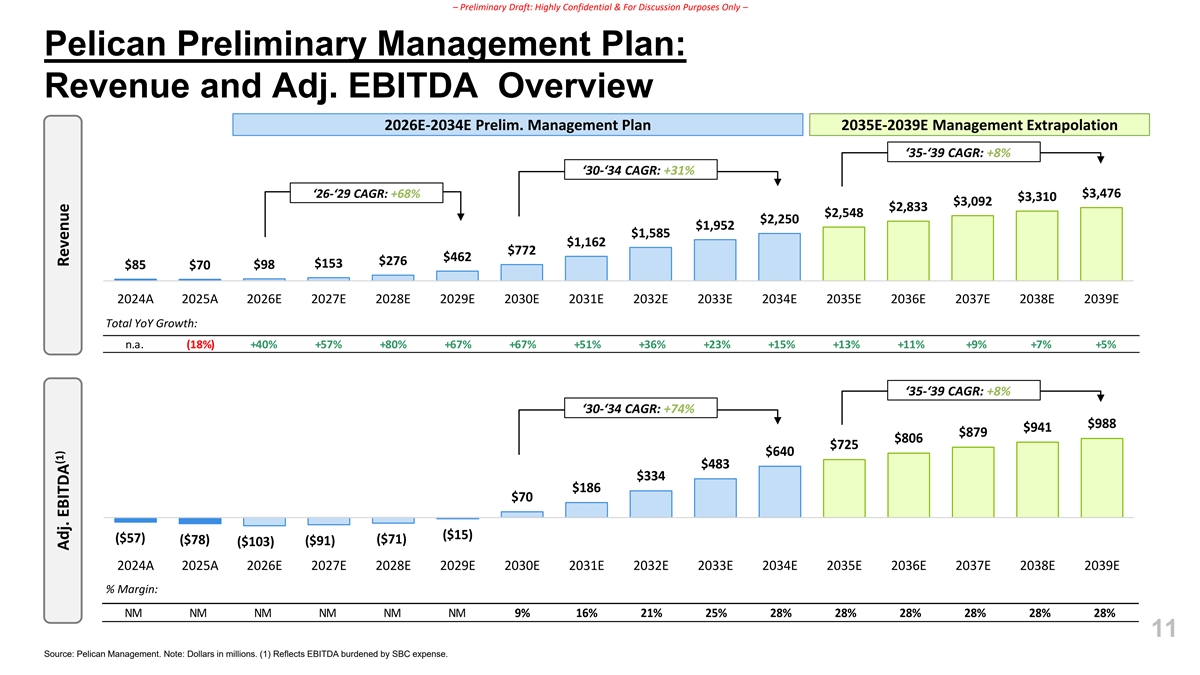
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican Preliminary Management Plan: Revenue and Adj. EBITDA Overview 2026E-2034E Prelim. Management Plan 2035E-2039E Management Extrapolation ‘35-‘39 CAGR: +8% ‘30-‘34 CAGR: +31% ‘26-‘29 CAGR: +68% $3,476 $3,310 $3,092 $2,833 $2,548 $2,250 $1,952 $1,585 $1,162 $772 $462 $276 $153 $85 $98 $70 2024A 2025A 2026E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E 2036E 2037E 2038E 2039E Total YoY Growth: n.a. (18%) +40% +57% +80% +67% +67% +51% +36% +23% +15% +13% +11% +9% +7% +5% ‘35-‘39 CAGR: +8% ‘30-‘34 CAGR: +74% $988 $941 $879 $806 $725 $640 $483 $334 $186 $70 ($15) ($57) ($71) ($78) ($91) ($103) 2024A 2025A 2026E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E 2036E 2037E 2038E 2039E % Margin: NM NM NM NM NM NM 9% 16% 21% 25% 28% 28% 28% 28% 28% 28% 11 Source: Pelican Management. Note: Dollars in millions. (1) Reflects EBITDA burdened by SBC expense. (1) Adj. EBITDA Revenue
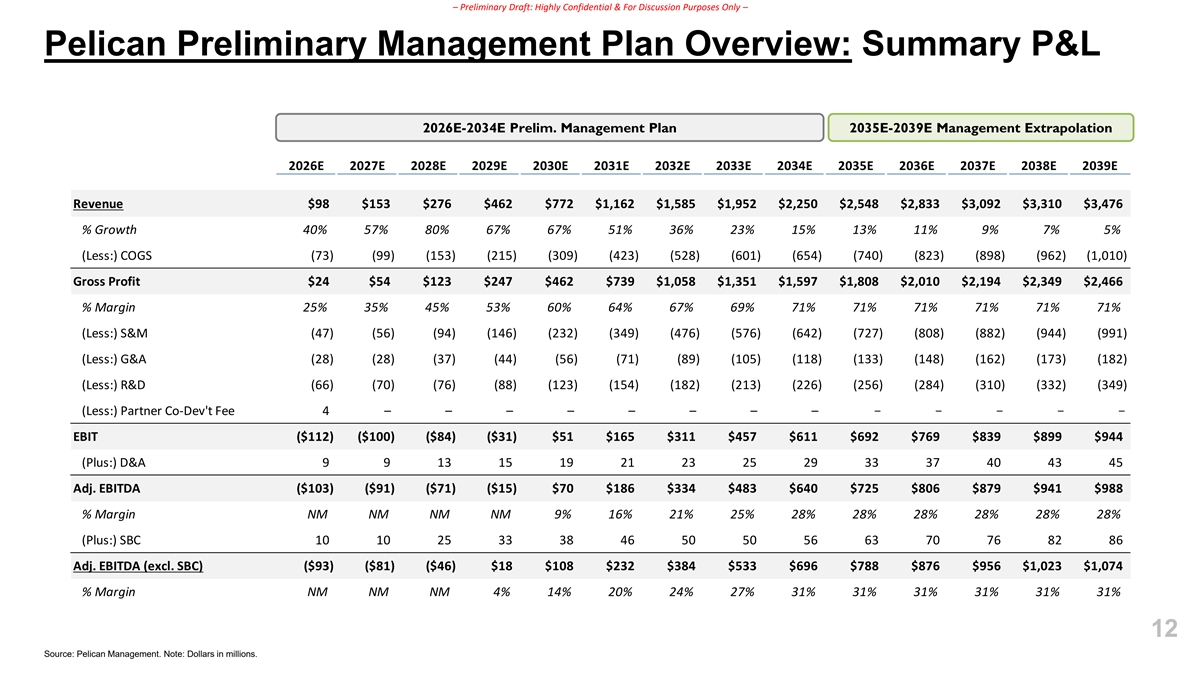
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican Preliminary Management Plan Overview: Summary P&L 2026E-2034E Prelim. Management Plan 2035E-2039E Management Extrapolation 2026E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E 2036E 2037E 2038E 2039E Revenue $98 $153 $276 $462 $772 $1,162 $1,585 $1,952 $2,250 $2,548 $2,833 $3,092 $3,310 $3,476 % Growth 40% 57% 80% 67% 67% 51% 36% 23% 15% 13% 11% 9% 7% 5% (Less:) COGS (73) (99) (153) (215) (309) (423) (528) (601) (654) (740) (823) (898) (962) (1,010) Gross Profit $24 $54 $123 $247 $462 $739 $1,058 $1,351 $1,597 $1,808 $2,010 $2,194 $2,349 $2,466 % Margin 25% 35% 45% 53% 60% 64% 67% 69% 71% 71% 71% 71% 71% 71% (Less:) S&M (47) (56) (94) (146) (232) (349) (476) (576) (642) (727) (808) (882) (944) (991) (Less:) G&A (28) (28) (37) (44) (56) (71) (89) (105) (118) (133) (148) (162) (173) (182) (Less:) R&D (66) (70) (76) (88) (123) (154) (182) (213) (226) (256) (284) (310) (332) (349) (Less:) Partner Co-Dev't Fee 4 – – – – – – – – – – – – – EBIT ($112) ($100) ($84) ($31) $51 $165 $311 $457 $611 $692 $769 $839 $899 $944 (Plus:) D&A 9 9 13 15 19 21 23 25 29 33 37 40 43 45 Adj. EBITDA ($103) ($91) ($71) ($15) $70 $186 $334 $483 $640 $725 $806 $879 $941 $988 % Margin NM NM NM NM 9% 16% 21% 25% 28% 28% 28% 28% 28% 28% (Plus:) SBC 10 10 25 33 38 46 50 50 56 63 70 76 82 86 Adj. EBITDA (excl. SBC) ($93) ($81) ($46) $18 $108 $232 $384 $533 $696 $788 $876 $956 $1,023 $1,074 % Margin NM NM NM 4% 14% 20% 24% 27% 31% 31% 31% 31% 31% 31% 12 Source: Pelican Management. Note: Dollars in millions.
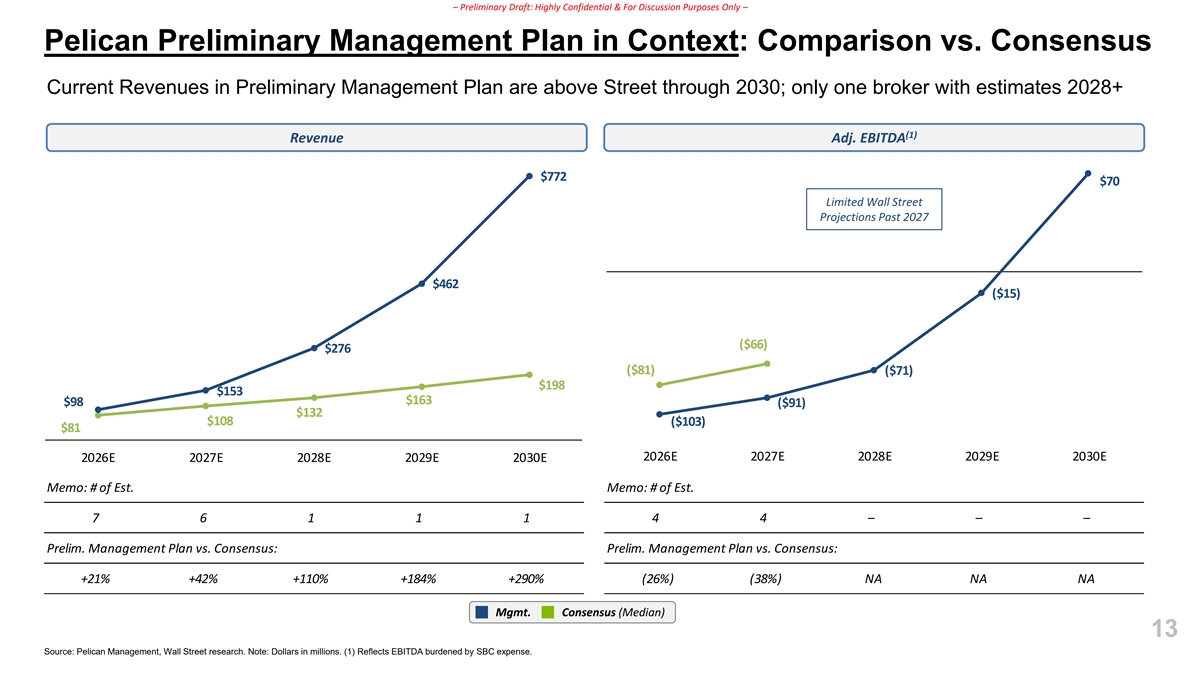
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican Preliminary Management Plan in Context: Comparison vs. Consensus Current Revenues in Preliminary Management Plan are above Street through 2030; only one broker with estimates 2028+ (1) Revenue Adj. EBITDA $772 $70 Limited Wall Street Projections Past 2027 $462 ($15) ($66) $276 ($81) ($71) $198 $153 $163 $98 ($91) $132 $108 ($103) $81 2026E 2027E 2028E 2029E 2030E 2026E 2027E 2028E 2029E 2030E Memo: # of Est. Memo: # of Est. 7 6 1 1 1 4 4 – – – Prelim. Management Plan vs. Consensus: Prelim. Management Plan vs. Consensus: +21% +42% +110% +184% +290% (26%) (38%) NA NA NA Mgmt. Consensus (Median) 13 Source: Pelican Management, Wall Street research. Note: Dollars in millions. (1) Reflects EBITDA burdened by SBC expense.
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Centerview Financial Analysis 14
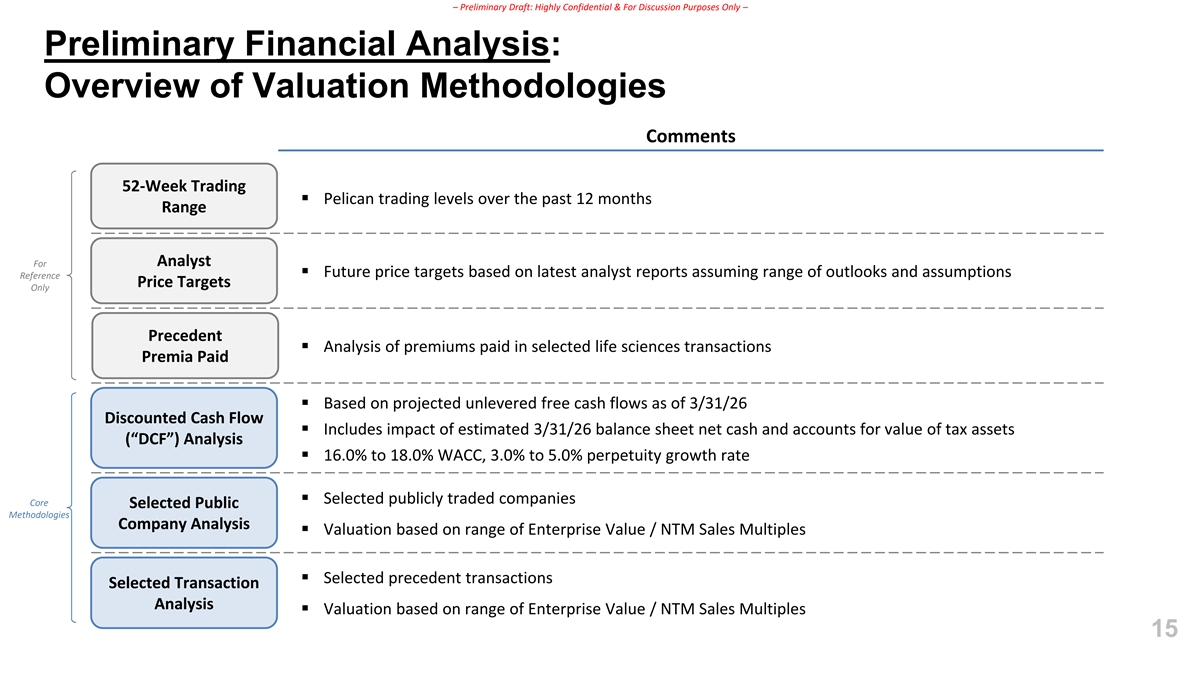
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Financial Analysis: Overview of Valuation Methodologies Comments 52-Week Trading ▪ Pelican trading levels over the past 12 months Range Analyst For ▪ Future price targets based on latest analyst reports assuming range of outlooks and assumptions Reference Price Targets Only Precedent ▪ Analysis of premiums paid in selected life sciences transactions Premia Paid ▪ Based on projected unlevered free cash flows as of 3/31/26 Discounted Cash Flow ▪ Includes impact of estimated 3/31/26 balance sheet net cash and accounts for value of tax assets (“DCF”) Analysis ▪ 16.0% to 18.0% WACC, 3.0% to 5.0% perpetuity growth rate ▪ Selected publicly traded companies Core Selected Public Methodologies Company Analysis ▪ Valuation based on range of Enterprise Value / NTM Sales Multiples ▪ Selected precedent transactions Selected Transaction Analysis ▪ Valuation based on range of Enterprise Value / NTM Sales Multiples 15
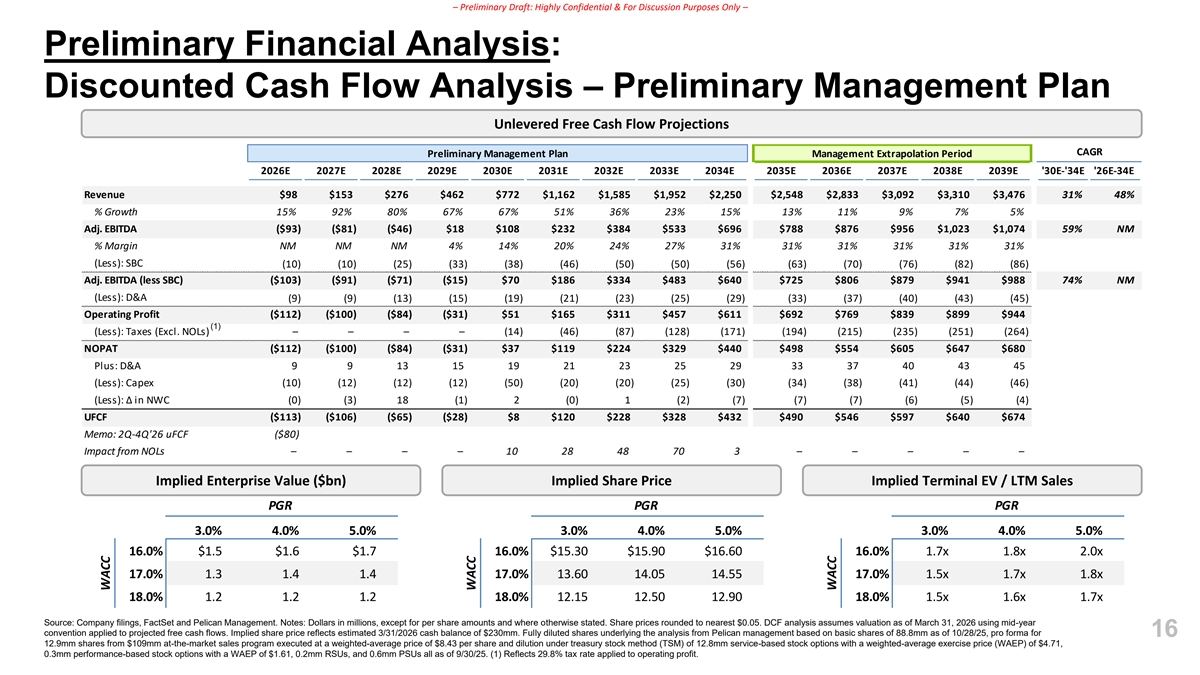
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Financial Analysis: Discounted Cash Flow Analysis – Preliminary Management Plan Unlevered Free Cash Flow Projections CAGR Preliminary Management Plan Management Extrapolation Period 2026E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E 2036E 2037E 2038E 2039E '30E-'34E '26E-34E Revenue $98 $153 $276 $462 $772 $1,162 $1,585 $1,952 $2,250 $2,548 $2,833 $3,092 $3,310 $3,476 31% 48% % Growth 15% 92% 80% 67% 67% 51% 36% 23% 15% 13% 11% 9% 7% 5% Adj. EBITDA ($93) ($81) ($46) $18 $108 $232 $384 $533 $696 $788 $876 $956 $1,023 $1,074 59% NM % Margin NM NM NM 4% 14% 20% 24% 27% 31% 31% 31% 31% 31% 31% (Less): SBC (10) (10) (25) (33) (38) (46) (50) (50) (56) (63) (70) (76) (82) (86) Adj. EBITDA (less SBC) ($103) ($91) ($71) ($15) $70 $186 $334 $483 $640 $725 $806 $879 $941 $988 74% NM (Less): D&A (9) (9) (13) (15) (19) (21) (23) (25) (29) (33) (37) (40) (43) (45) Operating Profit ($112) ($100) ($84) ($31) $51 $165 $311 $457 $611 $692 $769 $839 $899 $944 (1) (Less): Taxes (Excl. NOLs) – – – – (14) (46) (87) (128) (171) (194) (215) (235) (251) (264) NOPAT ($112) ($100) ($84) ($31) $37 $119 $224 $329 $440 $498 $554 $605 $647 $680 Plus: D&A 9 9 13 15 19 21 23 25 29 33 37 40 43 45 (Less): Capex (10) (12) (12) (12) (50) (20) (20) (25) (30) (34) (38) (41) (44) (46) (Less): Δ in NWC (0) (3) 18 (1) 2 (0) 1 (2) (7) (7) (7) (6) (5) (4) UFCF ($113) ($106) ($65) ($28) $8 $120 $228 $328 $432 $490 $546 $597 $640 $674 Memo: 2Q-4Q'26 uFCF ($80) Impact from NOLs – – – – 10 28 48 70 3 – – – – – Implied Enterprise Value ($bn) Implied Share Price Implied Terminal EV / LTM Sales PGR PGR PGR 3.0% 4.0% 5.0% 3.0% 4.0% 5.0% 3.0% 4.0% 5.0% 16.0% $1.5 $1.6 $1.7 16.0% $15.30 $15.90 $16.60 16.0% 1.7x 1.8x 2.0x 17.0% 1.3 1.4 1.4 17.0% 13.60 14.05 14.55 17.0% 1.5x 1.7x 1.8x 18.0% 1.2 1.2 1.2 18.0% 12.15 12.50 12.90 18.0% 1.5x 1.6x 1.7x Source: Company filings, FactSet and Pelican Management. Notes: Dollars in millions, except for per share amounts and where otherwise stated. Share prices rounded to nearest $0.05. DCF analysis assumes valuation as of March 31, 2026 using mid-year convention applied to projected free cash flows. Implied share price reflects estimated 3/31/2026 cash balance of $230mm. Fully diluted shares underlying the analysis from Pelican management based on basic shares of 88.8mm as of 10/28/25, pro forma for 16 12.9mm shares from $109mm at-the-market sales program executed at a weighted-average price of $8.43 per share and dilution under treasury stock method (TSM) of 12.8mm service-based stock options with a weighted-average exercise price (WAEP) of $4.71, 0.3mm performance-based stock options with a WAEP of $1.61, 0.2mm RSUs, and 0.6mm PSUs all as of 9/30/25. (1) Reflects 29.8% tax rate applied to operating profit. WACC WACC WACC
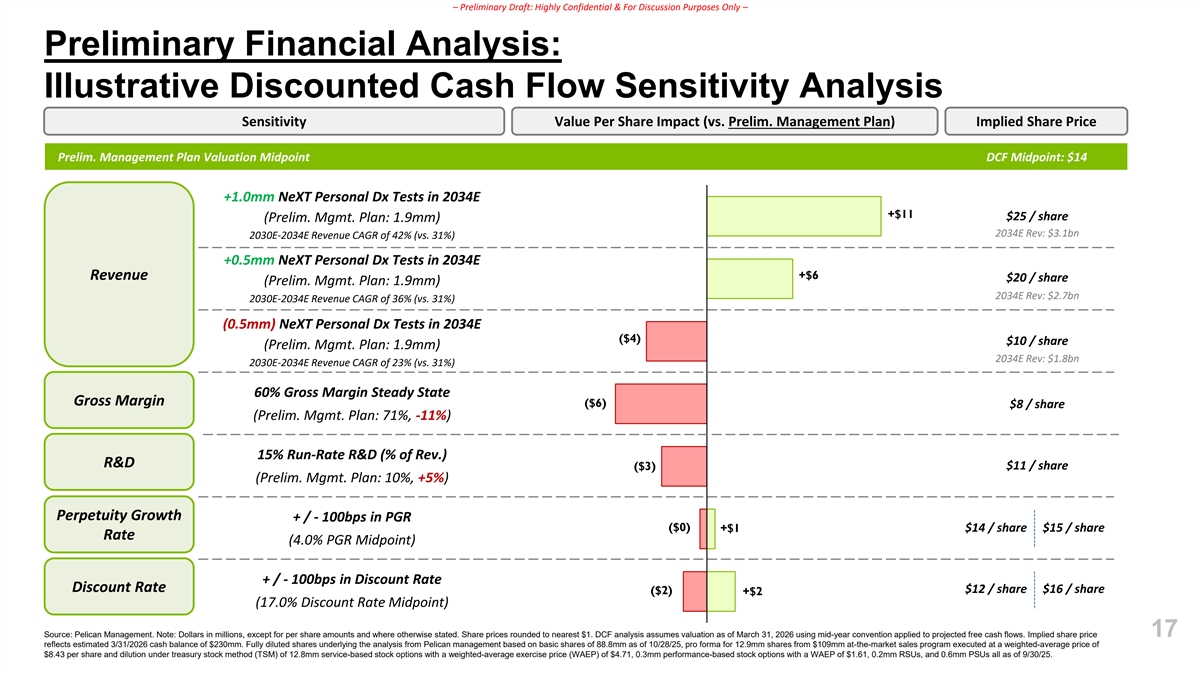
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Financial Analysis: Illustrative Discounted Cash Flow Sensitivity Analysis Sensitivity Value Per Share Impact (vs. Prelim. Management Plan) Implied Share Price Prelim. Management Plan Valuation Midpoint DCF Midpoint: $14 +1.0mm NeXT Personal Dx Tests in 2034E +$11 $25 / share (Prelim. Mgmt. Plan: 1.9mm) 2034E Rev: $3.1bn 2030E-2034E Revenue CAGR of 42% (vs. 31%) +0.5mm NeXT Personal Dx Tests in 2034E +$6 Revenue $20 / share (Prelim. Mgmt. Plan: 1.9mm) 2034E Rev: $2.7bn 2030E-2034E Revenue CAGR of 36% (vs. 31%) (0.5mm) NeXT Personal Dx Tests in 2034E ($4) $10 / share (Prelim. Mgmt. Plan: 1.9mm) 2034E Rev: $1.8bn 2030E-2034E Revenue CAGR of 23% (vs. 31%) 60% Gross Margin Steady State Gross Margin ($6) $8 / share (Prelim. Mgmt. Plan: 71%, -11%) 15% Run-Rate R&D (% of Rev.) R&D ($3) $11 / share (Prelim. Mgmt. Plan: 10%, +5%) Perpetuity Growth + / - 100bps in PGR ($0) +$1 $14 / share $15 / share Rate (4.0% PGR Midpoint) + / - 100bps in Discount Rate Discount Rate $12 / share $16 / share ($2) +$2 (17.0% Discount Rate Midpoint) Source: Pelican Management. Note: Dollars in millions, except for per share amounts and where otherwise stated. Share prices rounded to nearest $1. DCF analysis assumes valuation as of March 31, 2026 using mid-year convention applied to projected free cash flows. Implied share price 17 reflects estimated 3/31/2026 cash balance of $230mm. Fully diluted shares underlying the analysis from Pelican management based on basic shares of 88.8mm as of 10/28/25, pro forma for 12.9mm shares from $109mm at-the-market sales program executed at a weighted-average price of $8.43 per share and dilution under treasury stock method (TSM) of 12.8mm service-based stock options with a weighted-average exercise price (WAEP) of $4.71, 0.3mm performance-based stock options with a WAEP of $1.61, 0.2mm RSUs, and 0.6mm PSUs all as of 9/30/25.
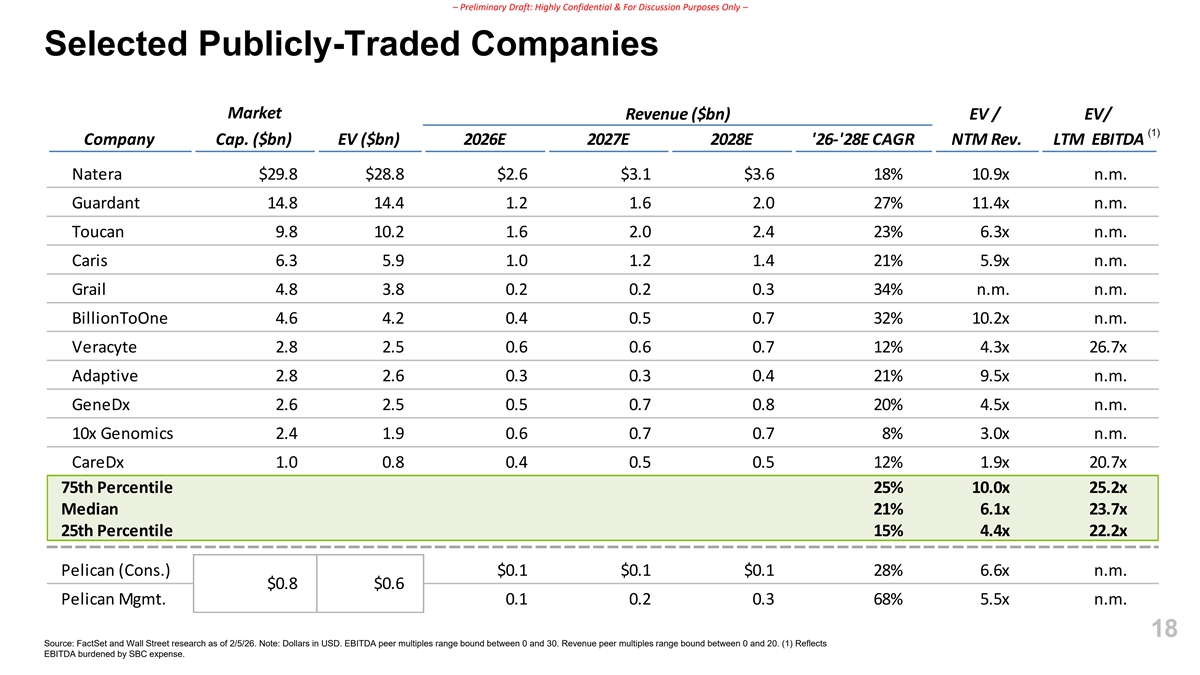
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Selected Publicly-Traded Companies Market Revenue ($bn) EV / EV/ (1) Company Cap. ($bn) EV ($bn) 2026E 2027E 2028E '26-'28E CAGR NTM Rev. LTM EBITDA Natera $29.8 $28.8 $2.6 $3.1 $3.6 18% 10.9x n.m. Guardant 14.8 14.4 1.2 1.6 2.0 27% 11.4x n.m. Toucan 9.8 10.2 1.6 2.0 2.4 23% 6.3x n.m. Caris 6.3 5.9 1.0 1.2 1.4 21% 5.9x n.m. Grail 4.8 3.8 0.2 0.2 0.3 34% n.m. n.m. BillionToOne 4.6 4.2 0.4 0.5 0.7 32% 10.2x n.m. Veracyte 2.8 2.5 0.6 0.6 0.7 12% 4.3x 26.7x Adaptive 2.8 2.6 0.3 0.3 0.4 21% 9.5x n.m. GeneDx 2.6 2.5 0.5 0.7 0.8 20% 4.5x n.m. 10x Genomics 2.4 1.9 0.6 0.7 0.7 8% 3.0x n.m. CareDx 1.0 0.8 0.4 0.5 0.5 12% 1.9x 20.7x 75th Percentile 25% 10.0x 25.2x Median 21% 6.1x 23.7x 25th Percentile 15% 4.4x 22.2x Pelican (Cons.) $0.1 $0.1 $0.1 28% 6.6x n.m. $0.8 $0.6 Pelican Mgmt. 0.1 0.2 0.3 68% 5.5x n.m. 18 Source: FactSet and Wall Street research as of 2/5/26. Note: Dollars in USD. EBITDA peer multiples range bound between 0 and 30. Revenue peer multiples range bound between 0 and 20. (1) Reflects EBITDA burdened by SBC expense.
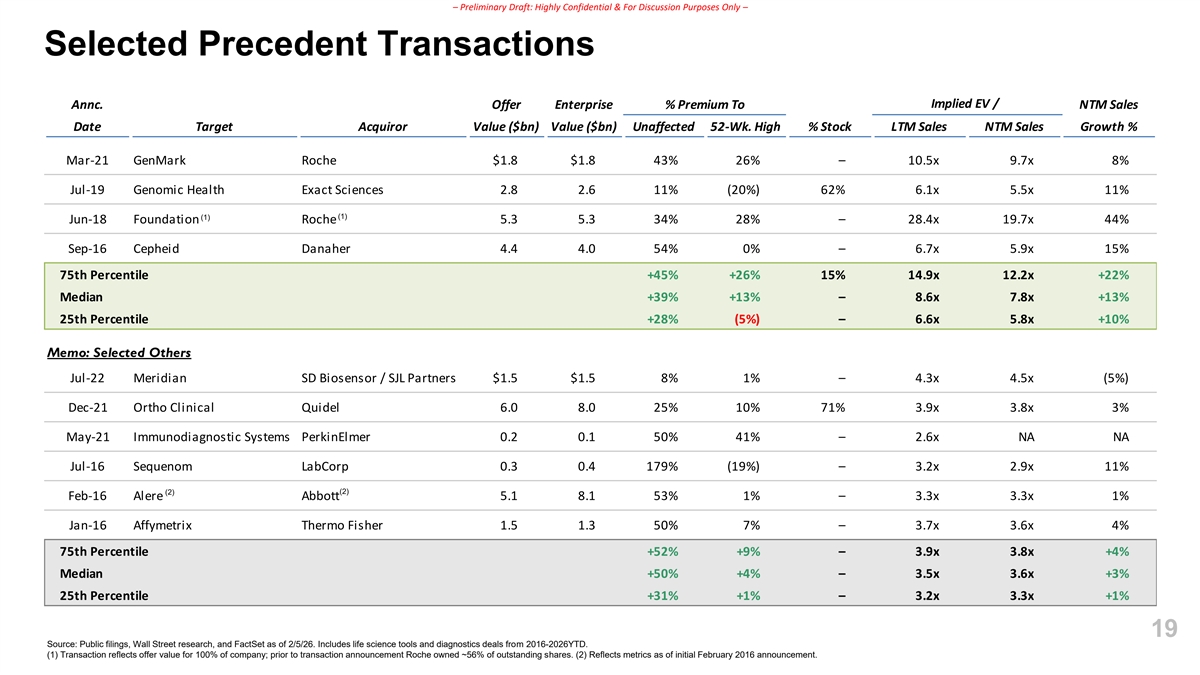
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Selected Precedent Transactions Implied EV / Annc. Offer Enterprise % Premium To NTM Sales Date Target Acquiror Value ($bn) Value ($bn) Unaffected 52-Wk. High % Stock LTM Sales NTM Sales Growth % Mar-21 GenMark Roche $1.8 $1.8 43% 26% – 10.5x 9.7x 8% Jul-19 Genomic Health Exact Sciences 2.8 2.6 11% (20%) 62% 6.1x 5.5x 11% (1) (1) Jun-18 Foundation Roche 5.3 5.3 34% 28% – 28.4x 19.7x 44% Sep-16 Cepheid Danaher 4.4 4.0 54% 0% – 6.7x 5.9x 15% 75th Percentile +45% +26% 15% 14.9x 12.2x +22% Median +39% +13% – 8.6x 7.8x +13% 25th Percentile +28% (5%) – 6.6x 5.8x +10% Memo: Selected Others Jul-22 Meridian SD Biosensor / SJL Partners $1.5 $1.5 8% 1% – 4.3x 4.5x (5%) Dec-21 Ortho Clinical Quidel 6.0 8.0 25% 10% 71% 3.9x 3.8x 3% May-21 Immunodiagnostic Systems PerkinElmer 0.2 0.1 50% 41% – 2.6x NA NA Jul-16 Sequenom LabCorp 0.3 0.4 179% (19%) – 3.2x 2.9x 11% (2) (2) Feb-16 Alere Abbott 5.1 8.1 53% 1% – 3.3x 3.3x 1% Jan-16 Affymetrix Thermo Fisher 1.5 1.3 50% 7% – 3.7x 3.6x 4% 75th Percentile +52% +9% – 3.9x 3.8x +4% Median +50% +4% – 3.5x 3.6x +3% 25th Percentile +31% +1% – 3.2x 3.3x +1% 19 Source: Public filings, Wall Street research, and FactSet as of 2/5/26. Includes life science tools and diagnostics deals from 2016-2026YTD. (1) Transaction reflects offer value for 100% of company; prior to transaction announcement Roche owned ~56% of outstanding shares. (2) Reflects metrics as of initial February 2016 announcement.
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary TD Cowen Financial Analysis 20
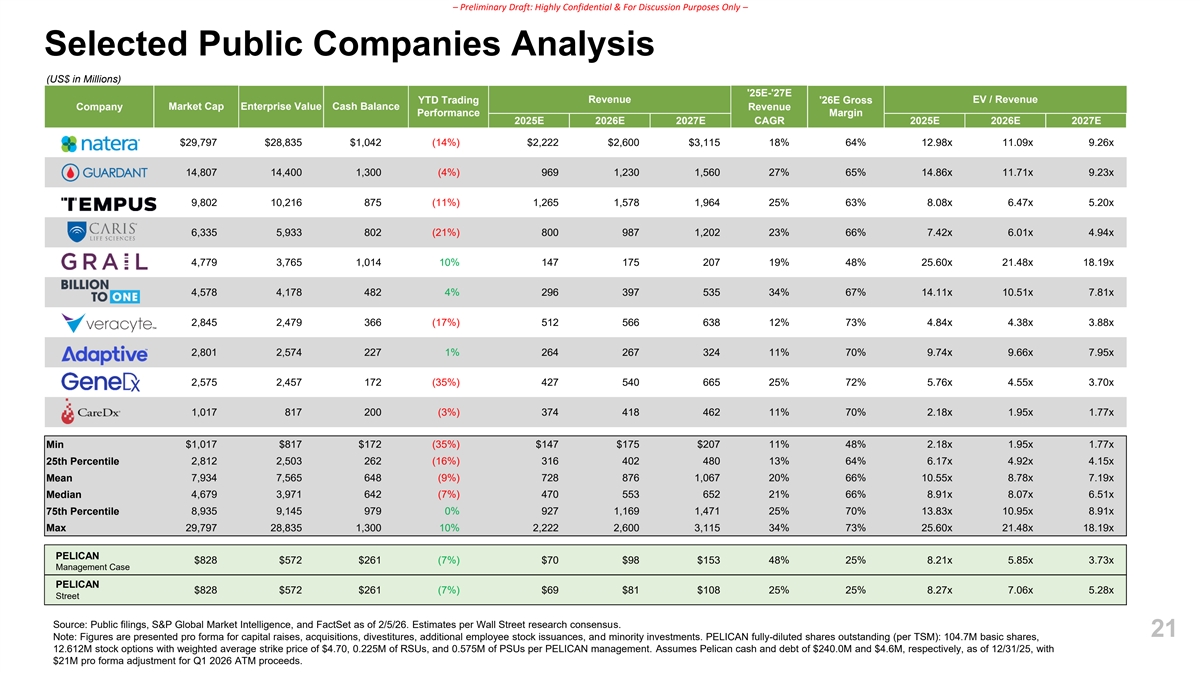
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Selected Public Companies Analysis (US$ in Millions) '25E-'27E YTD Trading Revenue '26E Gross EV / Revenue Company Market Cap Enterprise Value Cash Balance Revenue Performance Margin 2025E 2026E 2027E CAGR 2025E 2026E 2027E $29,797 $28,835 $1,042 (14%) $2,222 $2,600 $3,115 18% 64% 12.98x 11.09x 9.26x 14,807 14,400 1,300 (4%) 969 1,230 1,560 27% 65% 14.86x 11.71x 9.23x 9,802 10,216 875 (11%) 1,265 1,578 1,964 25% 63% 8.08x 6.47x 5.20x 6,335 5,933 802 (21%) 800 987 1,202 23% 66% 7.42x 6.01x 4.94x 4,779 3,765 1,014 10% 147 175 207 19% 48% 25.60x 21.48x 18.19x 4,578 4,178 482 4% 296 397 535 34% 67% 14.11x 10.51x 7.81x 2,845 2,479 366 (17%) 512 566 638 12% 73% 4.84x 4.38x 3.88x 2,801 2,574 227 1% 264 267 324 11% 70% 9.74x 9.66x 7.95x 2,575 2,457 172 (35%) 427 540 665 25% 72% 5.76x 4.55x 3.70x 1,017 817 200 (3%) 374 418 462 11% 70% 2.18x 1.95x 1.77x $1,017 $817 $172 (35%) $147 $175 $207 11% 48% 2.18x 1.95x 1.77x Min 25th Percentile 2,812 2,503 262 (16%) 316 402 480 13% 64% 6.17x 4.92x 4.15x Mean 7,934 7,565 648 (9%) 728 876 1,067 20% 66% 10.55x 8.78x 7.19x 4,679 3,971 642 (7%) 470 553 652 21% 66% 8.91x 8.07x 6.51x Median 75th Percentile 8,935 9,145 979 0% 927 1,169 1,471 25% 70% 13.83x 10.95x 8.91x Max 29,797 28,835 1,300 10% 2,222 2,600 3,115 34% 73% 25.60x 21.48x 18.19x PELICAN $828 $572 $261 (7%) $70 $98 $153 48% 25% 8.21x 5.85x 3.73x Management Case PELICAN $828 $572 $261 (7%) $69 $81 $108 25% 25% 8.27x 7.06x 5.28x Street Source: Public filings, S&P Global Market Intelligence, and FactSet as of 2/5/26. Estimates per Wall Street research consensus. 21 Note: Figures are presented pro forma for capital raises, acquisitions, divestitures, additional employee stock issuances, and minority investments. PELICAN fully-diluted shares outstanding (per TSM): 104.7M basic shares, 12.612M stock options with weighted average strike price of $4.70, 0.225M of RSUs, and 0.575M of PSUs per PELICAN management. Assumes Pelican cash and debt of $240.0M and $4.6M, respectively, as of 12/31/25, with $21M pro forma adjustment for Q1 2026 ATM proceeds.
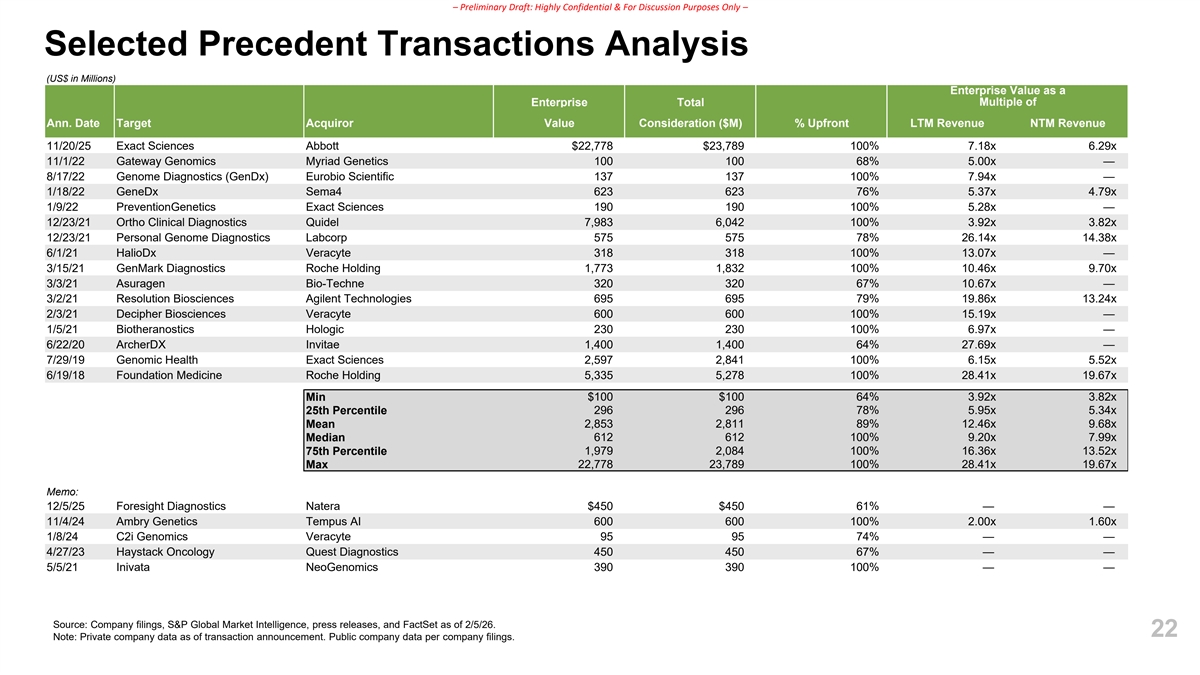
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Selected Precedent Transactions Analysis (US$ in Millions) Enterprise Value as a Enterprise Total Multiple of Ann. Date Target Acquiror Value Consideration ($M) % Upfront LTM Revenue NTM Revenue 11/20/25 Exact Sciences Abbott $22,778 $23,789 100% 7.18x 6.29x 11/1/22 Gateway Genomics Myriad Genetics 100 100 68% 5.00x — 8/17/22 Genome Diagnostics (GenDx) Eurobio Scientific 137 137 100% 7.94x — 1/18/22 GeneDx Sema4 623 623 76% 5.37x 4.79x 1/9/22 PreventionGenetics Exact Sciences 190 190 100% 5.28x — 12/23/21 Ortho Clinical Diagnostics Quidel 7,983 6,042 100% 3.92x 3.82x 12/23/21 Personal Genome Diagnostics Labcorp 575 575 78% 26.14x 14.38x 6/1/21 HalioDx Veracyte 318 318 100% 13.07x — 3/15/21 GenMark Diagnostics Roche Holding 1,773 1,832 100% 10.46x 9.70x 3/3/21 Asuragen Bio-Techne 320 320 67% 10.67x — 3/2/21 Resolution Biosciences Agilent Technologies 695 695 79% 19.86x 13.24x 2/3/21 Decipher Biosciences Veracyte 600 600 100% 15.19x — 1/5/21 Biotheranostics Hologic 230 230 100% 6.97x — 6/22/20 ArcherDX Invitae 1,400 1,400 64% 27.69x — 7/29/19 Genomic Health Exact Sciences 2,597 2,841 100% 6.15x 5.52x 6/19/18 Foundation Medicine Roche Holding 5,335 5,278 100% 28.41x 19.67x Min $100 $100 64% 3.92x 3.82x 296 296 78% 5.95x 5.34x 25th Percentile Mean 2,853 2,811 89% 12.46x 9.68x Median 612 612 100% 9.20x 7.99x 75th Percentile 1,979 2,084 100% 16.36x 13.52x Max 22,778 23,789 100% 28.41x 19.67x Memo: 12/5/25 Foresight Diagnostics Natera $450 $450 61% — — 11/4/24 Ambry Genetics Tempus AI 600 600 100% 2.00x 1.60x 1/8/24 C2i Genomics Veracyte 95 95 74% — — 4/27/23 Haystack Oncology Quest Diagnostics 450 450 67% — — 5/5/21 Inivata NeoGenomics 390 390 100% — — Source: Company filings, S&P Global Market Intelligence, press releases, and FactSet as of 2/5/26. 22 Note: Private company data as of transaction announcement. Public company data per company filings.
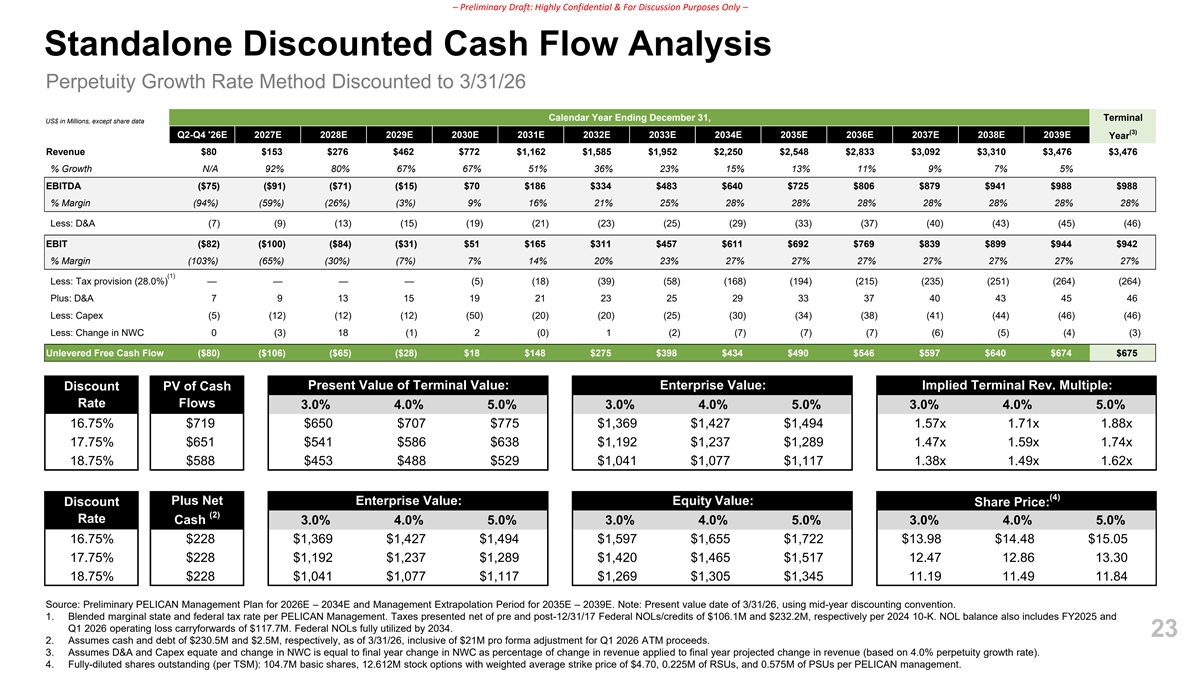
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Standalone Discounted Cash Flow Analysis Perpetuity Growth Rate Method Discounted to 3/31/26 Calendar Year Ending December 31, Terminal US$ in Millions, except share data (3) Q2-Q4 '26E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E 2036E 2037E 2038E 2039E Year Revenue $80 $153 $276 $462 $772 $1,162 $1,585 $1,952 $2,250 $2,548 $2,833 $3,092 $3,310 $3,476 $3,476 % Growth N/A 92% 80% 67% 67% 51% 36% 23% 15% 13% 11% 9% 7% 5% EBITDA ($75) ($91) ($71) ($15) $70 $186 $334 $483 $640 $725 $806 $879 $941 $988 $988 % Margin (94%) (59%) (26%) (3%) 9% 16% 21% 25% 28% 28% 28% 28% 28% 28% 28% Less: D&A (7) (9) (13) (15) (19) (21) (23) (25) (29) (33) (37) (40) (43) (45) (46) EBIT ($82) ($100) ($84) ($31) $51 $165 $311 $457 $611 $692 $769 $839 $899 $944 $942 % Margin (103%) (65%) (30%) (7%) 7% 14% 20% 23% 27% 27% 27% 27% 27% 27% 27% (1) Less: Tax provision (28.0%) — — — — (5) (18) (39) (58) (168) (194) (215) (235) (251) (264) (264) Plus: D&A 7 9 13 15 19 21 23 25 29 33 37 40 43 45 46 Less: Capex (5) (12) (12) (12) (50) (20) (20) (25) (30) (34) (38) (41) (44) (46) (46) Less: Change in NWC 0 (3) 18 (1) 2 (0) 1 (2) (7) (7) (7) (6) (5) (4) (3) Unlevered Free Cash Flow ($80) ($106) ($65) ($28) $18 $148 $275 $398 $434 $490 $546 $597 $640 $674 $675 Present Value of Terminal Value: Enterprise Value: Implied Terminal Rev. Multiple: Discount PV of Cash Rate Flows 3.0% 4.0% 5.0% 3.0% 4.0% 5.0% 3.0% 4.0% 5.0% 16.75% $719 $650 $707 $775 $1,369 $1,427 $1,494 1.57x 1.71x 1.88x 17.75% $651 $541 $586 $638 $1,192 $1,237 $1,289 1.47x 1.59x 1.74x 18.75% $588 $453 $488 $529 $1,041 $1,077 $1,117 1.38x 1.49x 1.62x (4) Plus Net Enterprise Value: Equity Value: Discount Share Price: (2) Rate Cash 3.0% 4.0% 5.0% 3.0% 4.0% 5.0% 3.0% 4.0% 5.0% 16.75% $228 $1,369 $1,427 $1,494 $1,597 $1,655 $1,722 $13.98 $14.48 $15.05 17.75% $228 $1,192 $1,237 $1,289 $1,420 $1,465 $1,517 12.47 12.86 13.30 18.75% $228 $1,041 $1,077 $1,117 $1,269 $1,305 $1,345 11.19 11.49 11.84 Source: Preliminary PELICAN Management Plan for 2026E – 2034E and Management Extrapolation Period for 2035E – 2039E. Note: Present value date of 3/31/26, using mid-year discounting convention. 1. Blended marginal state and federal tax rate per PELICAN Management. Taxes presented net of pre and post-12/31/17 Federal NOLs/credits of $106.1M and $232.2M, respectively per 2024 10-K. NOL balance also includes FY2025 and Q1 2026 operating loss carryforwards of $117.7M. Federal NOLs fully utilized by 2034. 23 2. Assumes cash and debt of $230.5M and $2.5M, respectively, as of 3/31/26, inclusive of $21M pro forma adjustment for Q1 2026 ATM proceeds. 3. Assumes D&A and Capex equate and change in NWC is equal to final year change in NWC as percentage of change in revenue applied to final year projected change in revenue (based on 4.0% perpetuity growth rate). 4. Fully-diluted shares outstanding (per TSM): 104.7M basic shares, 12.612M stock options with weighted average strike price of $4.70, 0.225M of RSUs, and 0.575M of PSUs per PELICAN management.
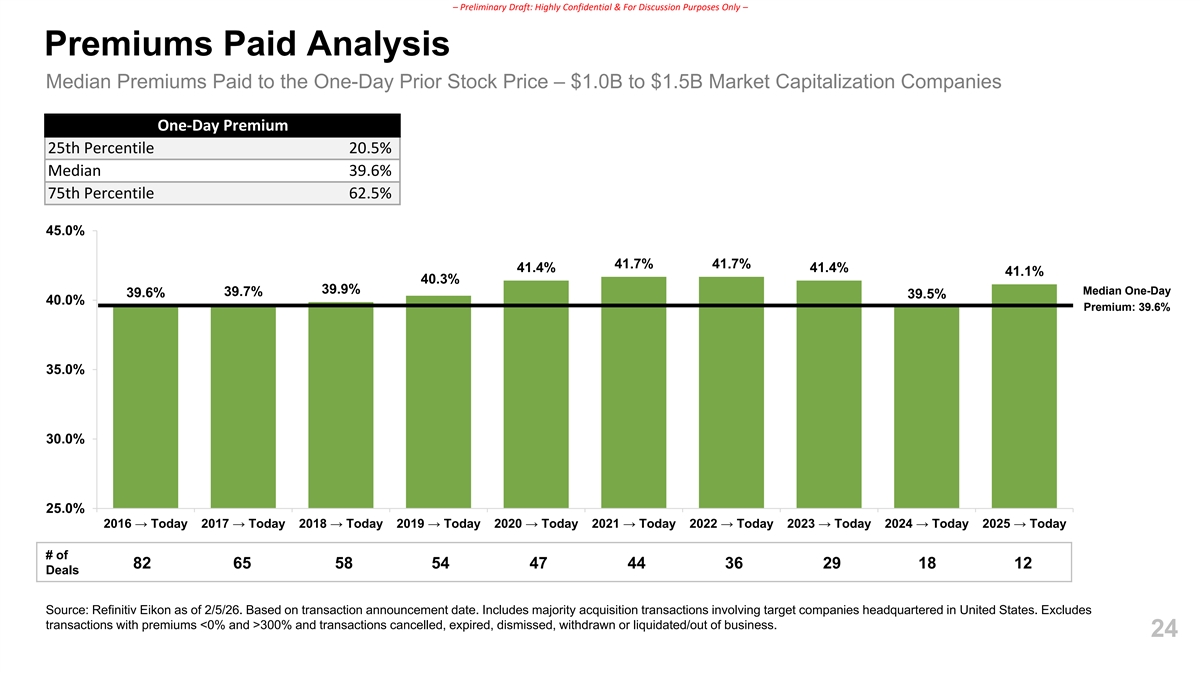
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Premiums Paid Analysis Median Premiums Paid to the One-Day Prior Stock Price – $1.0B to $1.5B Market Capitalization Companies One-Day Premium 25th Percentile 20.5% Median 39.6% 75th Percentile 62.5% 45.0% 41.7% 41.7% 41.4% 41.4% 41.1% 40.3% 39.9% Median One-Day 39.7% 39.6% 39.5% 40.0% Premium: 39.6% 35.0% 30.0% 25.0% 2016 → Today 2017 → Today 2018 → Today 2019 → Today 2020 → Today 2021 → Today 2022 → Today 2023 → Today 2024 → Today 2025 → Today # of 82 65 58 54 47 44 36 29 18 12 Deals Source: Refinitiv Eikon as of 2/5/26. Based on transaction announcement date. Includes majority acquisition transactions involving target companies headquartered in United States. Excludes transactions with premiums <0% and >300% and transactions cancelled, expired, dismissed, withdrawn or liquidated/out of business. 24
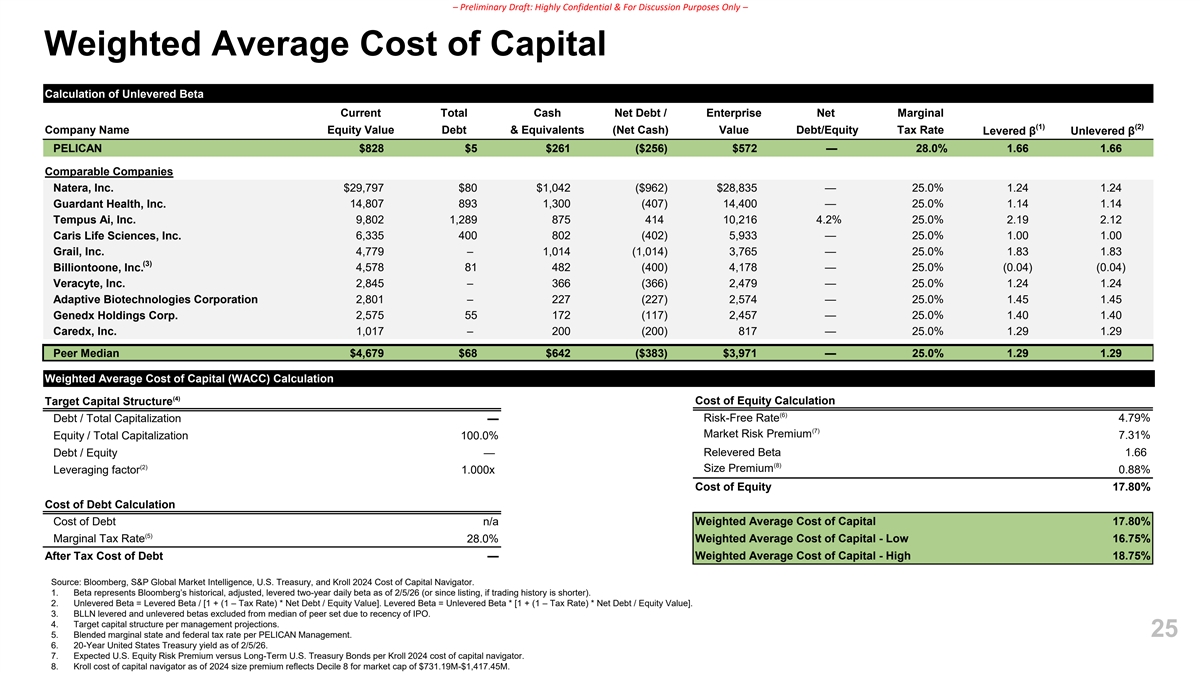
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Weighted Average Cost of Capital Calculation of Unlevered Beta Current Total Cash Net Debt / Enterprise Net Marginal (1) (2) Company Name Equity Value Debt & Equivalents (Net Cash) Value Debt/Equity Tax Rate Levered β Unlevered β PELICAN $828 $5 $261 ($256) $572 — 28.0% 1.66 1.66 Comparable Companies $29,797 $80 $1,042 ($962) $28,835 — 25.0% 1.24 1.24 Natera, Inc. Guardant Health, Inc. 14,807 893 1,300 (407) 14,400 — 25.0% 1.14 1.14 Tempus Ai, Inc. 9,802 1,289 875 414 10,216 4.2% 25.0% 2.19 2.12 Caris Life Sciences, Inc. 6,335 400 802 (402) 5,933 — 25.0% 1.00 1.00 4,779 – 1,014 (1,014) 3,765 — 25.0% 1.83 1.83 Grail, Inc. (3) Billiontoone, Inc. 4,578 81 482 (400) 4,178 — 25.0% (0.04) (0.04) Veracyte, Inc. 2,845 – 366 (366) 2,479 — 25.0% 1.24 1.24 Adaptive Biotechnologies Corporation 2,801 – 227 (227) 2,574 — 25.0% 1.45 1.45 Genedx Holdings Corp. 2,575 55 172 (117) 2,457 — 25.0% 1.40 1.40 Caredx, Inc. 1,017 – 200 (200) 817 — 25.0% 1.29 1.29 Peer Median $4,679 $68 $642 ($383) $3,971 — 25.0% 1.29 1.29 Weighted Average Cost of Capital (WACC) Calculation (4) Target Capital Structure Cost of Equity Calculation (6) Risk-Free Rate Debt / Total Capitalization — 4.79% (7) Market Risk Premium 7.31% Equity / Total Capitalization 100.0% Debt / Equity — Relevered Beta 1.66 (8) (2) Size Premium Leveraging factor 1.000x 0.88% Cost of Equity 17.80% Cost of Debt Calculation Cost of Debt n/a Weighted Average Cost of Capital 17.80% (5) Marginal Tax Rate 28.0% Weighted Average Cost of Capital - Low 16.75% After Tax Cost of Debt — Weighted Average Cost of Capital - High 18.75% Source: Bloomberg, S&P Global Market Intelligence, U.S. Treasury, and Kroll 2024 Cost of Capital Navigator. 1. Beta represents Bloomberg’s historical, adjusted, levered two-year daily beta as of 2/5/26 (or since listing, if trading history is shorter). 2. Unlevered Beta = Levered Beta / [1 + (1 – Tax Rate) * Net Debt / Equity Value]. Levered Beta = Unlevered Beta * [1 + (1 – Tax Rate) * Net Debt / Equity Value]. 3. BLLN levered and unlevered betas excluded from median of peer set due to recency of IPO. 4. Target capital structure per management projections. 5. Blended marginal state and federal tax rate per PELICAN Management. 25 6. 20-Year United States Treasury yield as of 2/5/26. 7. Expected U.S. Equity Risk Premium versus Long-Term U.S. Treasury Bonds per Kroll 2024 cost of capital navigator. 8. Kroll cost of capital navigator as of 2024 size premium reflects Decile 8 for market cap of $731.19M-$1,417.45M.
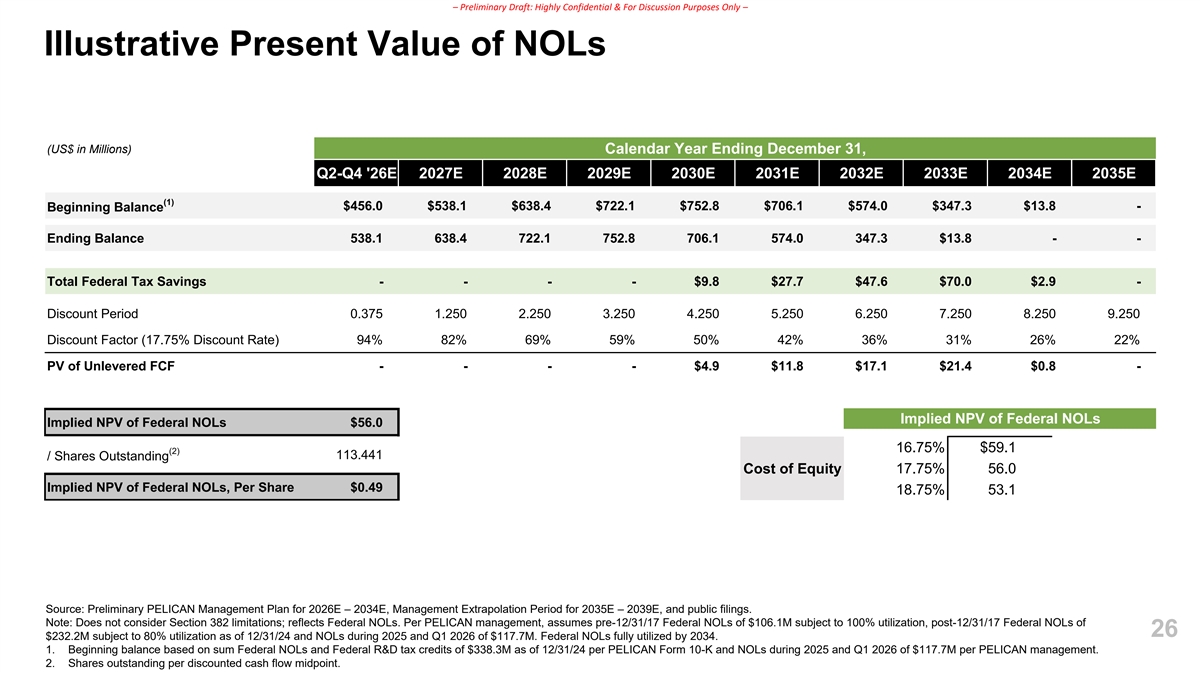
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Illustrative Present Value of NOLs (US$ in Millions) Calendar Year Ending December 31, Q2-Q4 '26E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E (1) $456.0 $538.1 $638.4 $722.1 $752.8 $706.1 $574.0 $347.3 $13.8 - Beginning Balance Ending Balance 538.1 638.4 722.1 752.8 706.1 574.0 347.3 $13.8 - - Total Federal Tax Savings - - - - $9.8 $27.7 $47.6 $70.0 $2.9 - Discount Period 0.375 1.250 2.250 3.250 4.250 5.250 6.250 7.250 8.250 9.250 Discount Factor (17.75% Discount Rate) 94% 82% 69% 59% 50% 42% 36% 31% 26% 22% PV of Unlevered FCF - - - - $4.9 $11.8 $17.1 $21.4 $0.8 - Implied NPV of Federal NOLs Implied NPV of Federal NOLs $56.0 16.75% $59.1 (2) 113.441 / Shares Outstanding Cost of Equity 17.75% 56.0 Implied NPV of Federal NOLs, Per Share $0.49 18.75% 53.1 Source: Preliminary PELICAN Management Plan for 2026E – 2034E, Management Extrapolation Period for 2035E – 2039E, and public filings. Note: Does not consider Section 382 limitations; reflects Federal NOLs. Per PELICAN management, assumes pre-12/31/17 Federal NOLs of $106.1M subject to 100% utilization, post-12/31/17 Federal NOLs of 26 $232.2M subject to 80% utilization as of 12/31/24 and NOLs during 2025 and Q1 2026 of $117.7M. Federal NOLs fully utilized by 2034. 1. Beginning balance based on sum Federal NOLs and Federal R&D tax credits of $338.3M as of 12/31/24 per PELICAN Form 10-K and NOLs during 2025 and Q1 2026 of $117.7M per PELICAN management. 2. Shares outstanding per discounted cash flow midpoint.
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary External Perspectives on Toucan 27
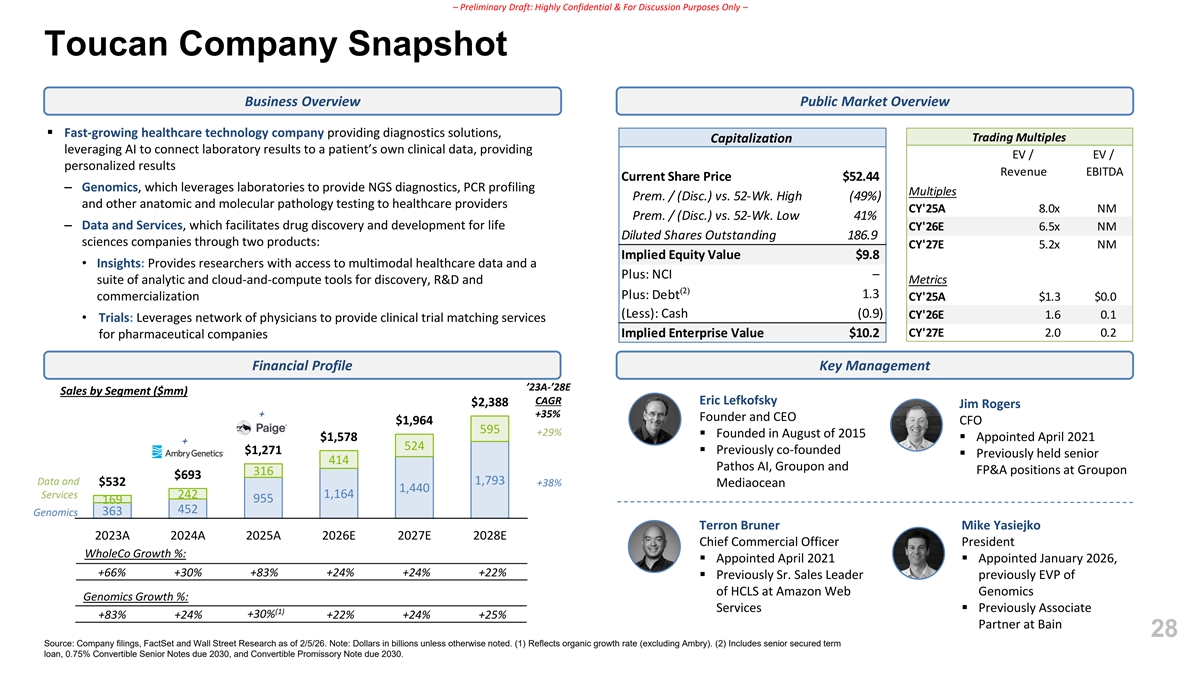
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Toucan Company Snapshot Business Overview Public Market Overview ▪ Fast-growing healthcare technology company providing diagnostics solutions, Trading Multiples Capitalization leveraging AI to connect laboratory results to a patient’s own clinical data, providing EV / EV / personalized results Revenue EBITDA Current Share Price $52.44 – Genomics, which leverages laboratories to provide NGS diagnostics, PCR profiling Multiples Prem. / (Disc.) vs. 52-Wk. High (49%) and other anatomic and molecular pathology testing to healthcare providers CY'25A 8.0x NM Prem. / (Disc.) vs. 52-Wk. Low 41% – Data and Services, which facilitates drug discovery and development for life CY'26E 6.5x NM Diluted Shares Outstanding 186.9 sciences companies through two products: CY'27E 5.2x NM Implied Equity Value $9.8 • Insights: Provides researchers with access to multimodal healthcare data and a Plus: NCI – suite of analytic and cloud-and-compute tools for discovery, R&D and Metrics (2) Plus: Debt 1.3 commercialization CY'25A $1.3 $0.0 (Less): Cash (0.9) CY'26E 1.6 0.1 • Trials: Leverages network of physicians to provide clinical trial matching services Implied Enterprise Value $10.2 CY'27E 2.0 0.2 for pharmaceutical companies Financial Profile Key Management ’23A-’28E Sales by Segment ($mm) CAGR Eric Lefkofsky $2,388 Jim Rogers + +35% Founder and CEO $1,964 CFO 595 +29% ▪ Founded in August of 2015 $1,578▪ Appointed April 2021 + 524 ▪ Previously co-founded $1,271 ▪ Previously held senior 414 Pathos AI, Groupon and FP&A positions at Groupon 316 $693 Data and 1,793 $532 +38% Mediaocean 1,440 Services 242 1,164 955 169 452 363 Genomics Terron Bruner Mike Yasiejko 2023A 2024A 2025A 2026E 2027E 2028E Chief Commercial Officer President WholeCo Growth %: ▪ Appointed April 2021▪ Appointed January 2026, +66% +30% +83% +24% +24% +22% ▪ Previously Sr. Sales Leader previously EVP of of HCLS at Amazon Web Genomics Genomics Growth %: Services▪ Previously Associate (1) +30% +83% +24% +22% +24% +25% Partner at Bain 28 Source: Company filings, FactSet and Wall Street Research as of 2/5/26. Note: Dollars in billions unless otherwise noted. (1) Reflects organic growth rate (excluding Ambry). (2) Includes senior secured term loan, 0.75% Convertible Senior Notes due 2030, and Convertible Promissory Note due 2030.
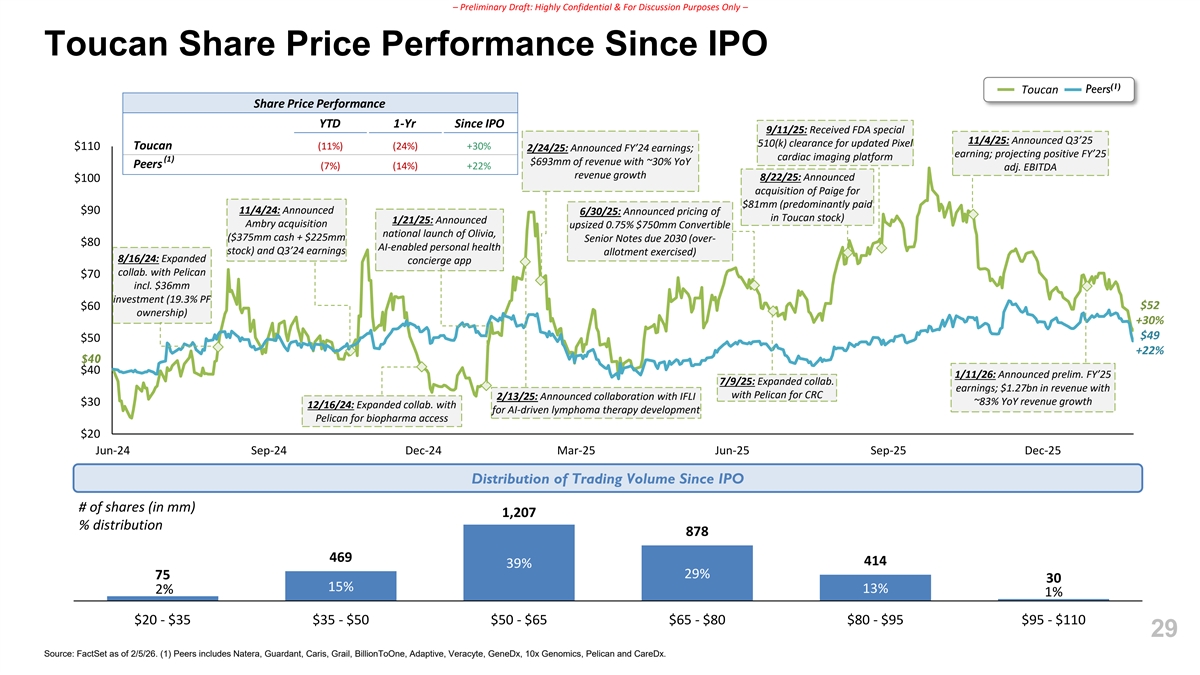
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Toucan Share Price Performance Since IPO (1) Toucan Peers Share Price Performance YTD 1-Yr Since IPO 9/11/25: Received FDA special 11/4/25: Announced Q3’25 510(k) clearance for updated Pixel $110 Toucan (11%) (24%) +30% 2/24/25: Announced FY’24 earnings; earning; projecting positive FY’25 cardiac imaging platform (1) $693mm of revenue with ~30% YoY Peers (7%) (14%) +22% adj. EBITDA revenue growth 8/22/25: Announced $100 acquisition of Paige for $81mm (predominantly paid $90 11/4/24: Announced 6/30/25: Announced pricing of in Toucan stock) 1/21/25: Announced Ambry acquisition upsized 0.75% $750mm Convertible national launch of Olivia, ($375mm cash + $225mm Senior Notes due 2030 (over- $80 AI-enabled personal health stock) and Q3’24 earnings allotment exercised) 8/16/24: Expanded concierge app collab. with Pelican $70 incl. $36mm investment (19.3% PF $52 $60 ownership) +30% $49 $50 +22% $40 $40 1/11/26: Announced prelim. FY’25 7/9/25: Expanded collab. earnings; $1.27bn in revenue with with Pelican for CRC 2/13/25: Announced collaboration with IFLI ~83% YoY revenue growth $30 12/16/24: Expanded collab. with for AI-driven lymphoma therapy development Pelican for biopharma access $20 Jun-24 Sep-24 Dec-24 Mar-25 Jun-25 Sep-25 Dec-25 Distribution of Trading Volume Since IPO # of shares (in mm) 1,207 % distribution 878 469 414 39% 29% 75 30 15% 2% 13% 1% $20 - $35 $35 - $50 $50 - $65 $65 - $80 $80 - $95 $95 - $110 29 Source: FactSet as of 2/5/26. (1) Peers includes Natera, Guardant, Caris, Grail, BillionToOne, Adaptive, Veracyte, GeneDx, 10x Genomics, Pelican and CareDx.
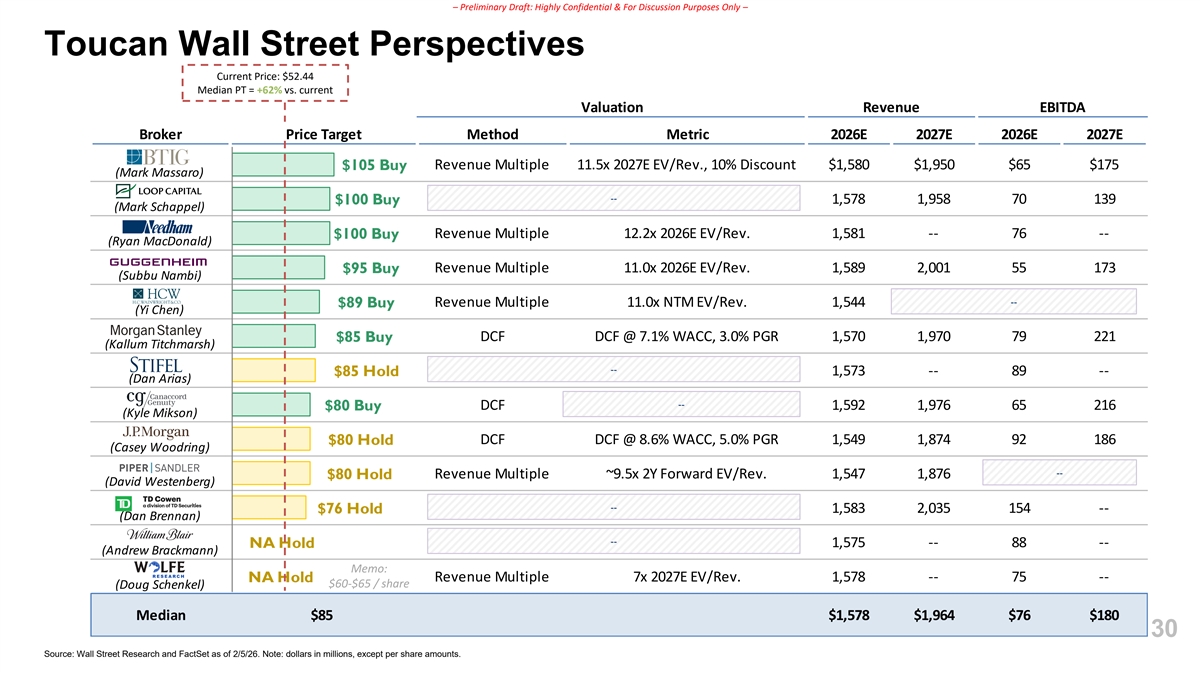
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Toucan Wall Street Perspectives Current Price: $52.44 Median PT = +62% vs. current Valuation Revenue EBITDA Broker Price Target Method Metric 2026E 2027E 2026E 2027E $105 Buy Revenue Multiple 11.5x 2027E EV/Rev., 10% Discount $1,580 $1,950 $65 $175 (Mark Massaro) -- 1,578 1,958 70 139 $100 Buy (Mark Schappel) $100 Buy Revenue Multiple 12.2x 2026E EV/Rev. 1,581 -- 76 -- (Ryan MacDonald) Revenue Multiple 11.0x 2026E EV/Rev. 1,589 2,001 55 173 $95 Buy (Subbu Nambi) -- $89 Buy Revenue Multiple 11.0x NTM EV/Rev. 1,544 -- -- -- (Yi Chen) DCF DCF @ 7.1% WACC, 3.0% PGR 1,570 1,970 79 221 $85 Buy (Kallum Titchmarsh) -- $85 Hold 1,573 -- 89 -- (Dan Arias) -- DCF 1,592 1,976 65 216 $80 Buy (Kyle Mikson) DCF DCF @ 8.6% WACC, 5.0% PGR 1,549 1,874 92 186 $80 Hold (Casey Woodring) -- Revenue Multiple ~9.5x 2Y Forward EV/Rev. 1,547 1,876 -- -- $80 Hold (David Westenberg) -- 1,583 2,035 154 -- $76 Hold (Dan Brennan) -- NA Hold 1,575 -- 88 -- (Andrew Brackmann) Memo: Revenue Multiple 7x 2027E EV/Rev. 1,578 -- 75 -- NA Hold $60-$65 / share (Doug Schenkel) Median $85 $1,578 $1,964 $76 $180 30 Source: Wall Street Research and FactSet as of 2/5/26. Note: dollars in millions, except per share amounts.
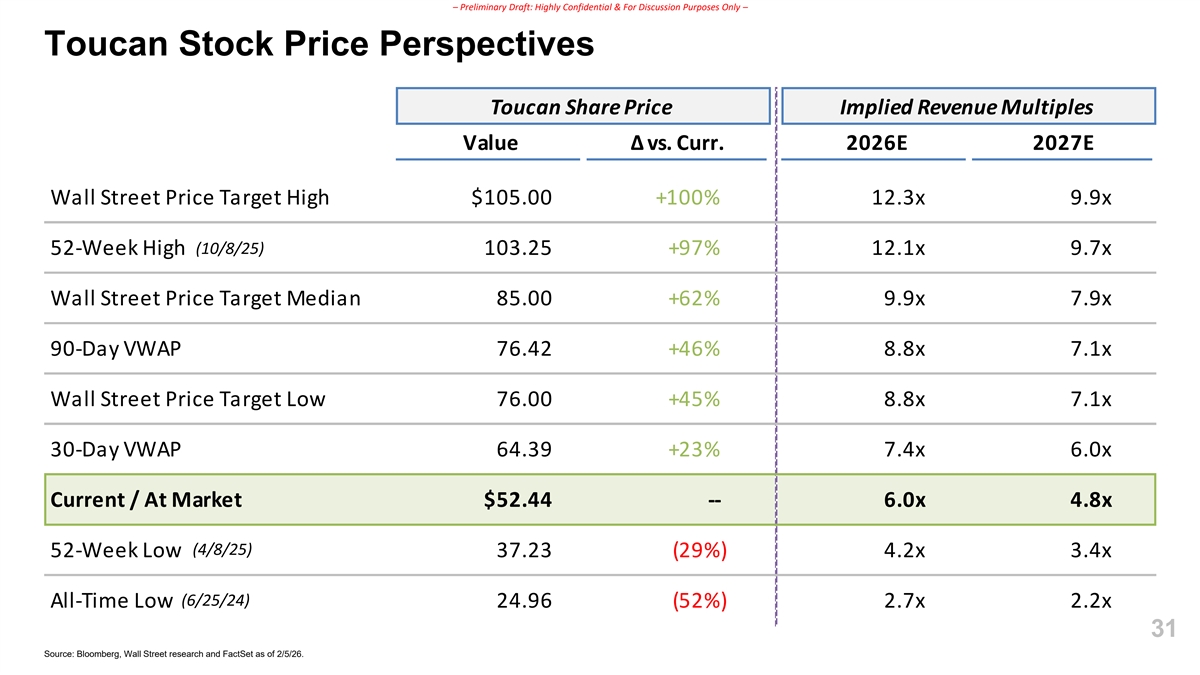
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Toucan Stock Price Perspectives Toucan Share Price Implied Revenue Multiples Value Δ vs. Curr. 2026E 2027E Wall Street Price Target High $105.00 +100% 12.3x 9.9x (10/8/25) 52-Week High 103.25 +97% 12.1x 9.7x Wall Street Price Target Median 85.00 +62% 9.9x 7.9x 90-Day VWAP 76.42 +46% 8.8x 7.1x Wall Street Price Target Low 76.00 +45% 8.8x 7.1x 30-Day VWAP 64.39 +23% 7.4x 6.0x Current / At Market $52.44 -- 6.0x 4.8x (4/8/25) 52-Week Low 37.23 (29%) 4.2x 3.4x (6/25/24) All-Time Low 24.96 (52%) 2.7x 2.2x 31 Source: Bloomberg, Wall Street research and FactSet as of 2/5/26.
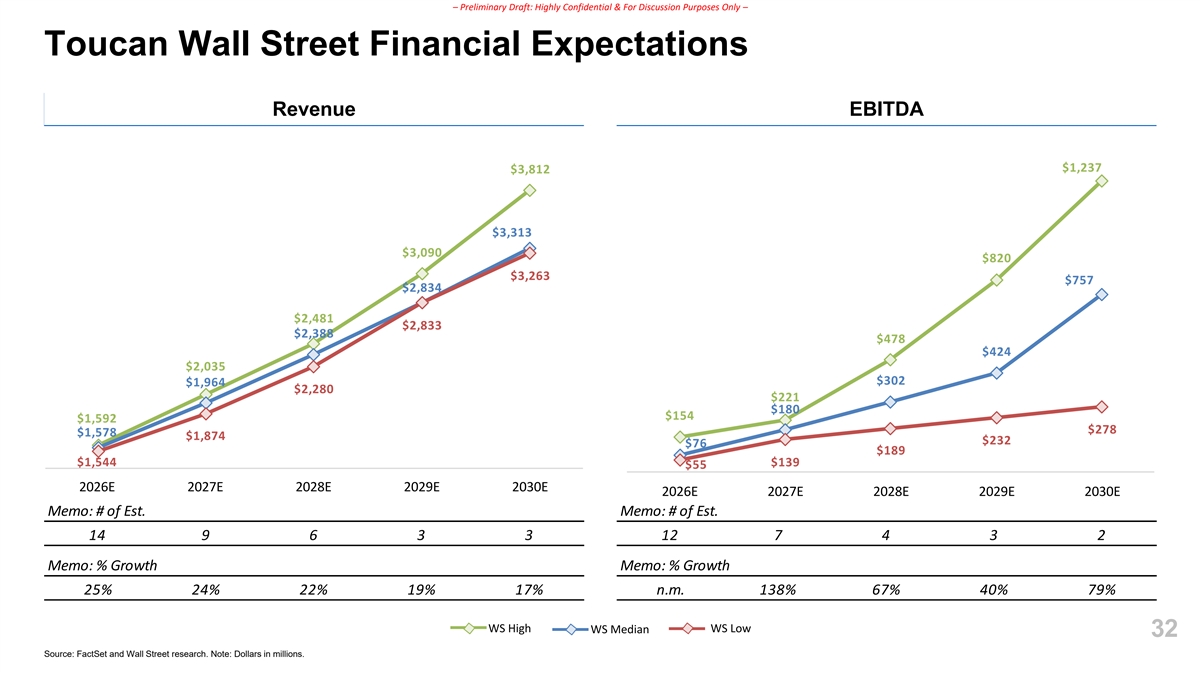
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Toucan Wall Street Financial Expectations Revenue EBITDA $1,237 $3,812 $3,313 $3,090 $820 $3,263 $757 $2,834 $2,481 $2,833 $2,388 $478 $424 $2,035 $302 $1,964 $2,280 $221 $180 $154 $1,592 $278 $1,578 $1,874 $232 $76 $189 $1,544 $139 $55 2026E 2027E 2028E 2029E 2030E 2026E 2027E 2028E 2029E 2030E Memo: # of Est. Memo: # of Est. 14 9 6 3 3 12 7 4 3 2 Memo: % Growth Memo: % Growth 25% 24% 22% 19% 17% n.m. 138% 67% 40% 79% WS High WS Low WS Median 32 Source: FactSet and Wall Street research. Note: Dollars in millions.
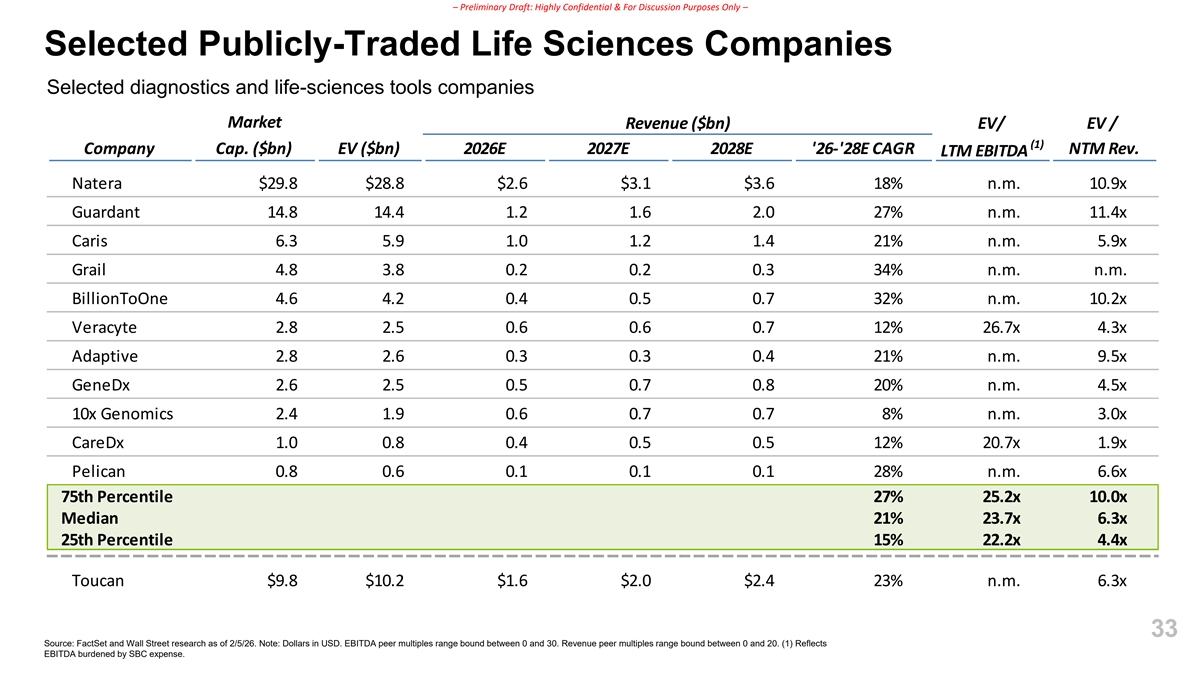
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Selected Publicly-Traded Life Sciences Companies Selected diagnostics and life-sciences tools companies Market Revenue ($bn) EV/ EV / (1) Company Cap. ($bn) EV ($bn) 2026E 2027E 2028E '26-'28E CAGR NTM Rev. LTM EBITDA Natera $29.8 $28.8 $2.6 $3.1 $3.6 18% n.m. 10.9x Guardant 14.8 14.4 1.2 1.6 2.0 27% n.m. 11.4x Caris 6.3 5.9 1.0 1.2 1.4 21% n.m. 5.9x Grail 4.8 3.8 0.2 0.2 0.3 34% n.m. n.m. BillionToOne 4.6 4.2 0.4 0.5 0.7 32% n.m. 10.2x Veracyte 2.8 2.5 0.6 0.6 0.7 12% 26.7x 4.3x Adaptive 2.8 2.6 0.3 0.3 0.4 21% n.m. 9.5x GeneDx 2.6 2.5 0.5 0.7 0.8 20% n.m. 4.5x 10x Genomics 2.4 1.9 0.6 0.7 0.7 8% n.m. 3.0x CareDx 1.0 0.8 0.4 0.5 0.5 12% 20.7x 1.9x Pelican 0.8 0.6 0.1 0.1 0.1 28% n.m. 6.6x 75th Percentile 27% 25.2x 10.0x Median 21% 23.7x 6.3x 25th Percentile 15% 22.2x 4.4x Toucan $9.8 $10.2 $1.6 $2.0 $2.4 23% n.m. 6.3x 33 Source: FactSet and Wall Street research as of 2/5/26. Note: Dollars in USD. EBITDA peer multiples range bound between 0 and 30. Revenue peer multiples range bound between 0 and 20. (1) Reflects EBITDA burdened by SBC expense.
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Appendix 34
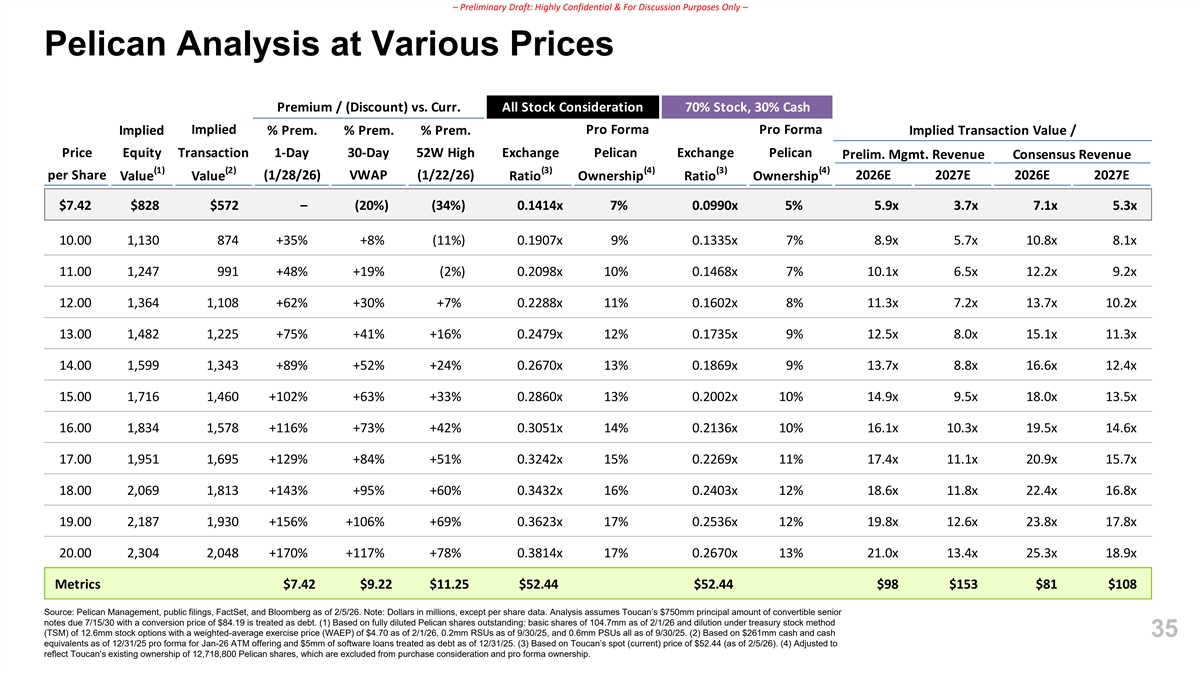
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican Analysis at Various Prices Premium / (Discount) vs. Curr. All Stock Consideration 70% Stock, 30% Cash Implied Pro Forma Pro Forma Implied % Prem. % Prem. % Prem. Implied Transaction Value / Price Equity Transaction 1-Day 30-Day 52W High Exchange Pelican Exchange Pelican Prelim. Mgmt. Revenue Consensus Revenue (1) (2) (3) (4) (3) (4) per Share Value Value (1/28/26) VWAP (1/22/26) Ratio Ownership Ratio Ownership 2026E 2027E 2026E 2027E $7.42 $828 $572 – (20%) (34%) 0.1414x 7% 0.0990x 5% 5.9x 3.7x 7.1x 5.3x 10.00 1,130 874 +35% +8% (11%) 0.1907x 9% 0.1335x 7% 8.9x 5.7x 10.8x 8.1x 11.00 1,247 991 +48% +19% (2%) 0.2098x 10% 0.1468x 7% 10.1x 6.5x 12.2x 9.2x 12.00 1,364 1,108 +62% +30% +7% 0.2288x 11% 0.1602x 8% 11.3x 7.2x 13.7x 10.2x 13.00 1,482 1,225 +75% +41% +16% 0.2479x 12% 0.1735x 9% 12.5x 8.0x 15.1x 11.3x 14.00 1,599 1,343 +89% +52% +24% 0.2670x 13% 0.1869x 9% 13.7x 8.8x 16.6x 12.4x 15.00 1,716 1,460 +102% +63% +33% 0.2860x 13% 0.2002x 10% 14.9x 9.5x 18.0x 13.5x 16.00 1,834 1,578 +116% +73% +42% 0.3051x 14% 0.2136x 10% 16.1x 10.3x 19.5x 14.6x 17.00 1,951 1,695 +129% +84% +51% 0.3242x 15% 0.2269x 11% 17.4x 11.1x 20.9x 15.7x 18.00 2,069 1,813 +143% +95% +60% 0.3432x 16% 0.2403x 12% 18.6x 11.8x 22.4x 16.8x 19.00 2,187 1,930 +156% +106% +69% 0.3623x 17% 0.2536x 12% 19.8x 12.6x 23.8x 17.8x 20.00 2,304 2,048 +170% +117% +78% 0.3814x 17% 0.2670x 13% 21.0x 13.4x 25.3x 18.9x Metrics $7.42 $9.22 $11.25 $52.44 $52.44 $98 $153 $81 $108 Source: Pelican Management, public filings, FactSet, and Bloomberg as of 2/5/26. Note: Dollars in millions, except per share data. Analysis assumes Toucan’s $750mm principal amount of convertible senior notes due 7/15/30 with a conversion price of $84.19 is treated as debt. (1) Based on fully diluted Pelican shares outstanding: basic shares of 104.7mm as of 2/1/26 and dilution under treasury stock method (TSM) of 12.6mm stock options with a weighted-average exercise price (WAEP) of $4.70 as of 2/1/26, 0.2mm RSUs as of 9/30/25, and 0.6mm PSUs all as of 9/30/25. (2) Based on $261mm cash and cash 35 equivalents as of 12/31/25 pro forma for Jan-26 ATM offering and $5mm of software loans treated as debt as of 12/31/25. (3) Based on Toucan’s spot (current) price of $52.44 (as of 2/5/26). (4) Adjusted to reflect Toucan’s existing ownership of 12,718,800 Pelican shares, which are excluded from purchase consideration and pro forma ownership.
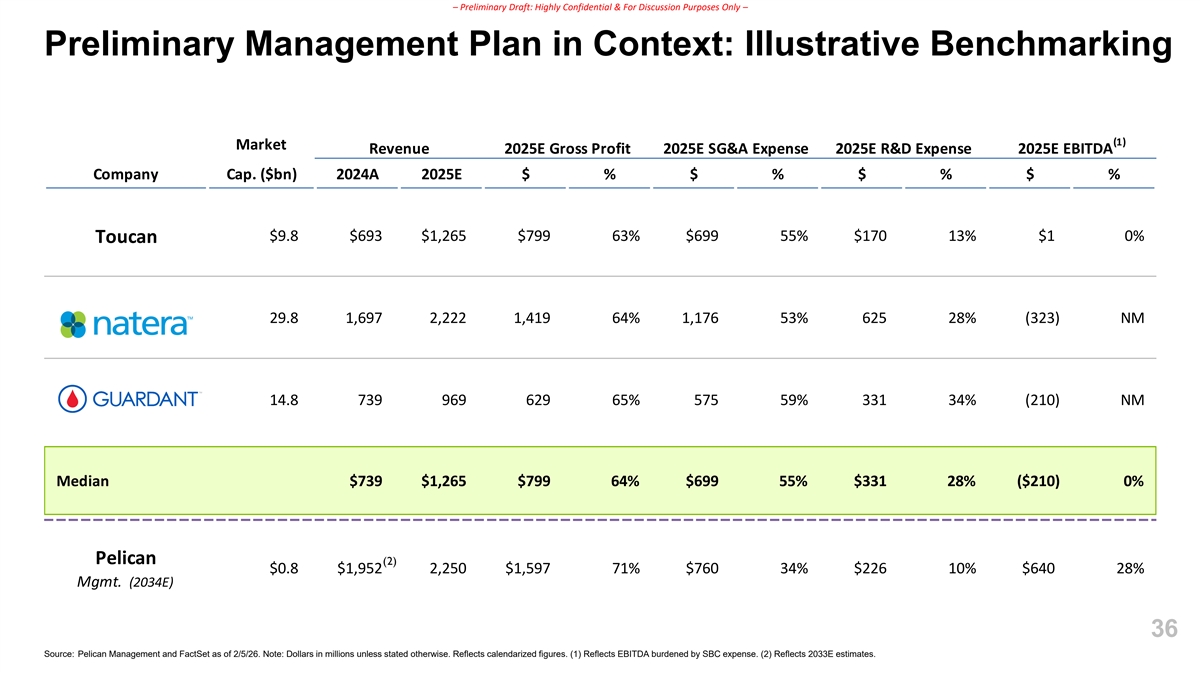
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Management Plan in Context: Illustrative Benchmarking (1) Market Revenue 2025E Gross Profit 2025E SG&A Expense 2025E R&D Expense 2025E EBITDA Company Cap. ($bn) 2024A 2025E $ % $ % $ % $ % $9.8 $693 $1,265 $799 63% $699 55% $170 13% $1 0% Toucan 29.8 1,697 2,222 1,419 64% 1,176 53% 625 28% (323) NM 14.8 739 969 629 65% 575 59% 331 34% (210) NM Median $739 $1,265 $799 64% $699 55% $331 28% ($210) 0% Pelican (2) $0.8 $1,952 2,250 $1,597 71% $760 34% $226 10% $640 28% Mgmt. (2034E) 36 Source: Pelican Management and FactSet as of 2/5/26. Note: Dollars in millions unless stated otherwise. Reflects calendarized figures. (1) Reflects EBITDA burdened by SBC expense. (2) Reflects 2033E estimates.
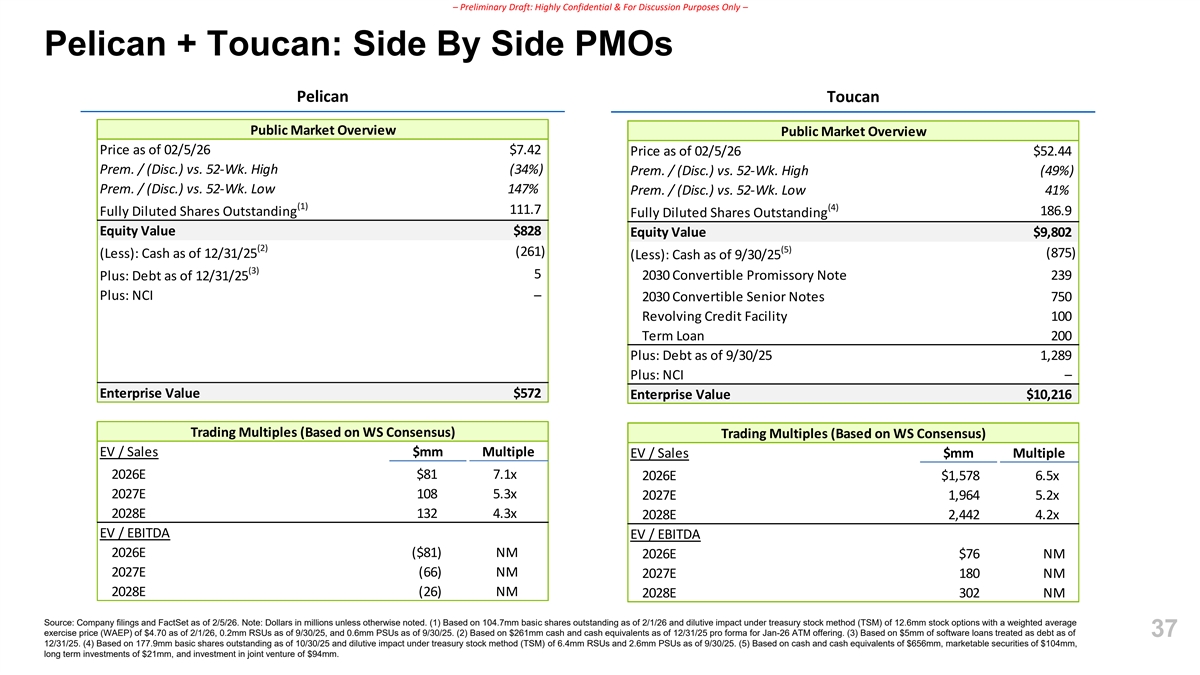
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican + Toucan: Side By Side PMOs Pelican Toucan Public Market Overview Public Market Overview Public Market Overview Price as of 02/5/26 $7.42 Price as of 02/5/26 $52.44 Prem. / (Disc.) vs. 52-Wk. High (34%) Prem. / (Disc.) vs. 52-Wk. High (49%) Prem. / (Disc.) vs. 52-Wk. Low 147% Prem. / (Disc.) vs. 52-Wk. Low 41% (1) (4) 111.7 186.9 Fully Diluted Shares Outstanding Fully Diluted Shares Outstanding Equity Value $828 Equity Value $9,802 (2) (5) (261) (Less): Cash as of 12/31/25 (875) (Less): Cash as of 9/30/25 (3) 5 Plus: Debt as of 12/31/25 2030 Convertible Promissory Note 239 Plus: NCI – 2030 Convertible Senior Notes 750 Revolving Credit Facility 100 Term Loan 200 Plus: Debt as of 9/30/25 1,289 Plus: NCI – Enterprise Value $572 Enterprise Value $10,216 Trading Multiples (Based on WS Consensus) Trading Multiples (Based on WS Consensus) Trading Multiples (Based on WS Consensus) EV / Sales $mm Multiple EV / Sales $mm Multiple 2026E $81 7.1x 2026E $1,578 6.5x 2027E 108 5.3x 2027E 1,964 5.2x 2028E 132 4.3x 2028E 2,442 4.2x EV / EBITDA EV / EBITDA 2026E ($81) NM 2026E $76 NM 2027E (66) NM 2027E 180 NM 2028E (26) NM 2028E 302 NM Source: Company filings and FactSet as of 2/5/26. Note: Dollars in millions unless otherwise noted. (1) Based on 104.7mm basic shares outstanding as of 2/1/26 and dilutive impact under treasury stock method (TSM) of 12.6mm stock options with a weighted average exercise price (WAEP) of $4.70 as of 2/1/26, 0.2mm RSUs as of 9/30/25, and 0.6mm PSUs as of 9/30/25. (2) Based on $261mm cash and cash equivalents as of 12/31/25 pro forma for Jan-26 ATM offering. (3) Based on $5mm of software loans treated as debt as of 37 12/31/25. (4) Based on 177.9mm basic shares outstanding as of 10/30/25 and dilutive impact under treasury stock method (TSM) of 6.4mm RSUs and 2.6mm PSUs as of 9/30/25. (5) Based on cash and cash equivalents of $656mm, marketable securities of $104mm, long term investments of $21mm, and investment in joint venture of $94mm.
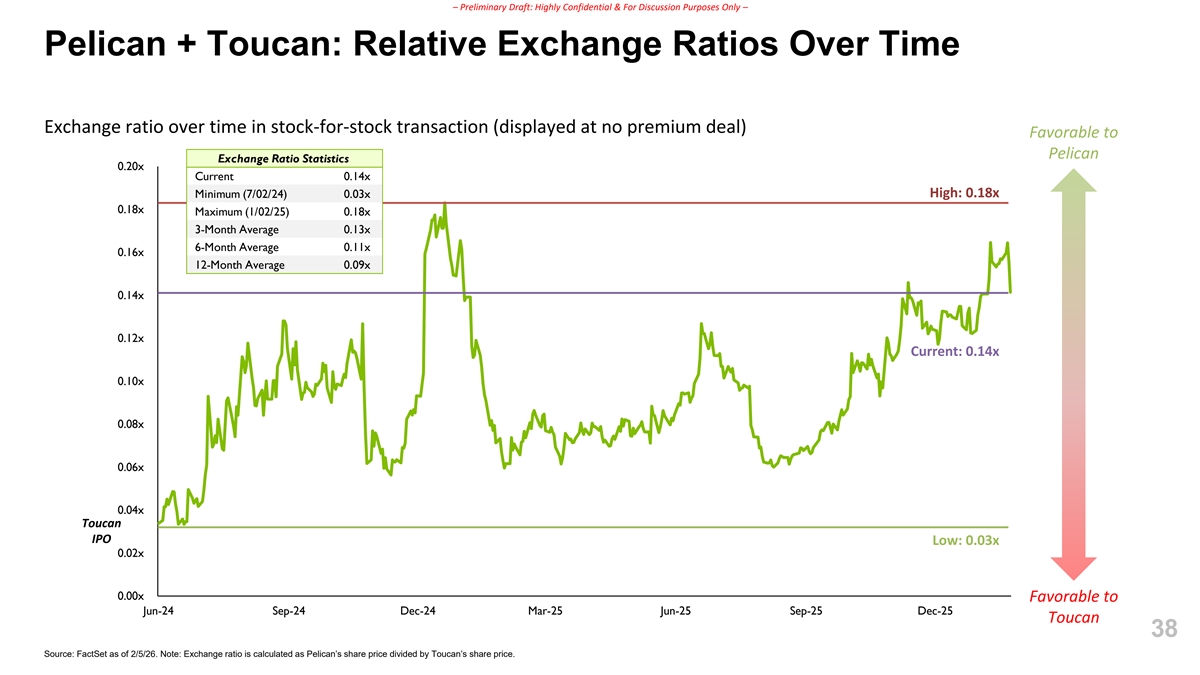
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican + Toucan: Relative Exchange Ratios Over Time Exchange ratio over time in stock-for-stock transaction (displayed at no premium deal) Favorable to Pelican Exchange Ratio Statistics 0.20x Current 0.14x Minimum (7/02/24) 0.03x High: 0.18x 0.18x Maximum (1/02/25) 0.18x 3-Month Average 0.13x 6-Month Average 0.11x 0.16x 12-Month Average 0.09x 0.14x 0.12x Current: 0.14x 0.10x 0.08x 0.06x 0.04x Toucan IPO Low: 0.03x 0.02x 0.00x Favorable to Jun-24 Sep-24 Dec-24 Mar-25 Jun-25 Sep-25 Dec-25 Toucan 38 Source: FactSet as of 2/5/26. Note: Exchange ratio is calculated as Pelican’s share price divided by Toucan’s share price.
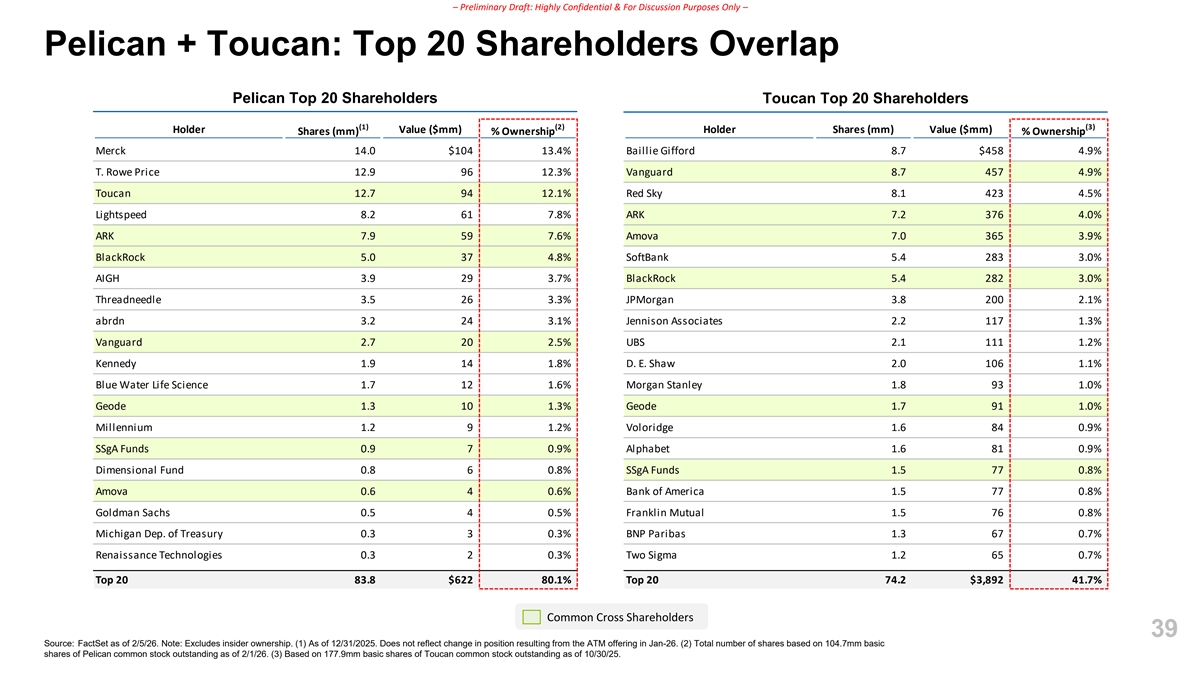
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican + Toucan: Top 20 Shareholders Overlap Pelican Top 20 Shareholders Toucan Top 20 Shareholders (1) (2) (3) Holder Value ($mm) Holder Shares (mm) Value ($mm) Shares (mm) % Ownership % Ownership Merck 14.0 $104 13.4% Baillie Gifford 8.7 $458 4.9% T. Rowe Price 12.9 96 12.3% Vanguard 8.7 457 4.9% Toucan 12.7 94 12.1% Red Sky 8.1 423 4.5% Lightspeed 8.2 61 7.8% ARK 7.2 376 4.0% ARK 7.9 59 7.6% Amova 7.0 365 3.9% BlackRock 5.0 37 4.8% SoftBank 5.4 283 3.0% AIGH 3.9 29 3.7% BlackRock 5.4 282 3.0% Threadneedle 3.5 26 3.3% JPMorgan 3.8 200 2.1% abrdn 3.2 24 3.1% Jennison Associates 2.2 117 1.3% Vanguard 2.7 20 2.5% UBS 2.1 111 1.2% Kennedy 1.9 14 1.8% D. E. Shaw 2.0 106 1.1% Blue Water Life Science 1.7 12 1.6% Morgan Stanley 1.8 93 1.0% Geode 1.3 10 1.3% Geode 1.7 91 1.0% Millennium 1.2 9 1.2% Voloridge 1.6 84 0.9% SSgA Funds 0.9 7 0.9% Alphabet 1.6 81 0.9% Dimensional Fund 0.8 6 0.8% SSgA Funds 1.5 77 0.8% Amova 0.6 4 0.6% Bank of America 1.5 77 0.8% Goldman Sachs 0.5 4 0.5% Franklin Mutual 1.5 76 0.8% Michigan Dep. of Treasury 0.3 3 0.3% BNP Paribas 1.3 67 0.7% Renaissance Technologies 0.3 2 0.3% Two Sigma 1.2 65 0.7% Top 20 83.8 $622 80.1% Top 20 74.2 $3,892 41.7% Common Cross Shareholders 39 Source: FactSet as of 2/5/26. Note: Excludes insider ownership. (1) As of 12/31/2025. Does not reflect change in position resulting from the ATM offering in Jan-26. (2) Total number of shares based on 104.7mm basic shares of Pelican common stock outstanding as of 2/1/26. (3) Based on 177.9mm basic shares of Toucan common stock outstanding as of 10/30/25.
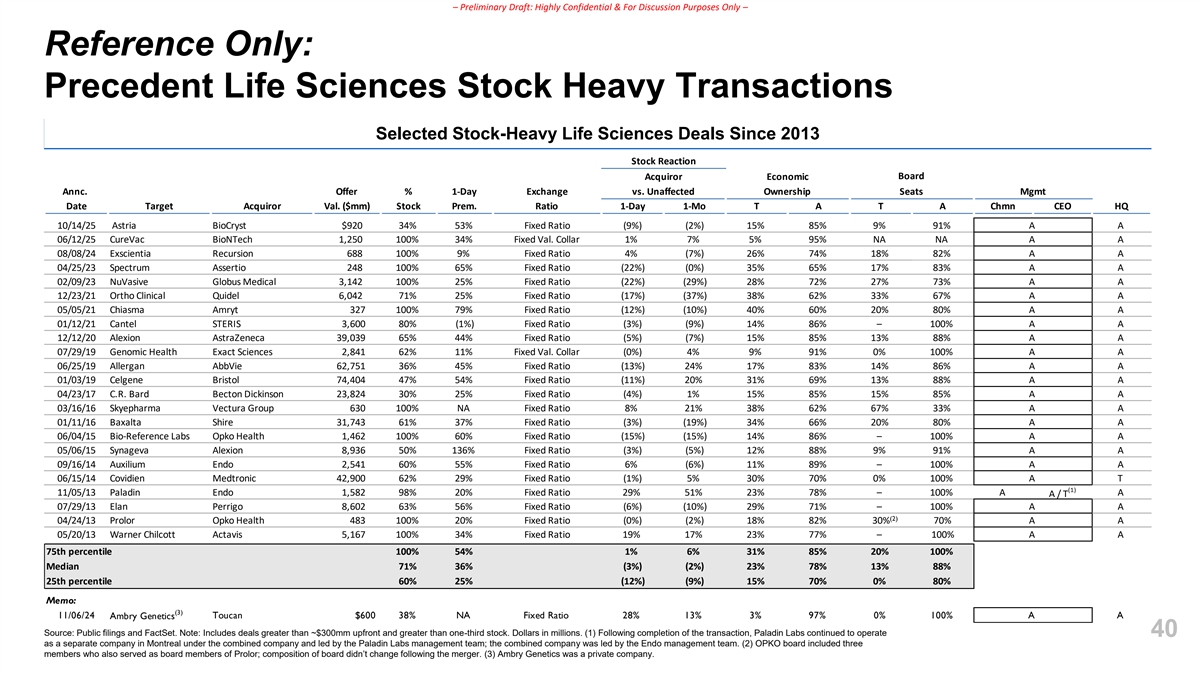
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Reference Only: Precedent Life Sciences Stock Heavy Transactions Selected Stock-Heavy Life Sciences Deals Since 2013 Stock Reaction Acquiror Economic Board ACQUIROR Annc. Offer % 1-Day Exchange vs. Unaffected Ownership Seats Mgmt Date Target Acquiror Val. ($mm) Stock Prem. Ratio 1-Day 1-Mo T A T A Chmn CEO HQ 10/14/25 Astria BioCryst $920 34% 53% Fixed Ratio (9%) (2%) 15% 85% 9% 91% A A 06/12/25 CureVac BioNTech 1,250 100% 34% Fixed Val. Collar 1% 7% 5% 95% NA NA A A 08/08/24 Exscientia Recursion 688 100% 9% Fixed Ratio 4% (7%) 26% 74% 18% 82% A A 04/25/23 Spectrum Assertio 248 100% 65% Fixed Ratio (22%) (0%) 35% 65% 17% 83% A A 02/09/23 NuVasive Globus Medical 3,142 100% 25% Fixed Ratio (22%) (29%) 28% 72% 27% 73% A A 12/23/21 Ortho Clinical Quidel 6,042 71% 25% Fixed Ratio (17%) (37%) 38% 62% 33% 67% A A 05/05/21 Chiasma Amryt 327 100% 79% Fixed Ratio (12%) (10%) 40% 60% 20% 80% A A 01/12/21 Cantel STERIS 3,600 80% (1%) Fixed Ratio (3%) (9%) 14% 86% – 100% A A 12/12/20 Alexion AstraZeneca 39,039 65% 44% Fixed Ratio (5%) (7%) 15% 85% 13% 88% A A 07/29/19 Genomic Health Exact Sciences 2,841 62% 11% Fixed Val. Collar (0%) 4% 9% 91% 0% 100% A A 06/25/19 Allergan AbbVie 62,751 36% 45% Fixed Ratio (13%) 24% 17% 83% 14% 86% A A 01/03/19 Celgene Bristol 74,404 47% 54% Fixed Ratio (11%) 20% 31% 69% 13% 88% A A 04/23/17 C.R. Bard Becton Dickinson 23,824 30% 25% Fixed Ratio (4%) 1% 15% 85% 15% 85% A A 03/16/16 Skyepharma Vectura Group 630 100% NA Fixed Ratio 8% 21% 38% 62% 67% 33% A A 01/11/16 Baxalta Shire 31,743 61% 37% Fixed Ratio (3%) (19%) 34% 66% 20% 80% A A 06/04/15 Bio-Reference Labs Opko Health 1,462 100% 60% Fixed Ratio (15%) (15%) 14% 86% – 100% A A 05/06/15 Synageva Alexion 8,936 50% 136% Fixed Ratio (3%) (5%) 12% 88% 9% 91% A A 09/16/14 Auxilium Endo 2,541 60% 55% Fixed Ratio 6% (6%) 11% 89% – 100% A A 06/15/14 Covidien Medtronic 42,900 62% 29% Fixed Ratio (1%) 5% 30% 70% 0% 100% A T (1) 11/05/13 Paladin Endo 1,582 98% 20% Fixed Ratio 29% 51% 23% 78% – 100% A A A / T 07/29/13 Elan Perrigo 8,602 63% 56% Fixed Ratio (6%) (10%) 29% 71% – 100% A A (2) 04/24/13 Prolor Opko Health 483 100% 20% Fixed Ratio (0%) (2%) 18% 82% 30% 70% A A 05/20/13 Warner Chilcott Actavis 5,167 100% 34% Fixed Ratio 19% 17% 23% 77% – 100% A A 75th percentile 100% 54% 1% 6% 31% 85% 20% 100% Median 71% 36% (3%) (2%) 23% 78% 13% 88% 25th percentile 60% 25% (12%) (9%) 15% 70% 0% 80% Memo: (3) 11/06/24 Ambry Genetics Toucan $600 38% NA Fixed Ratio 28% 13% 3% 97% 0% 100% A A Source: Public filings and FactSet. Note: Includes deals greater than ~$300mm upfront and greater than one-third stock. Dollars in millions. (1) Following completion of the transaction, Paladin Labs continued to operate 40 as a separate company in Montreal under the combined company and led by the Paladin Labs management team; the combined company was led by the Endo management team. (2) OPKO board included three members who also served as board members of Prolor; composition of board didn’t change following the merger. (3) Ambry Genetics was a private company.
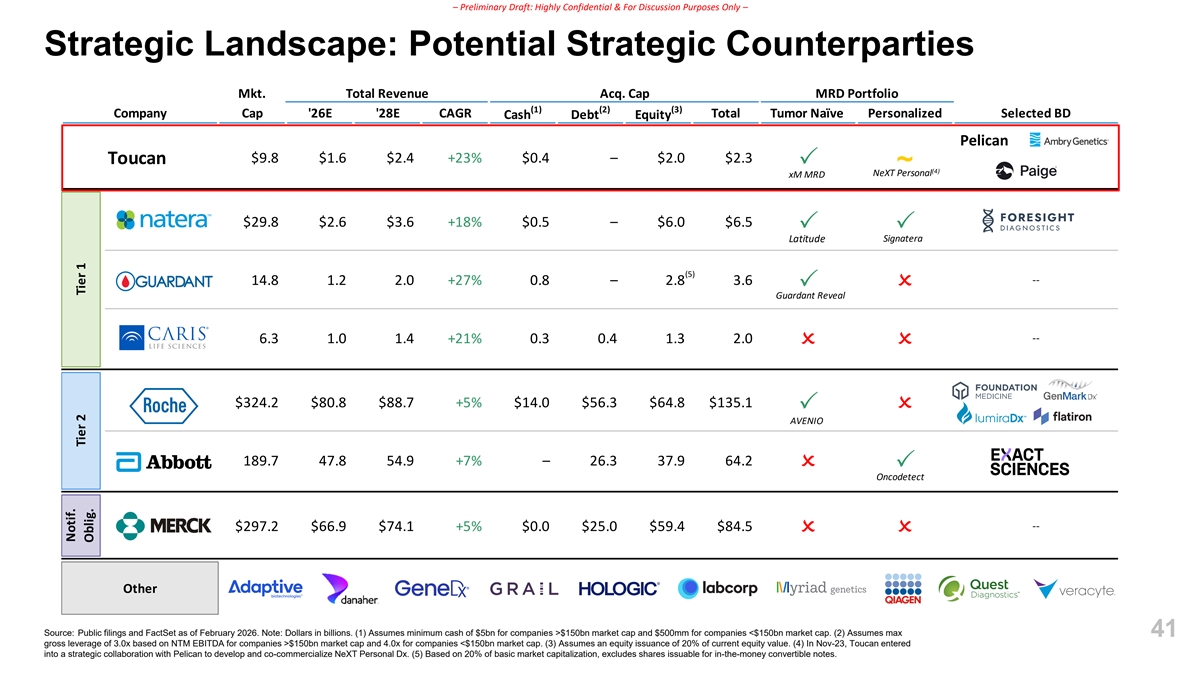
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Strategic Landscape: Potential Strategic Counterparties Mkt. Total Revenue Acq. Cap MRD Portfolio (1) (2) (3) Company Cap '26E '28E CAGR Total Tumor Naïve Personalized Selected BD Cash Debt Equity Pelican $9.8 $1.6 $2.4 +23% $0.4 – $2.0 $2.3 Toucan ~ P (4) NeXT Personal xM MRD $29.8 $2.6 $3.6 +18% $0.5 – $6.0 $6.5 PP Latitude Signatera (5) -- 14.8 1.2 2.0 +27% 0.8 – 2.8 3.6 PO Guardant Reveal -- 6.3 1.0 1.4 +21% 0.3 0.4 1.3 2.0 OO $324.2 $80.8 $88.7 +5% $14.0 $56.3 $64.8 $135.1 PO AVENIO 189.7 47.8 54.9 +7% – 26.3 37.9 64.2 OP Oncodetect -- $297.2 $66.9 $74.1 +5% $0.0 $25.0 $59.4 $84.5 OO Other Source: Public filings and FactSet as of February 2026. Note: Dollars in billions. (1) Assumes minimum cash of $5bn for companies >$150bn market cap and $500mm for companies <$150bn market cap. (2) Assumes max 41 gross leverage of 3.0x based on NTM EBITDA for companies >$150bn market cap and 4.0x for companies <$150bn market cap. (3) Assumes an equity issuance of 20% of current equity value. (4) In Nov-23, Toucan entered into a strategic collaboration with Pelican to develop and co-commercialize NeXT Personal Dx. (5) Based on 20% of basic market capitalization, excludes shares issuable for in-the-money convertible notes. Notif. Tier 2 Tier 1 Oblig.
Exhibit (c)(6)
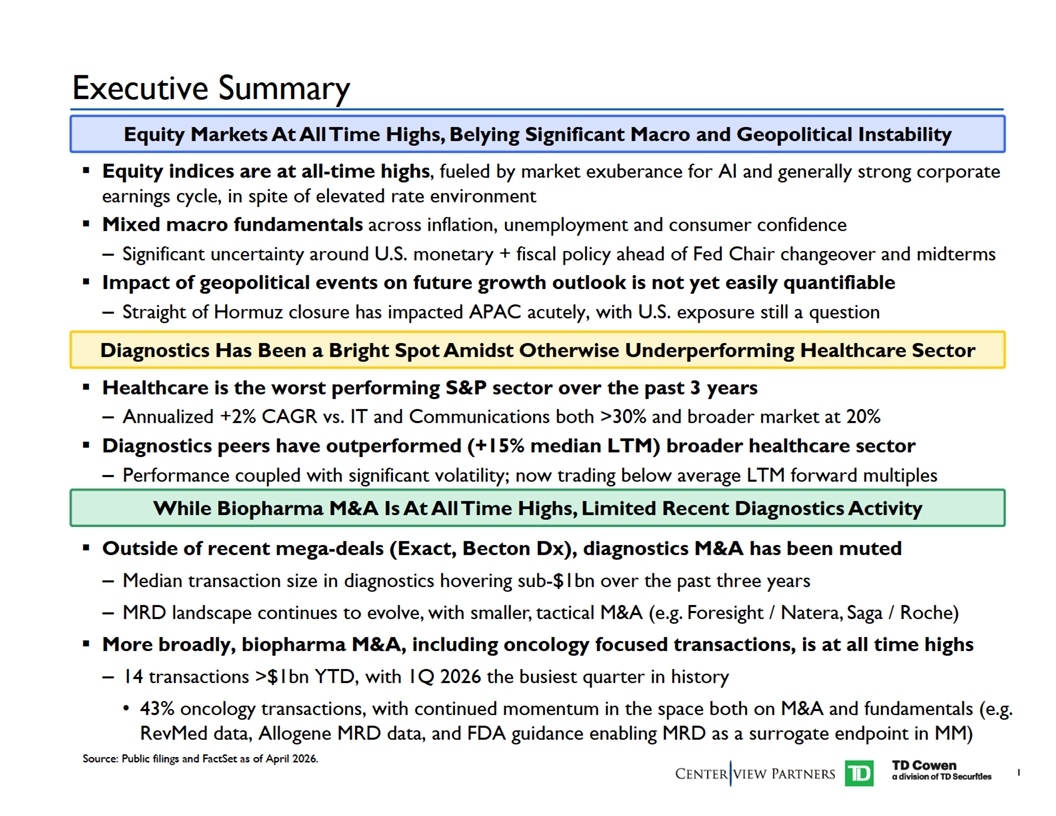
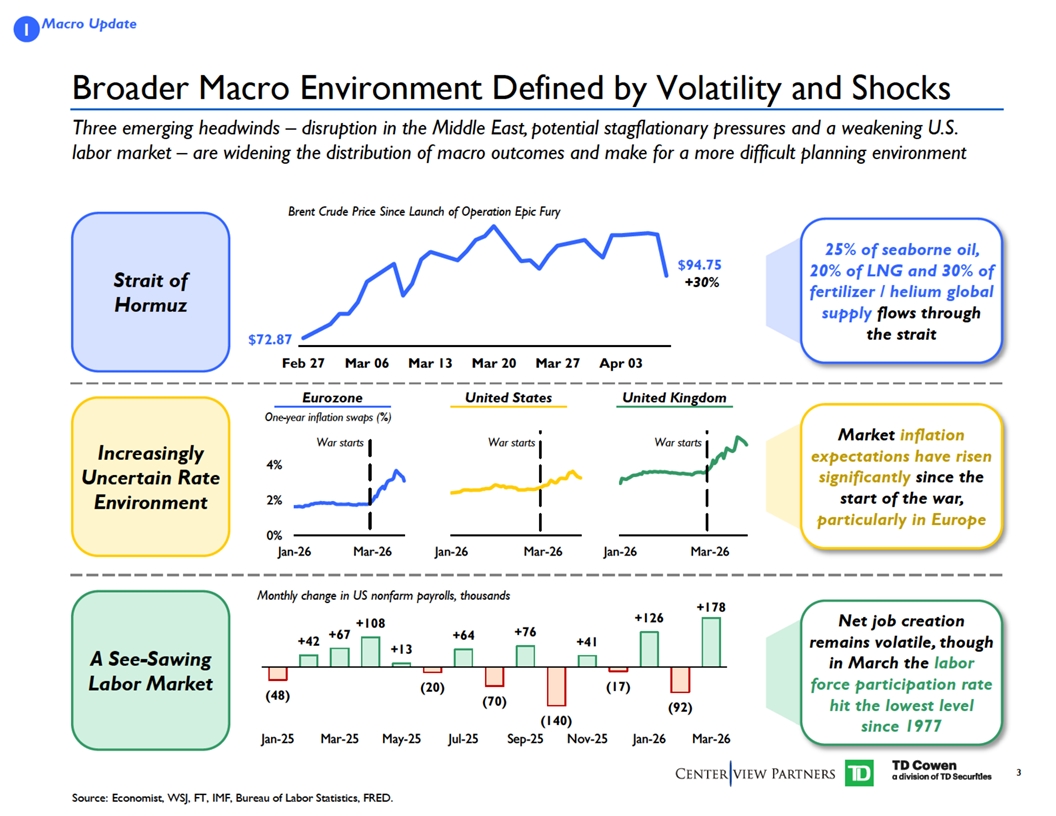
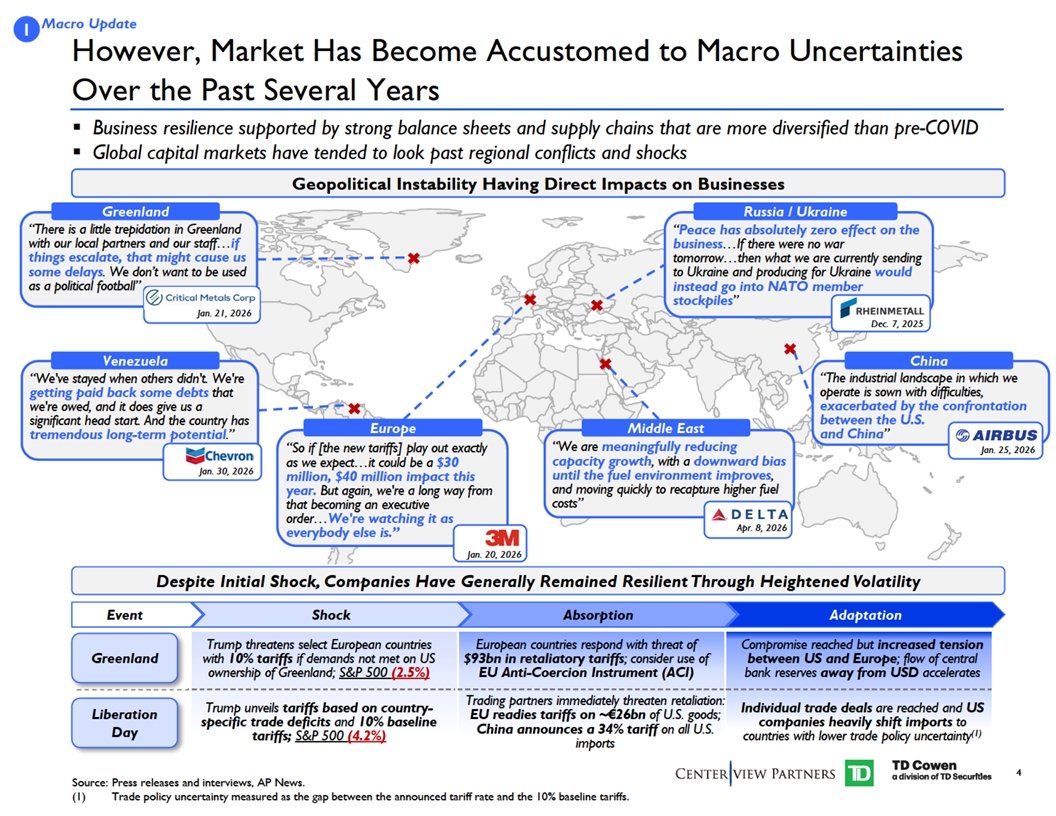
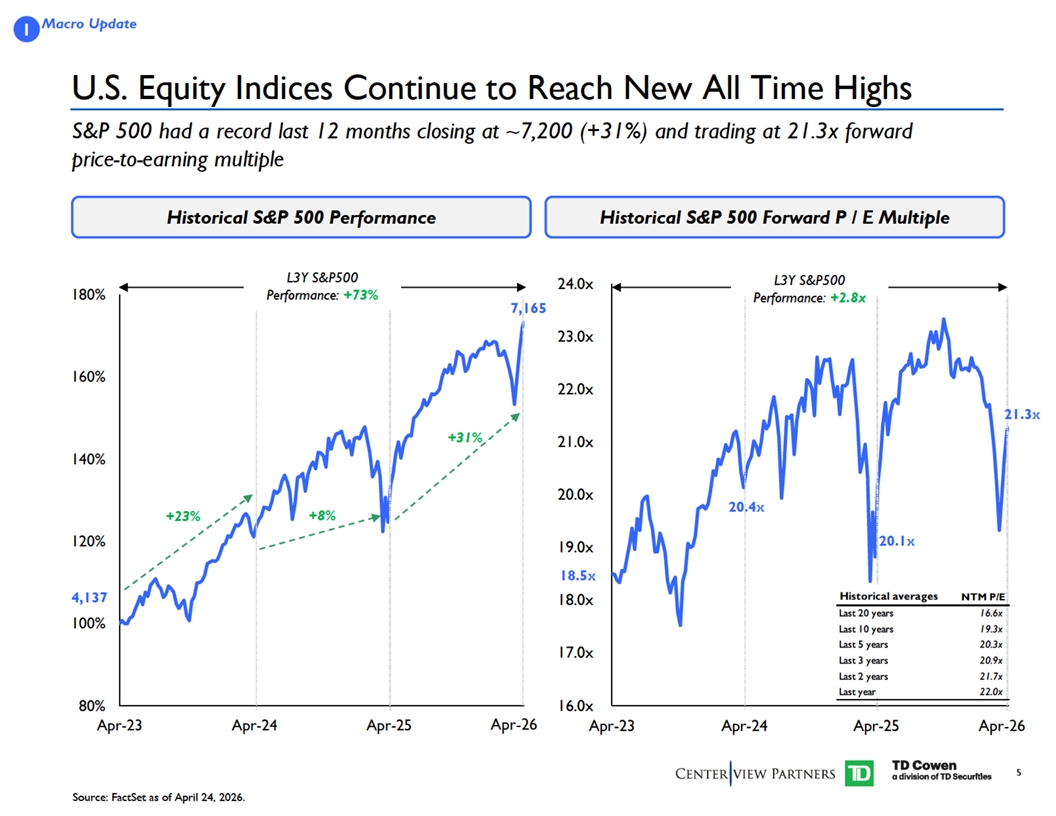
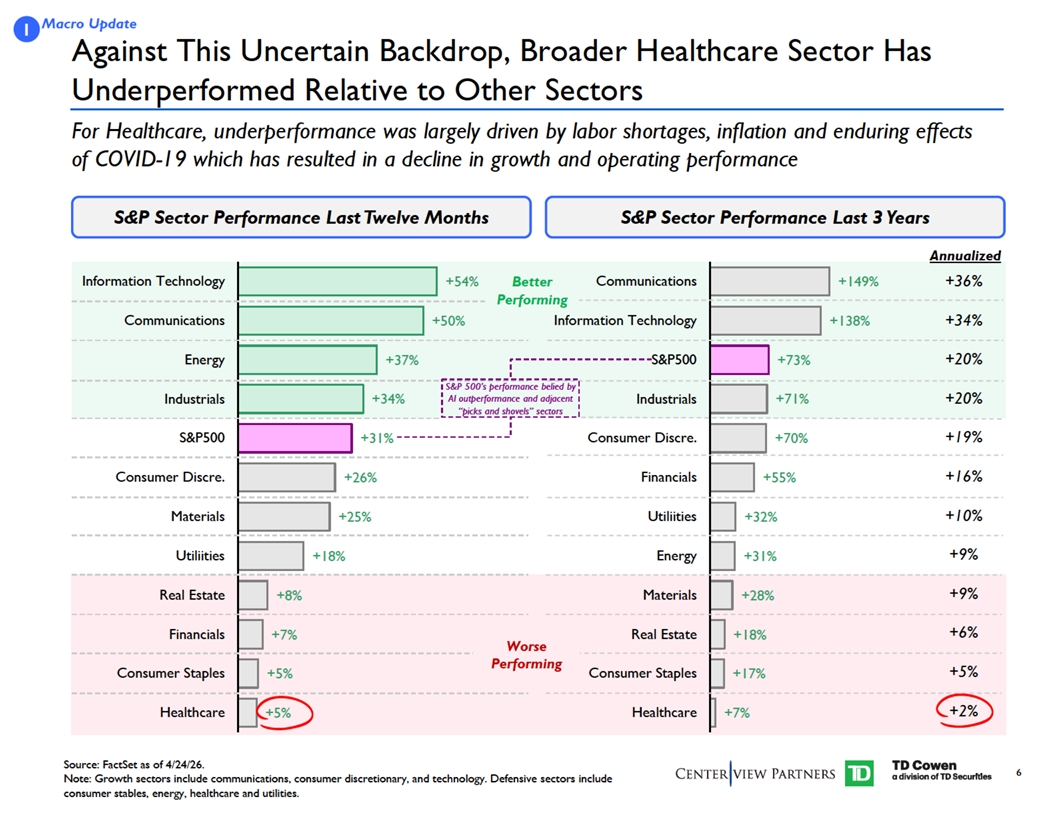
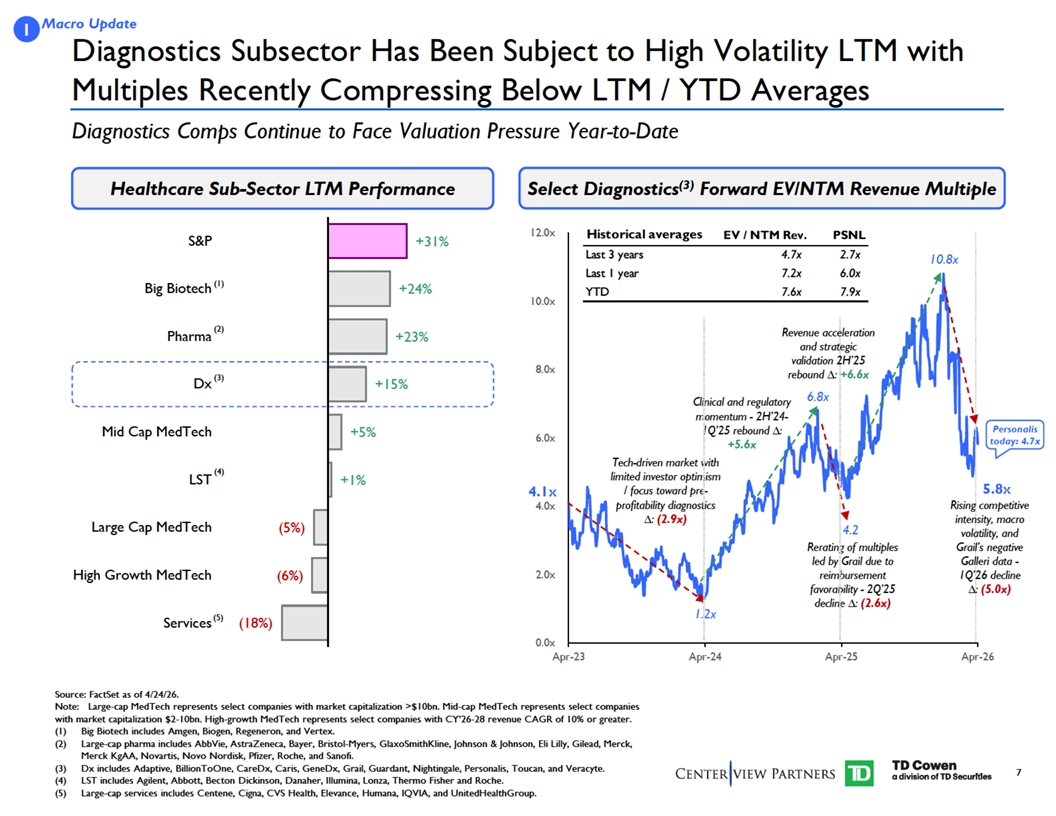
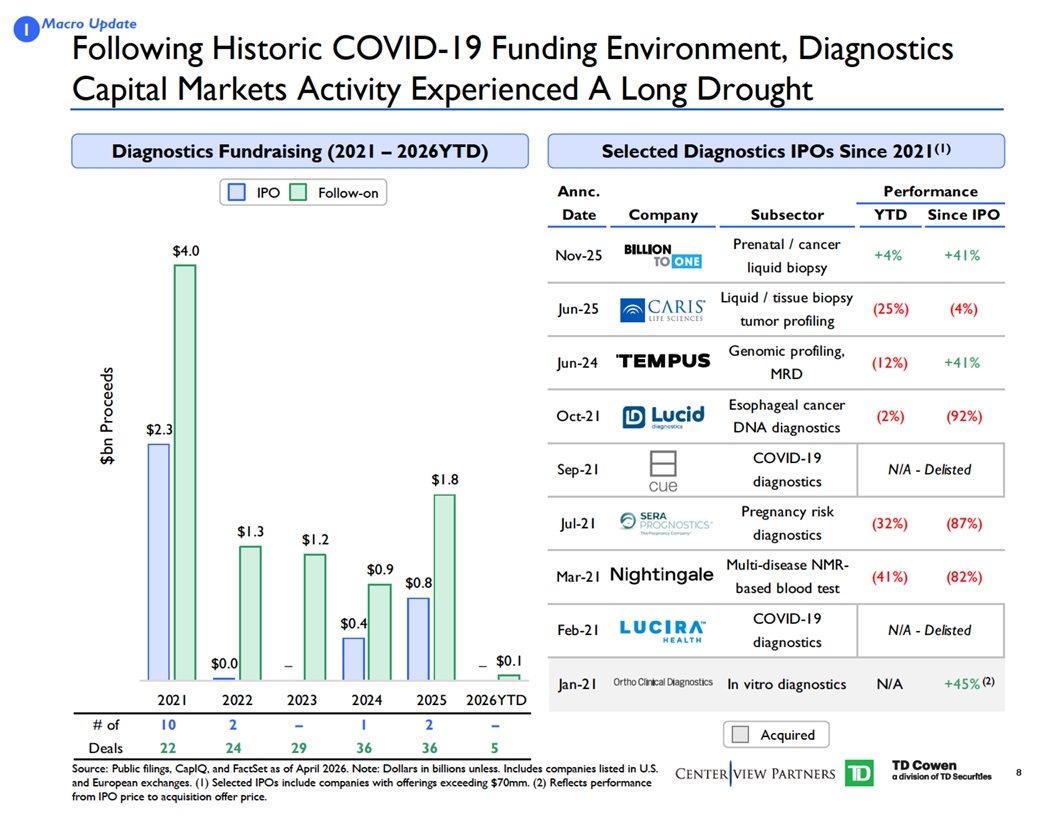
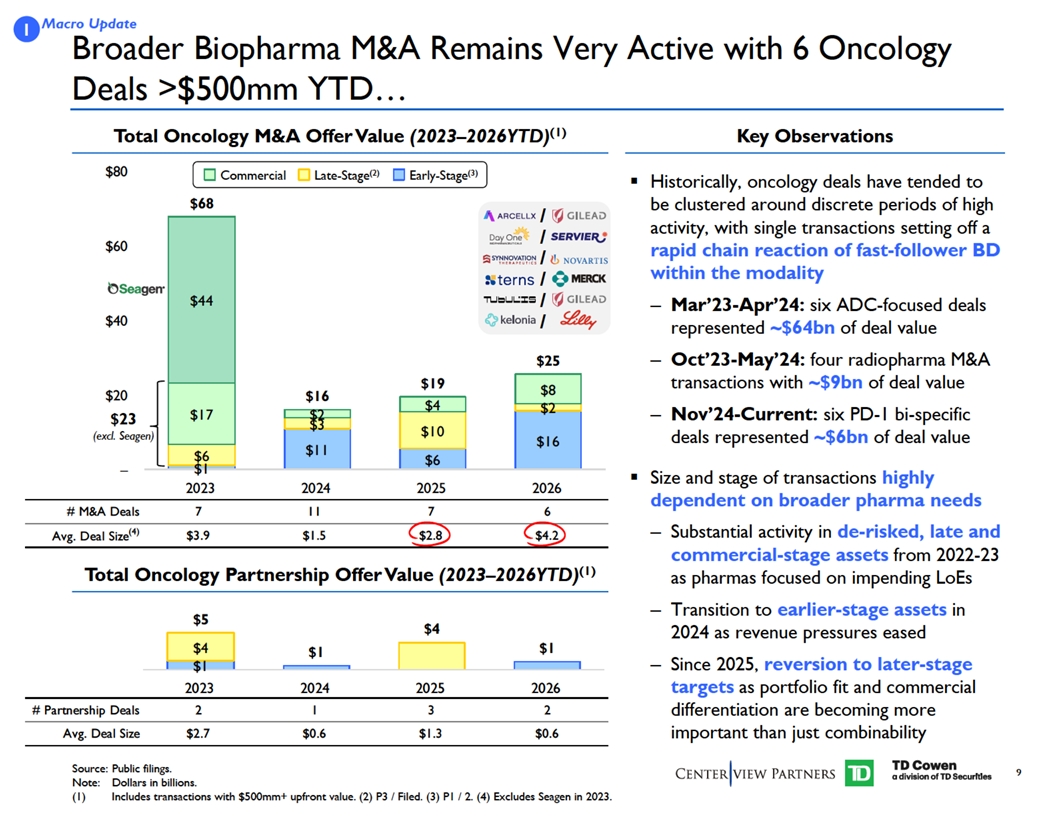
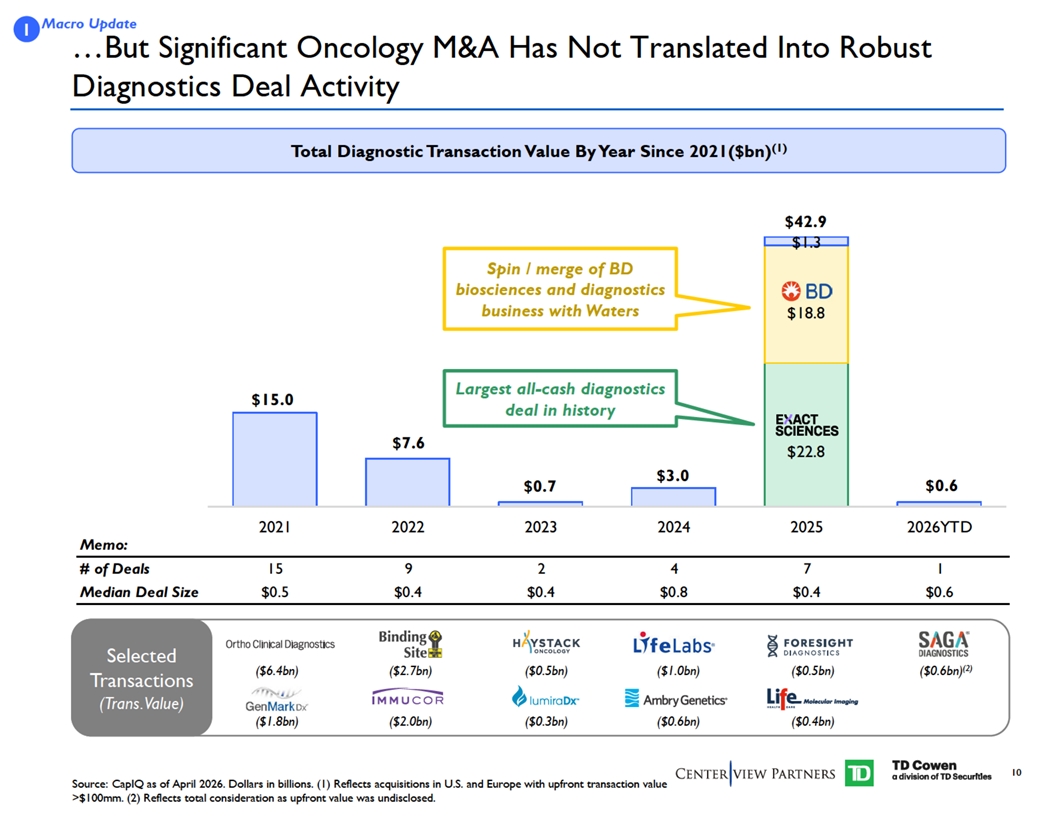
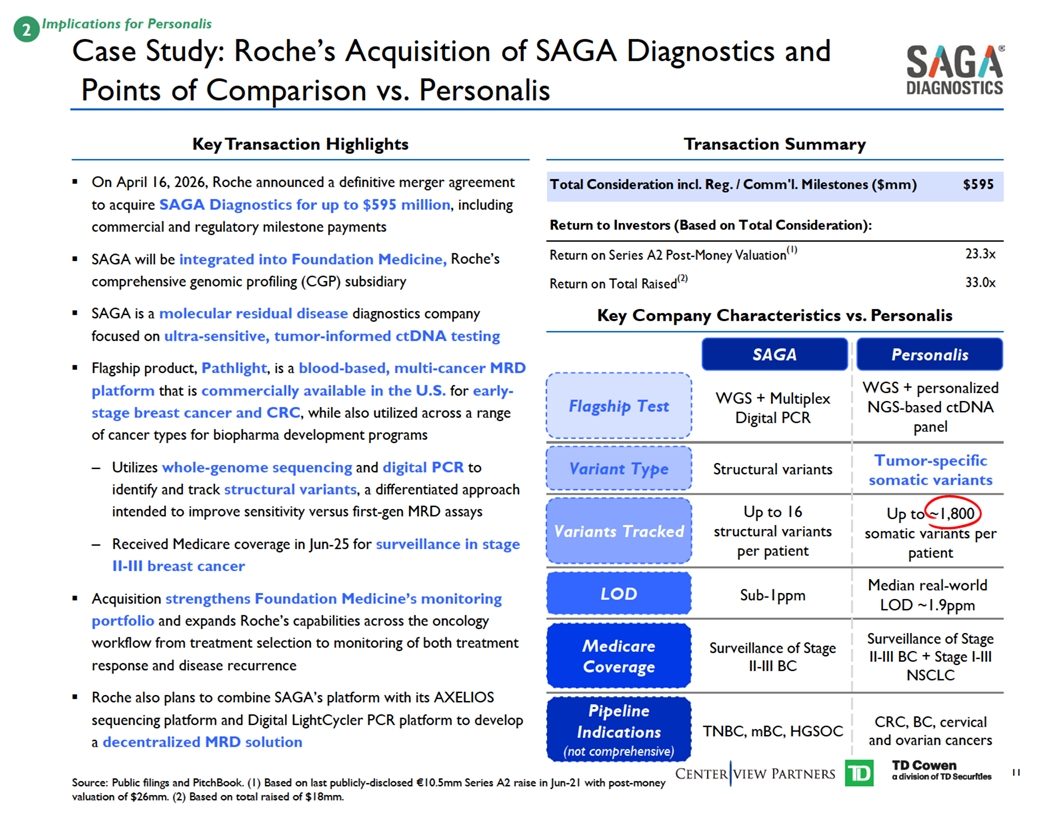
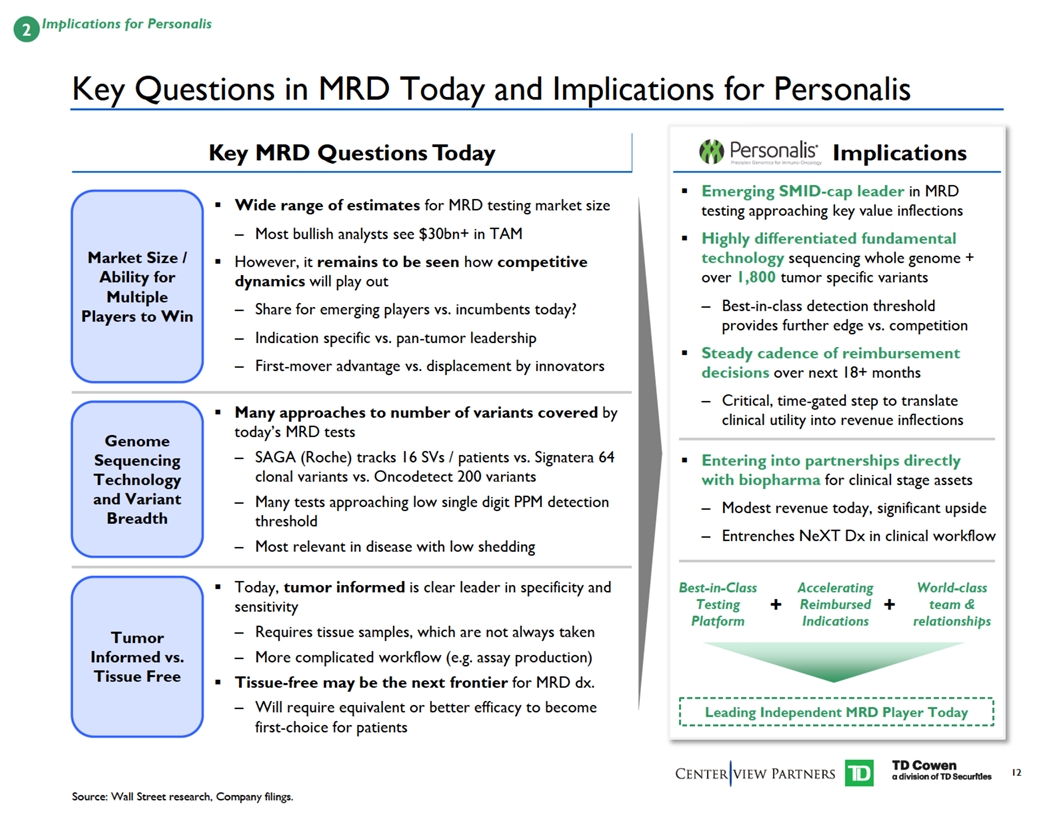
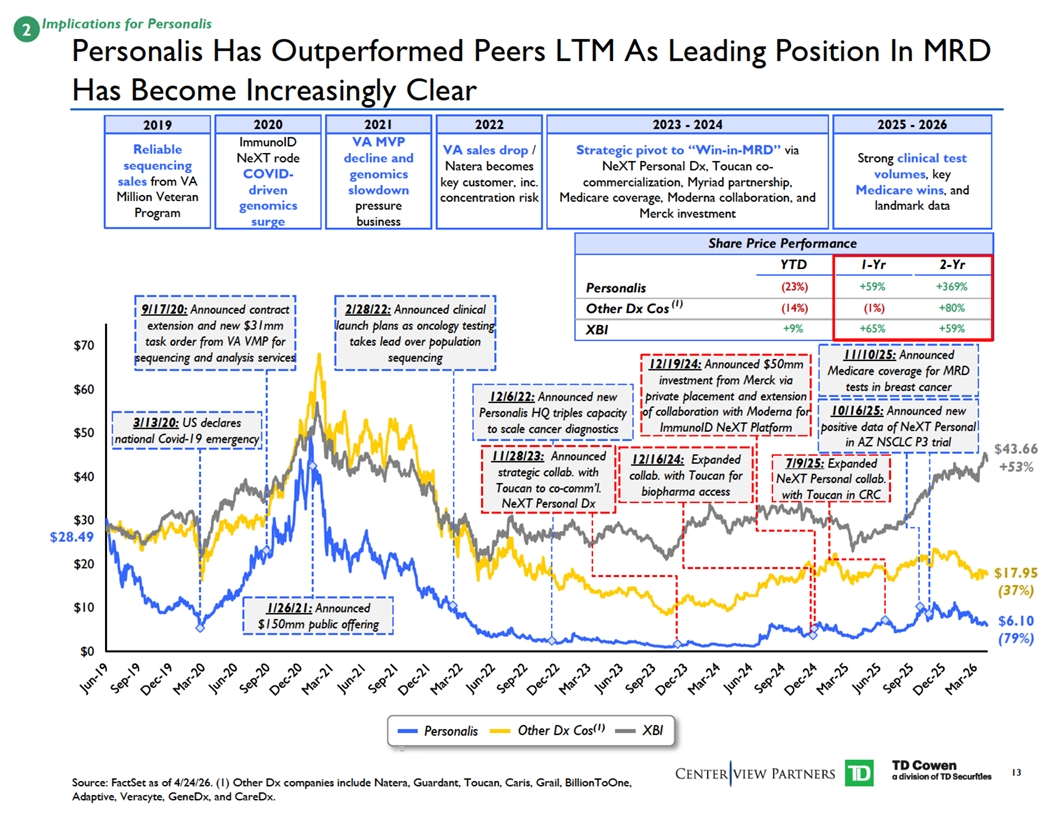
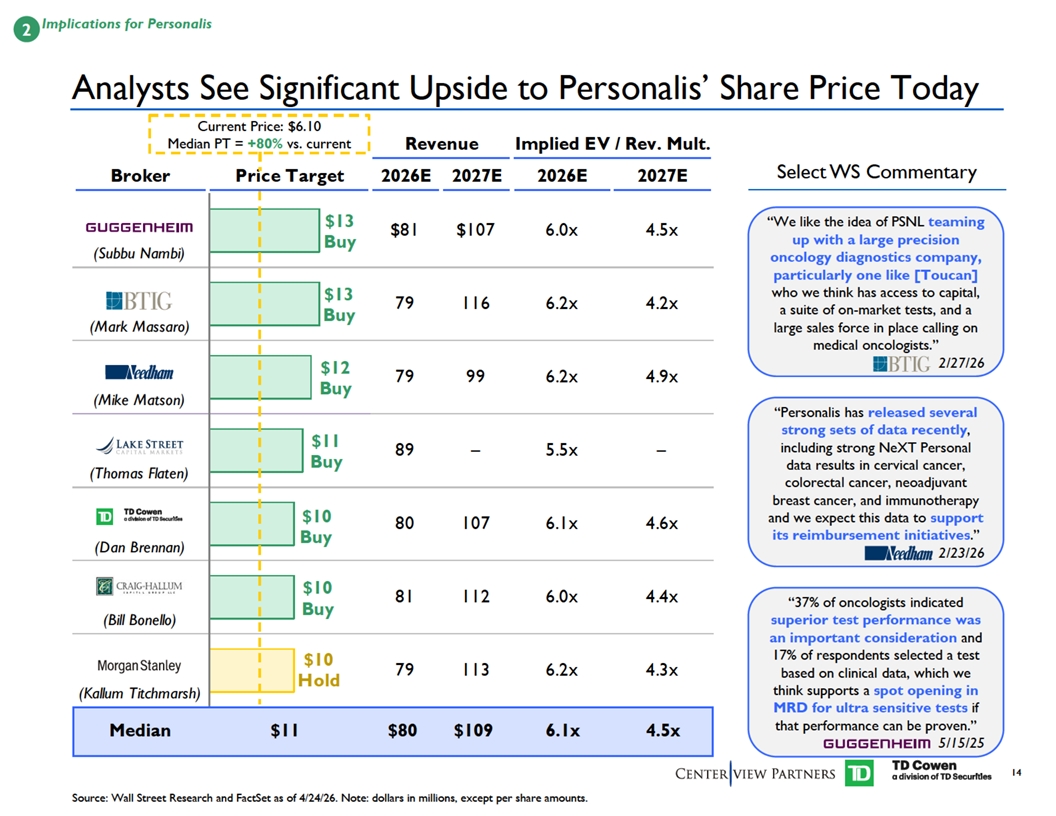
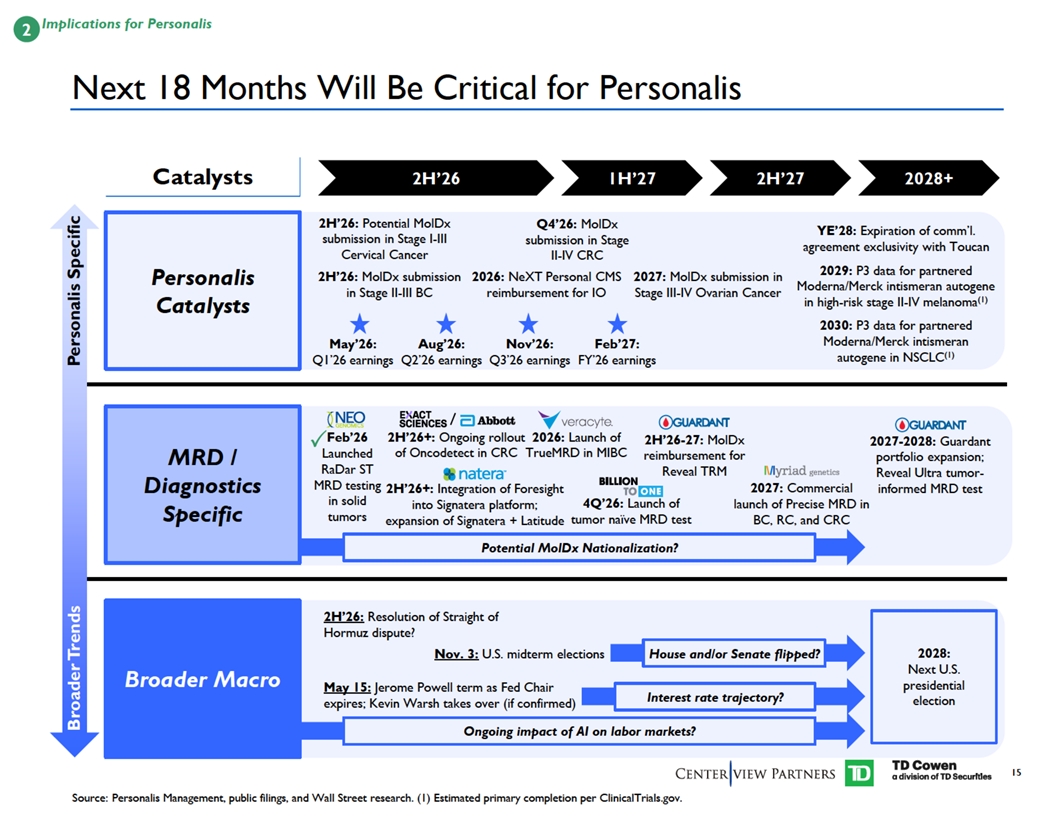
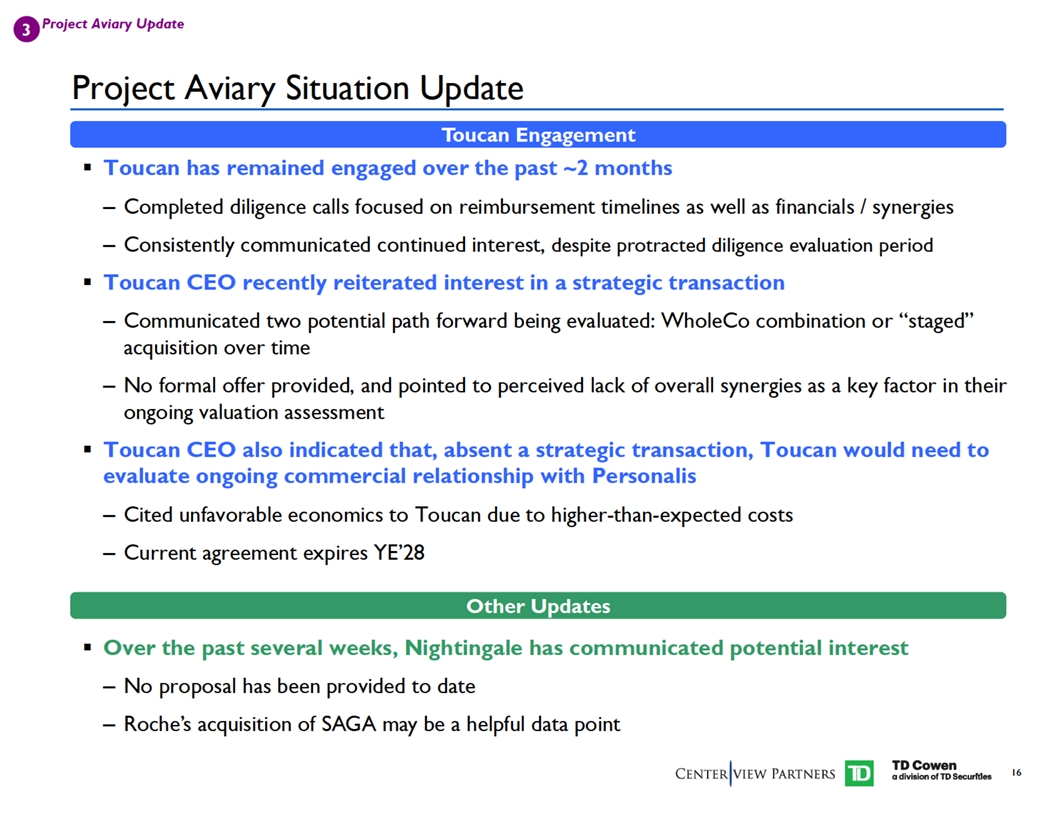
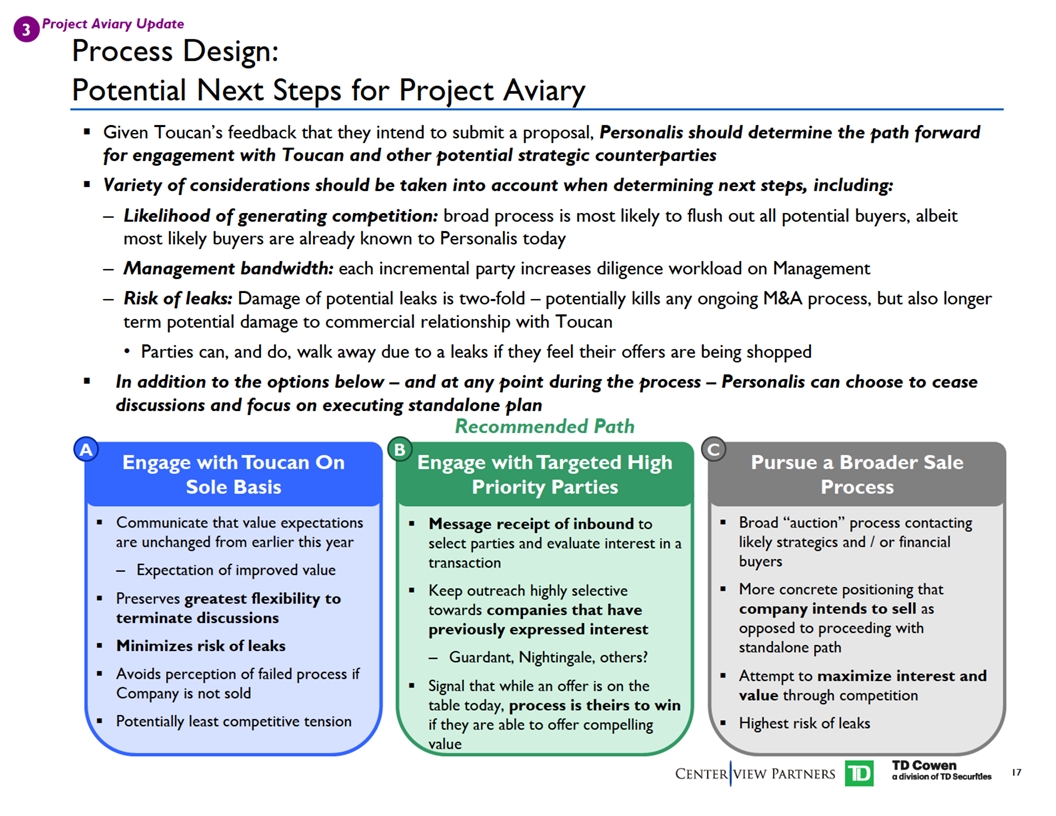
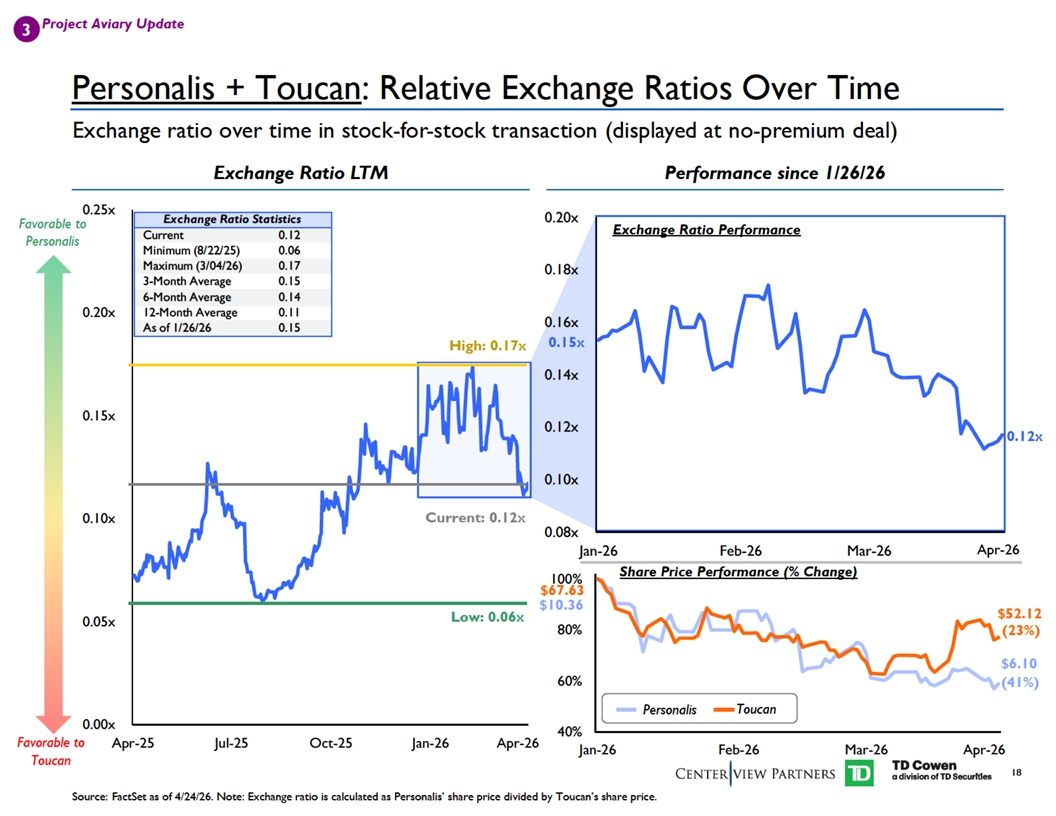
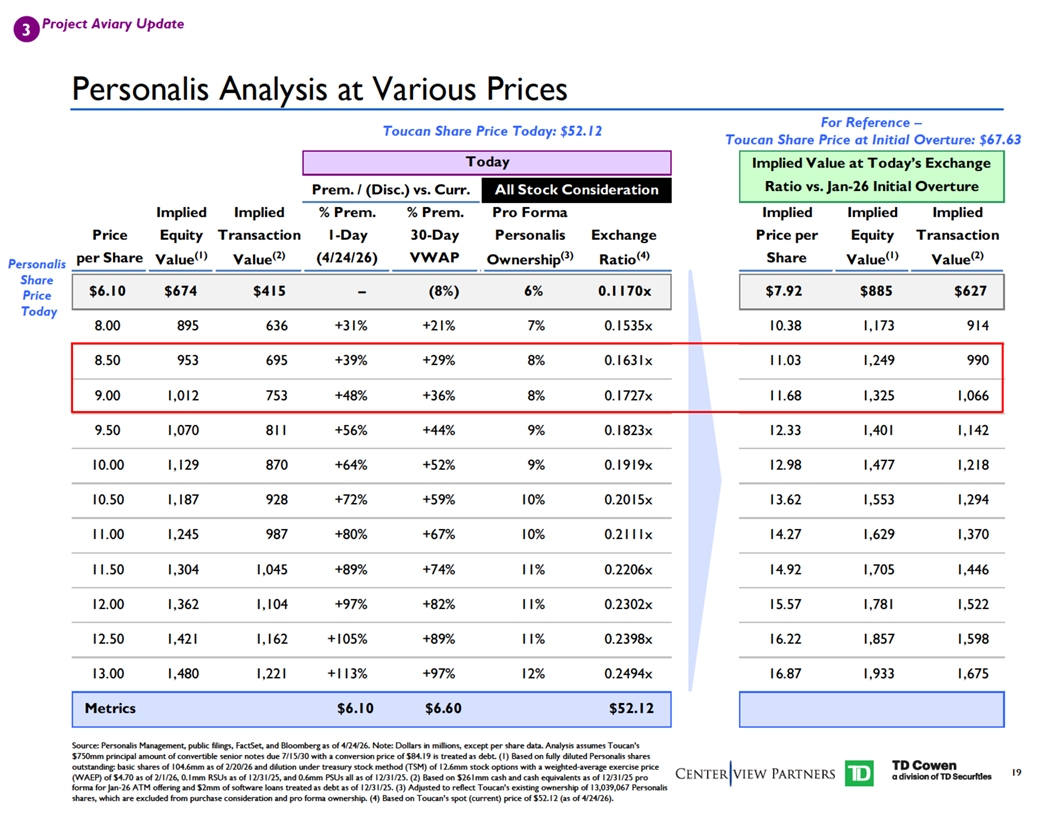
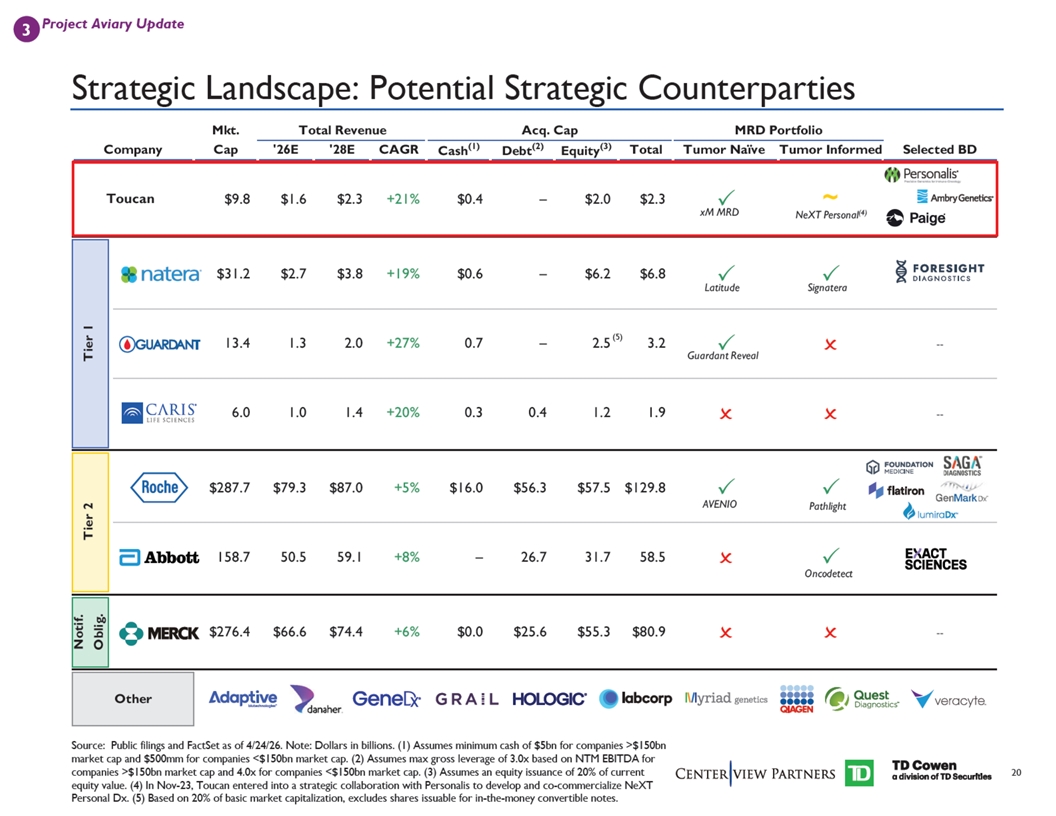
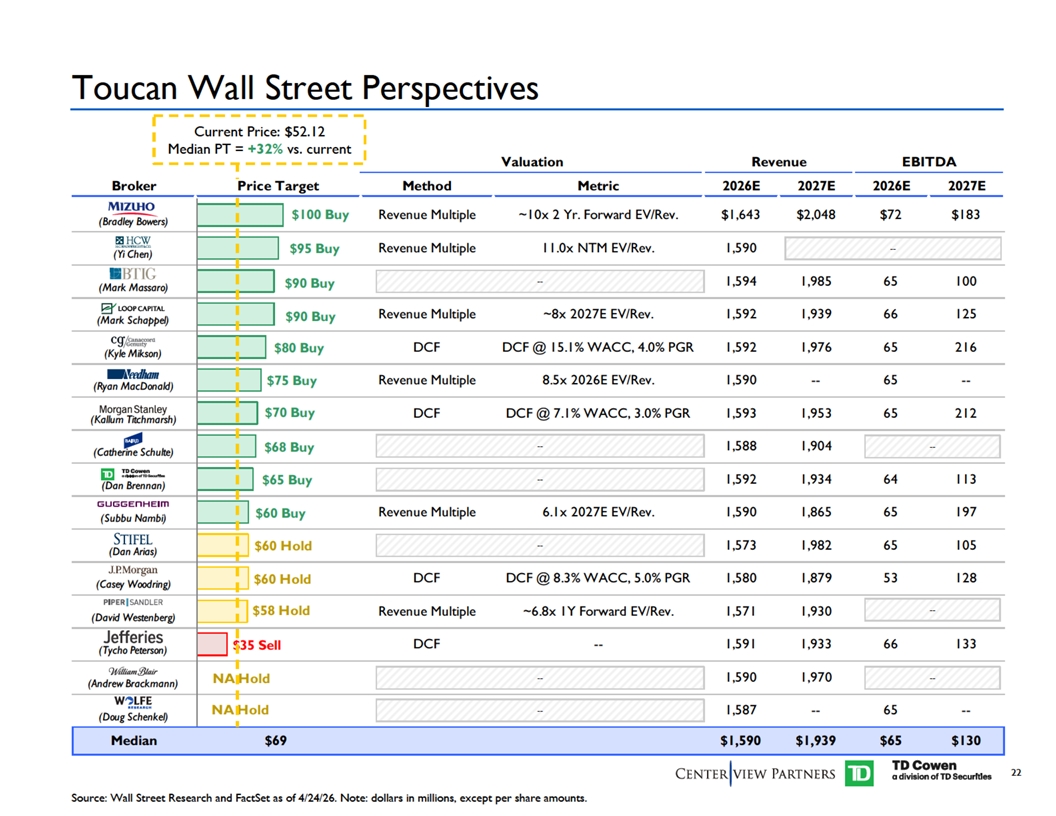
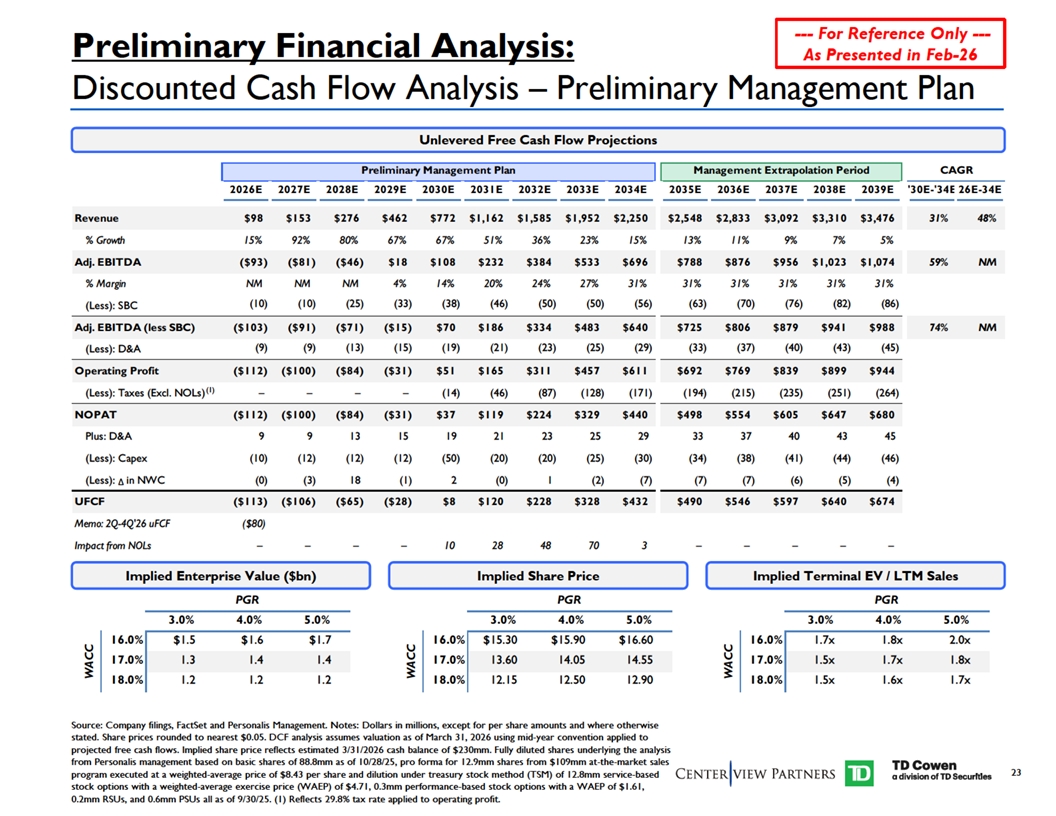
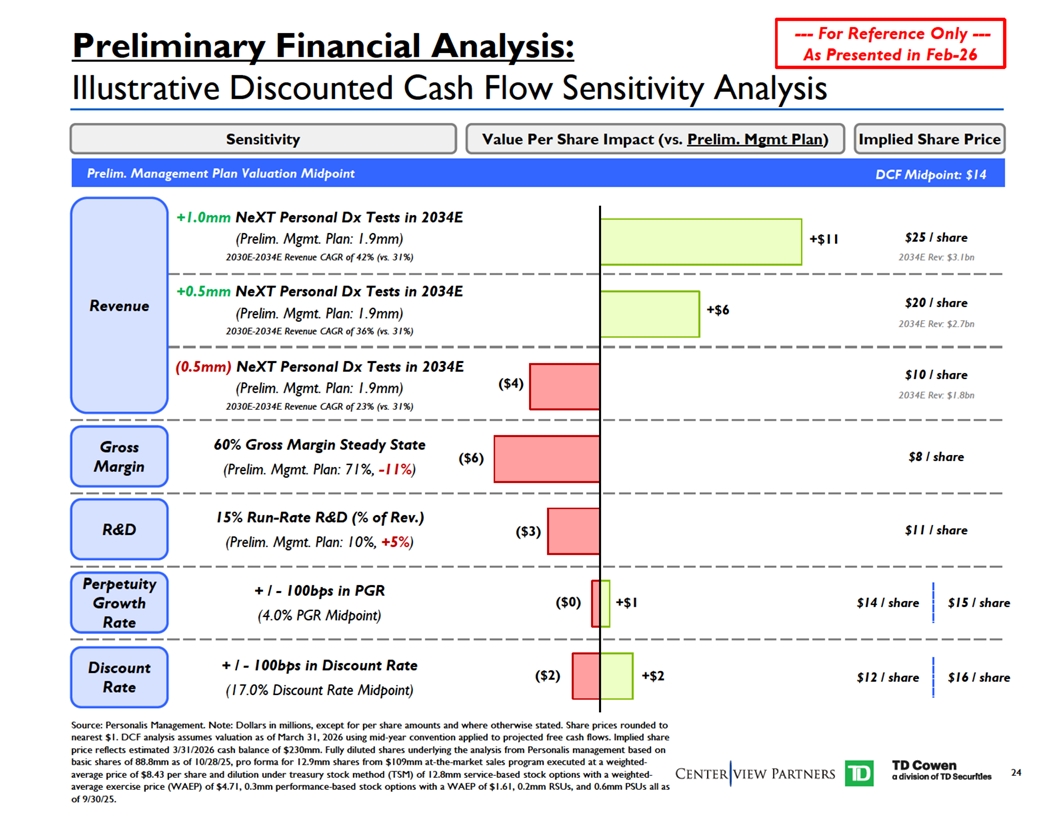
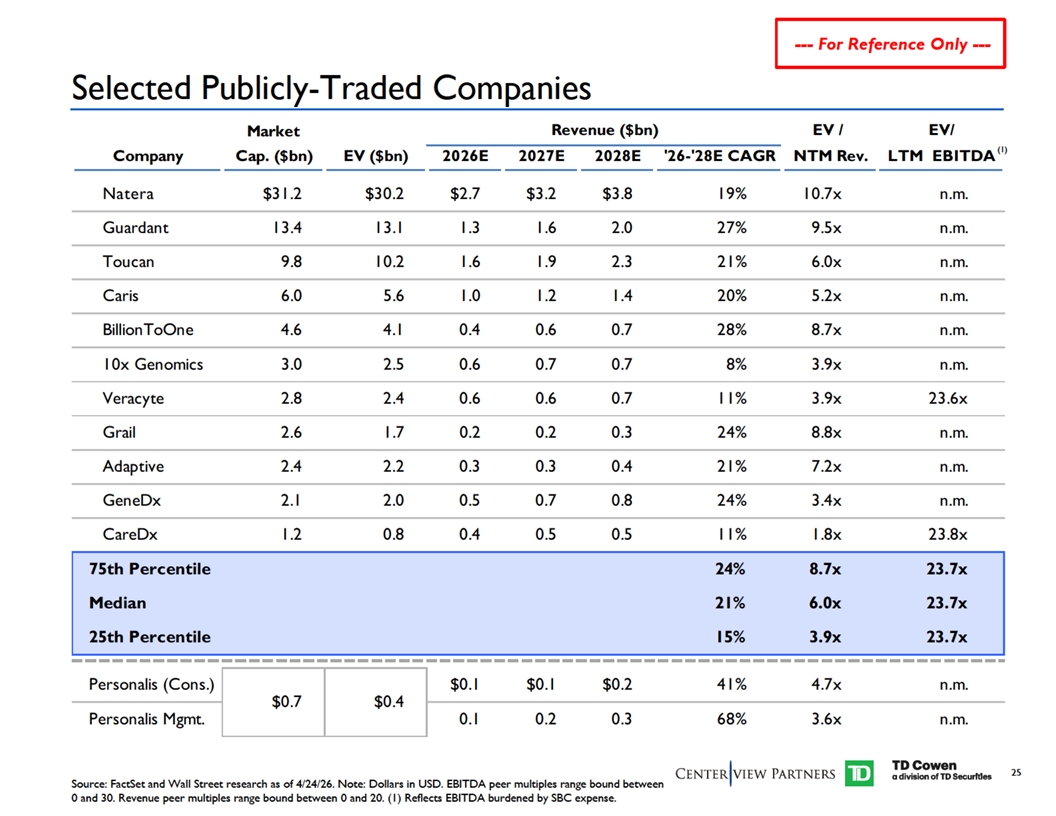
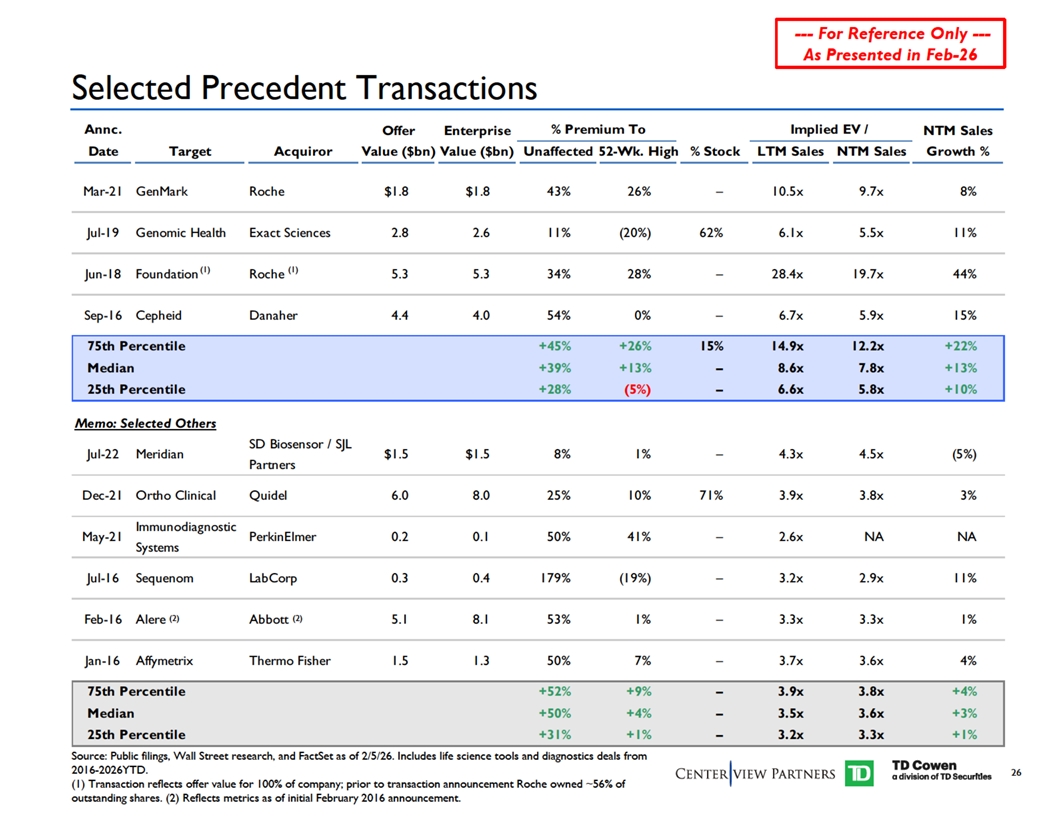
Exhibit (c)(7) Project Aviary Presentation to the Board of Directors May 29, 2026
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Situation Update ▪ Centerview and TD Cowen contacted Morgan Stanley, Toucan’s advisors, before Memorial Day Weekend to connect for an update – Last contact between the advisors had been at the end of April to discuss potential transaction constructs – Strong Pelican in the interim following recent coverage decisions ▪ On 5/27, Morgan Stanley relayed the preliminary outlines of a cash-and-stock acquisition structure for the Pelican Board’s consideration and a potential timeline th – Chris and Eric will be together at ASCO (Saturday, May 30 ) – Can reserve formal response pending further Board discussion – Discussion at ASCO can remain general, in keeping with prior conversations If a high level conceptual alignment is reached, diligence conversations can progress – Substantially all of Toucan’s business diligence is complete – Confirmatory / corporate due diligence remains, which could be finalized in weeks – Reverse diligence to be facilitated by Toucan 2
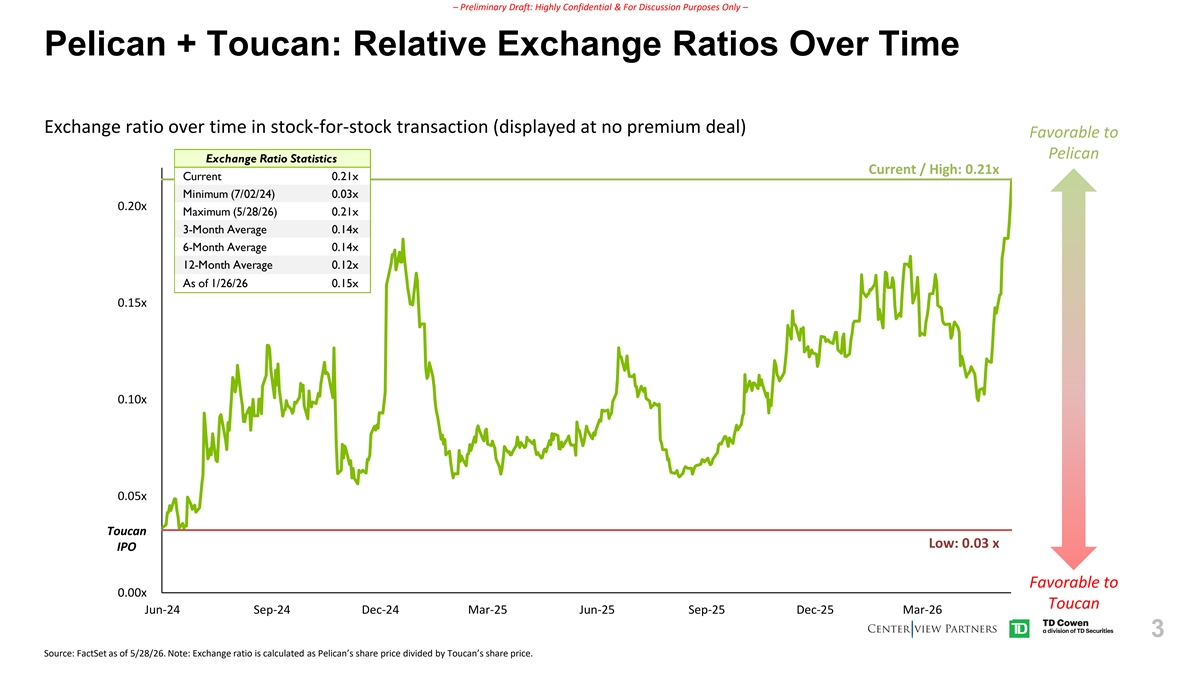
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican + Toucan: Relative Exchange Ratios Over Time Exchange ratio over time in stock-for-stock transaction (displayed at no premium deal) Favorable to Pelican Exchange Ratio Statistics Current / High: 0.21x Current 0.21x Minimum (7/02/24) 0.03x 0.20x Maximum (5/28/26) 0.21x 3-Month Average 0.14x 6-Month Average 0.14x 12-Month Average 0.12x As of 1/26/26 0.15x 0.15x 0.10x 0.05x Toucan Low: 0.03 x IPO Favorable to 0.00x Toucan Jun-24 Sep-24 Dec-24 Mar-25 Jun-25 Sep-25 Dec-25 Mar-26 3 Source: FactSet as of 5/28/26. Note: Exchange ratio is calculated as Pelican’s share price divided by Toucan’s share price.
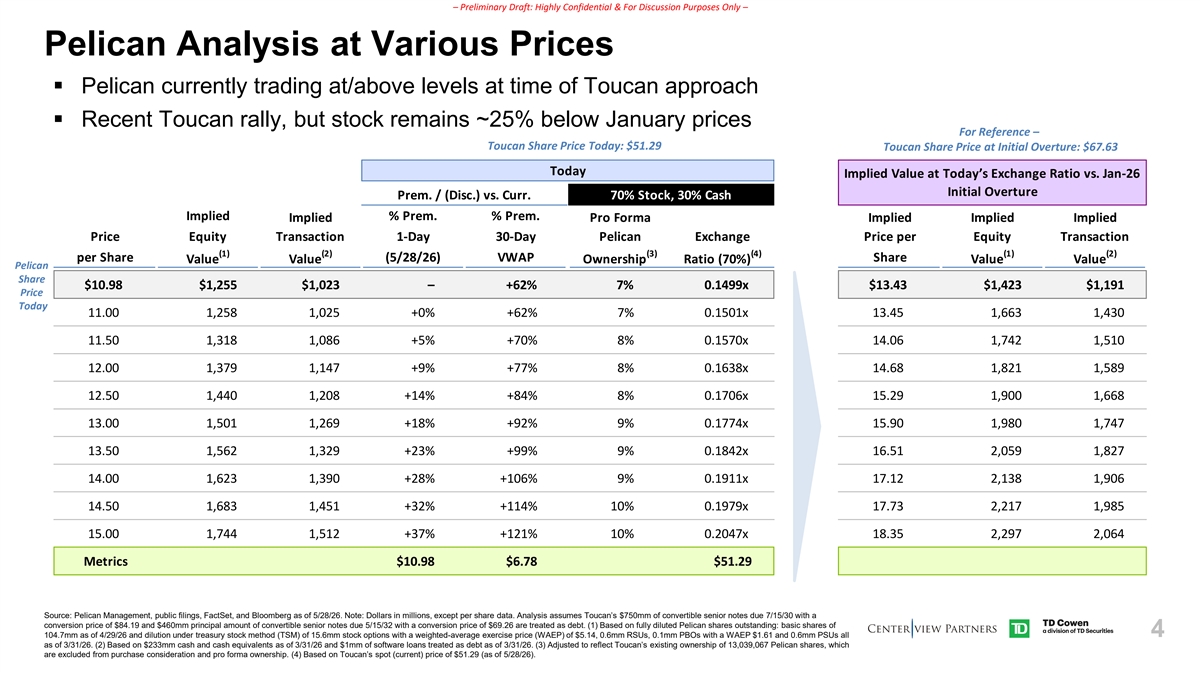
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican Analysis at Various Prices ▪ Pelican currently trading at/above levels at time of Toucan approach ▪ Recent Toucan rally, but stock remains ~25% below January prices For Reference – Toucan Share Price Today: $51.29 Toucan Share Price at Initial Overture: $67.63 Today Implied Value at Today’s Exchange Ratio vs. Jan-26 Initial Overture Prem. / (Disc.) vs. Curr. 70% Stock, 30% Cash Implied % Prem. % Prem. Implied Pro Forma Implied Implied Implied Price Equity Transaction 1-Day 30-Day Pelican Exchange Price per Equity Transaction (1) (2) (3) (4) (1) (2) per Share (5/28/26) VWAP Share Value Value Ownership Ratio (70%) Value Value Pelican Share $10.98 $1,255 $1,023 – +62% 7% 0.1499x $13.43 $1,423 $1,191 Price Today 11.00 1,258 1,025 +0% +62% 7% 0.1501x 13.45 1,663 1,430 11.50 1,318 1,086 +5% +70% 8% 0.1570x 14.06 1,742 1,510 12.00 1,379 1,147 +9% +77% 8% 0.1638x 14.68 1,821 1,589 12.50 1,440 1,208 +14% +84% 8% 0.1706x 15.29 1,900 1,668 13.00 1,501 1,269 +18% +92% 9% 0.1774x 15.90 1,980 1,747 13.50 1,562 1,329 +23% +99% 9% 0.1842x 16.51 2,059 1,827 14.00 1,623 1,390 +28% +106% 9% 0.1911x 17.12 2,138 1,906 14.50 1,683 1,451 +32% +114% 10% 0.1979x 17.73 2,217 1,985 15.00 1,744 1,512 +37% +121% 10% 0.2047x 18.35 2,297 2,064 Metrics $10.98 $6.78 $51.29 Source: Pelican Management, public filings, FactSet, and Bloomberg as of 5/28/26. Note: Dollars in millions, except per share data. Analysis assumes Toucan’s $750mm of convertible senior notes due 7/15/30 with a conversion price of $84.19 and $460mm principal amount of convertible senior notes due 5/15/32 with a conversion price of $69.26 are treated as debt. (1) Based on fully diluted Pelican shares outstanding: basic shares of 104.7mm as of 4/29/26 and dilution under treasury stock method (TSM) of 15.6mm stock options with a weighted-average exercise price (WAEP) of $5.14, 0.6mm RSUs, 0.1mm PBOs with a WAEP $1.61 and 0.6mm PSUs all 4 as of 3/31/26. (2) Based on $233mm cash and cash equivalents as of 3/31/26 and $1mm of software loans treated as debt as of 3/31/26. (3) Adjusted to reflect Toucan’s existing ownership of 13,039,067 Pelican shares, which are excluded from purchase consideration and pro forma ownership. (4) Based on Toucan’s spot (current) price of $51.29 (as of 5/28/26).
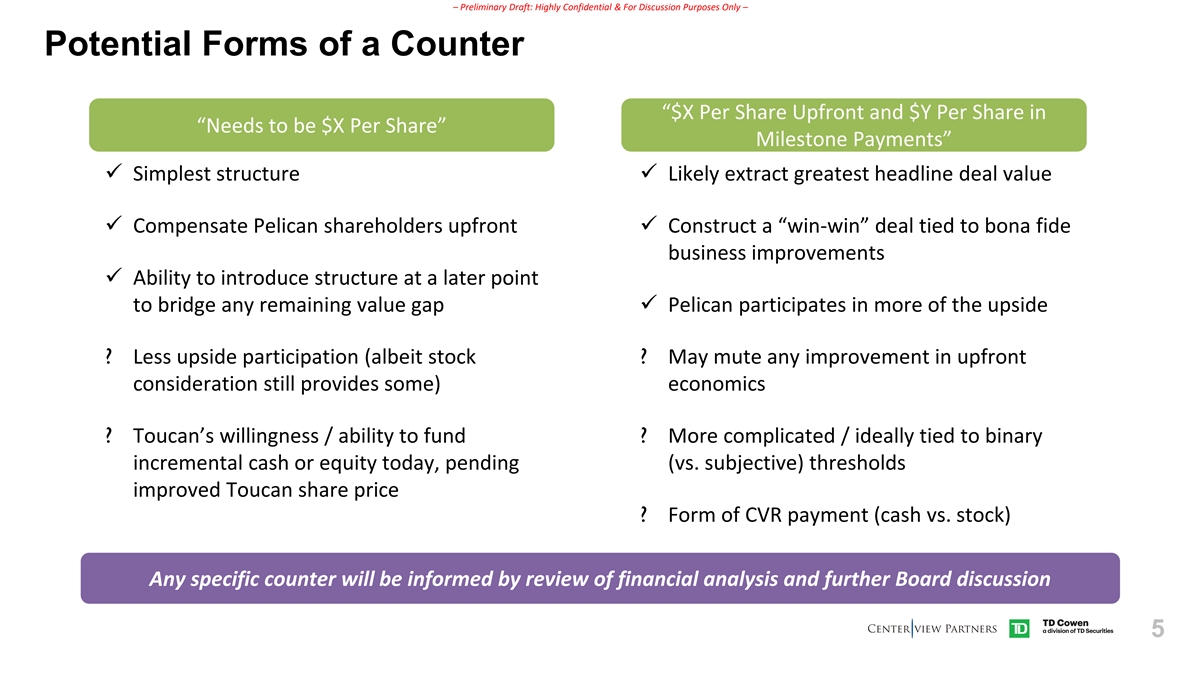
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Potential Forms of a Counter “$X Per Share Upfront and $Y Per Share in “Needs to be $X Per Share” Milestone Payments” ✓ Simplest structure ✓ Likely extract greatest headline deal value ✓ Compensate Pelican shareholders upfront ✓ Construct a “win-win” deal tied to bona fide business improvements ✓ Ability to introduce structure at a later point to bridge any remaining value gap ✓ Pelican participates in more of the upside ? Less upside participation (albeit stock ? May mute any improvement in upfront consideration still provides some) economics ? Toucan’s willingness / ability to fund ? More complicated / ideally tied to binary incremental cash or equity today, pending (vs. subjective) thresholds improved Toucan share price ? Form of CVR payment (cash vs. stock) Any specific counter will be informed by review of financial analysis and further Board discussion 5
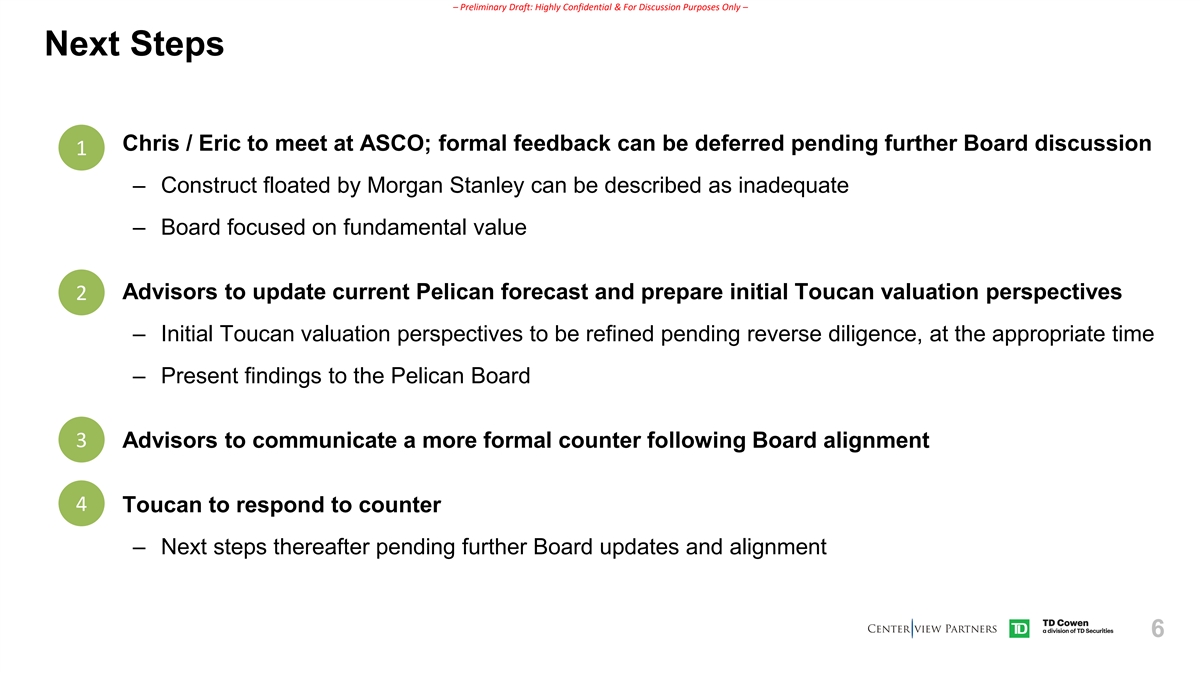
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Next Steps ▪ Chris / Eric to meet at ASCO; formal feedback can be deferred pending further Board discussion 1 – Construct floated by Morgan Stanley can be described as inadequate – Board focused on fundamental value 2▪ Advisors to update current Pelican forecast and prepare initial Toucan valuation perspectives – Initial Toucan valuation perspectives to be refined pending reverse diligence, at the appropriate time – Present findings to the Pelican Board 3▪ Advisors to communicate a more formal counter following Board alignment 4 ▪ Toucan to respond to counter – Next steps thereafter pending further Board updates and alignment 6
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Appendix 7
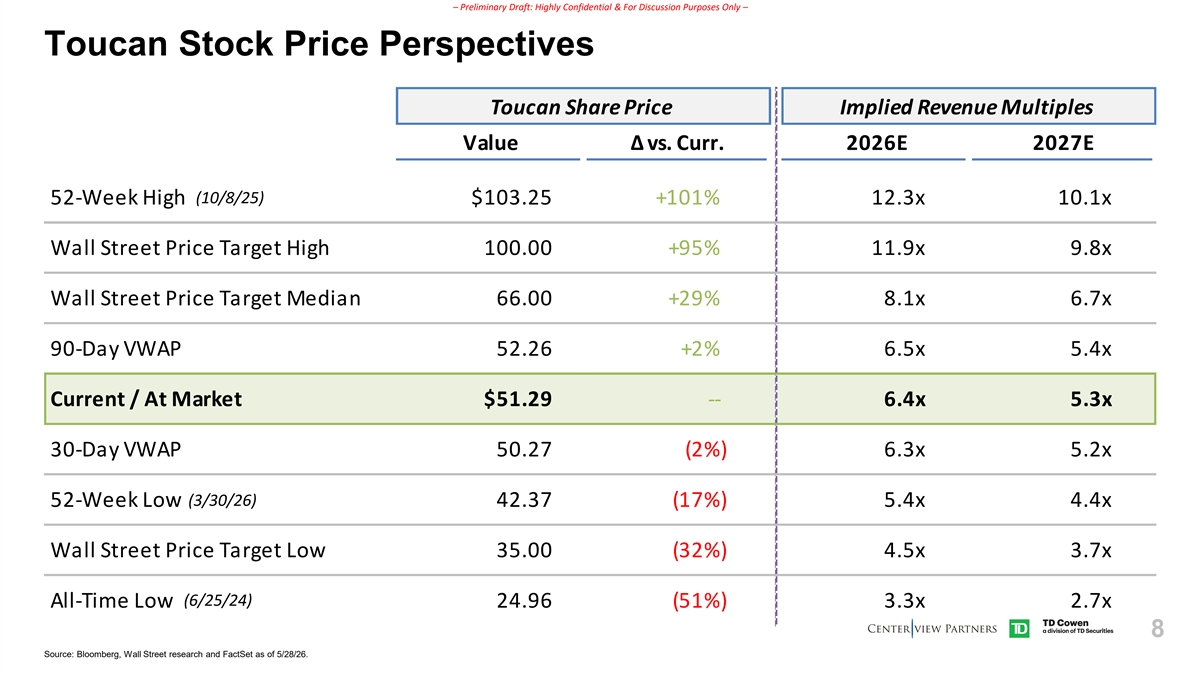
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Toucan Stock Price Perspectives Toucan Share Price Implied Revenue Multiples Value Δ vs. Curr. 2026E 2027E (10/8/25) 52-Week High $103.25 +101% 12.3x 10.1x Wall Street Price Target High 100.00 +95% 11.9x 9.8x Wall Street Price Target Median 66.00 +29% 8.1x 6.7x 90-Day VWAP 52.26 +2% 6.5x 5.4x Current / At Market $51.29 -- 6.4x 5.3x 30-Day VWAP 50.27 (2%) 6.3x 5.2x (3/30/26) 52-Week Low 42.37 (17%) 5.4x 4.4x Wall Street Price Target Low 35.00 (32%) 4.5x 3.7x (6/25/24) All-Time Low 24.96 (51%) 3.3x 2.7x 8 Source: Bloomberg, Wall Street research and FactSet as of 5/28/26.
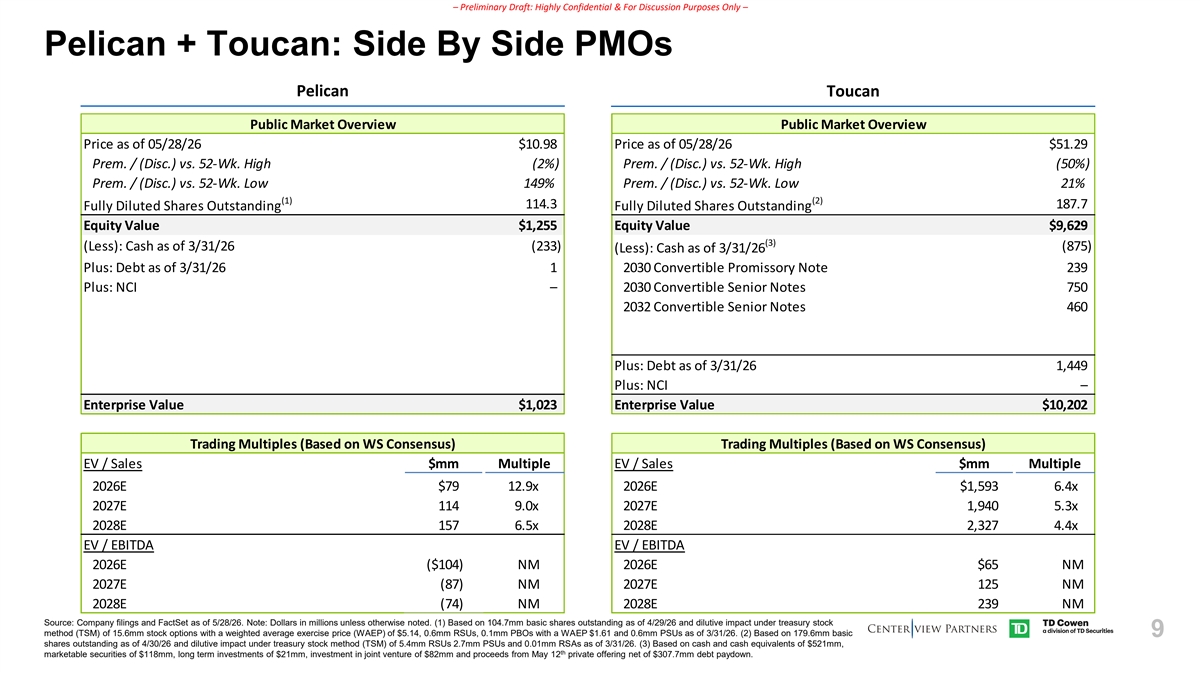
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican + Toucan: Side By Side PMOs Pelican Toucan Public Market Overview Public Market Overview Public Market Overview Price as of 05/28/26 $10.98 Price as of 05/28/26 $51.29 Prem. / (Disc.) vs. 52-Wk. High (2%) Prem. / (Disc.) vs. 52-Wk. High (50%) Prem. / (Disc.) vs. 52-Wk. Low 149% Prem. / (Disc.) vs. 52-Wk. Low 21% (1) (2) 114.3 187.7 Fully Diluted Shares Outstanding Fully Diluted Shares Outstanding Equity Value $1,255 Equity Value $9,629 (3) (Less): Cash as of 3/31/26 (233) (875) (Less): Cash as of 3/31/26 Plus: Debt as of 3/31/26 1 2030 Convertible Promissory Note 239 Plus: NCI – 2030 Convertible Senior Notes 750 2032 Convertible Senior Notes 460 Plus: Debt as of 3/31/26 1,449 Plus: NCI – Enterprise Value $1,023 Enterprise Value $10,202 Trading Multiples (Based on WS Consensus) Trading Multiples (Based on WS Consensus) Trading Multiples (Based on WS Consensus) EV / Sales $mm Multiple EV / Sales $mm Multiple 2026E $79 12.9x 2026E $1,593 6.4x 2027E 114 9.0x 2027E 1,940 5.3x 2028E 157 6.5x 2028E 2,327 4.4x EV / EBITDA EV / EBITDA 2026E ($104) NM 2026E $65 NM 2027E (87) NM 2027E 125 NM 2028E (74) NM 2028E 239 NM Source: Company filings and FactSet as of 5/28/26. Note: Dollars in millions unless otherwise noted. (1) Based on 104.7mm basic shares outstanding as of 4/29/26 and dilutive impact under treasury stock method (TSM) of 15.6mm stock options with a weighted average exercise price (WAEP) of $5.14, 0.6mm RSUs, 0.1mm PBOs with a WAEP $1.61 and 0.6mm PSUs as of 3/31/26. (2) Based on 179.6mm basic 9 shares outstanding as of 4/30/26 and dilutive impact under treasury stock method (TSM) of 5.4mm RSUs 2.7mm PSUs and 0.01mm RSAs as of 3/31/26. (3) Based on cash and cash equivalents of $521mm, th marketable securities of $118mm, long term investments of $21mm, investment in joint venture of $82mm and proceeds from May 12 private offering net of $307.7mm debt paydown.
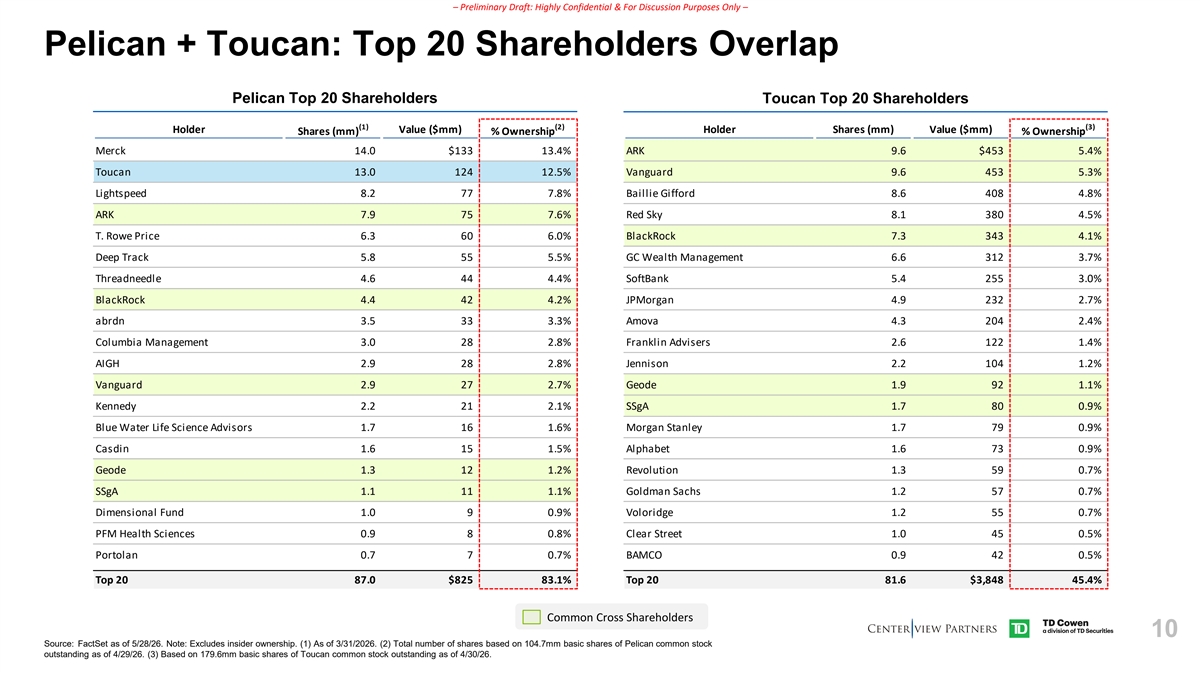
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican + Toucan: Top 20 Shareholders Overlap Pelican Top 20 Shareholders Toucan Top 20 Shareholders (1) (2) (3) Holder Value ($mm) Holder Shares (mm) Value ($mm) Shares (mm) % Ownership % Ownership Merck 14.0 $133 13.4% ARK 9.6 $453 5.4% Toucan 13.0 124 12.5% Vanguard 9.6 453 5.3% Lightspeed 8.2 77 7.8% Baillie Gifford 8.6 408 4.8% ARK 7.9 75 7.6% Red Sky 8.1 380 4.5% T. Rowe Price 6.3 60 6.0% BlackRock 7.3 343 4.1% Deep Track 5.8 55 5.5% GC Wealth Management 6.6 312 3.7% Threadneedle 4.6 44 4.4% SoftBank 5.4 255 3.0% BlackRock 4.4 42 4.2% JPMorgan 4.9 232 2.7% abrdn 3.5 33 3.3% Amova 4.3 204 2.4% Columbia Management 3.0 28 2.8% Franklin Advisers 2.6 122 1.4% AIGH 2.9 28 2.8% Jennison 2.2 104 1.2% Vanguard 2.9 27 2.7% Geode 1.9 92 1.1% Kennedy 2.2 21 2.1% SSgA 1.7 80 0.9% Blue Water Life Science Advisors 1.7 16 1.6% Morgan Stanley 1.7 79 0.9% Casdin 1.6 15 1.5% Alphabet 1.6 73 0.9% Geode 1.3 12 1.2% Revolution 1.3 59 0.7% SSgA 1.1 11 1.1% Goldman Sachs 1.2 57 0.7% Dimensional Fund 1.0 9 0.9% Voloridge 1.2 55 0.7% PFM Health Sciences 0.9 8 0.8% Clear Street 1.0 45 0.5% Portolan 0.7 7 0.7% BAMCO 0.9 42 0.5% Top 20 87.0 $825 83.1% Top 20 81.6 $3,848 45.4% Common Cross Shareholders 10 Source: FactSet as of 5/28/26. Note: Excludes insider ownership. (1) As of 3/31/2026. (2) Total number of shares based on 104.7mm basic shares of Pelican common stock outstanding as of 4/29/26. (3) Based on 179.6mm basic shares of Toucan common stock outstanding as of 4/30/26.
Exhibit (c)(8) Project Aviary Presentation to the Board of Directors June 5, 2026
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Centerview Disclaimer This presentation has been prepared by Centerview Partners LLC (“Centerview”) for use solely by the Board of Directors of Personalis (“Pelican” or the “Company”) in connection with its evaluation of a potential sale of Pelican and for no other purpose. The information contained herein is based upon information supplied by or on behalf of Pelican and publicly available information, and portions of the information contained herein may be based upon statements, estimates and forecasts provided by Pelican. Centerview has relied upon the accuracy and completeness of the foregoing information, and has not assumed any responsibility for any independent verification of such information or for any independent evaluation or appraisal of any of the assets or liabilities (contingent or otherwise) of Pelican or any other entity, or concerning the solvency or fair value of Pelican or any other entity. With respect to financial forecasts, Centerview has assumed that such forecasts have been reasonably prepared on bases reflecting the best currently available estimates and judgments of the management of Pelican as to the future financial performance of Pelican, and at your direction Centerview has relied upon such forecasts, as provided by Pelican management, with respect to Pelican. Centerview assumes no responsibility for and expresses no view as to such forecasts or the assumptions on which they are based. The information set forth herein is based upon economic, monetary, market and other conditions as in effect on, and the information made available to us as of, the date hereof, unless indicated otherwise and Centerview assumes no obligation to update or otherwise revise these materials. The financial analysis in this presentation is complex and is not necessarily susceptible to a partial analysis or summary description. In performing this financial analysis, Centerview has considered the results of its analysis as a whole and did not necessarily attribute a particular weight to any particular portion of the analysis considered. Furthermore, selecting any portion of Centerview’s analysis, without considering the analysis as a whole, would create an incomplete view of the process underlying its financial analysis. Centerview may have deemed various assumptions more or less probable than other assumptions, so the reference ranges resulting from any particular portion of the analysis described above should not be taken to be Centerview’s view of the actual value of Pelican. These materials and the information contained herein are confidential, were not prepared with a view toward public disclosure, and may not be disclosed publicly or made available to third parties without the prior written consent of Centerview. These materials and any other advice, written or oral, rendered by Centerview are intended solely for the benefit and use of the Board of Directors of Pelican (in its capacity as such) in its consideration of the proposed transaction, and are not for the benefit of, and do not convey any rights or remedies for any holder of securities of Pelican or any other person. Centerview will not be responsible for and has not provided any tax, accounting, actuarial, legal or other specialist advice. These materials are not intended to provide the sole basis for evaluating the proposed transaction, and this presentation does not represent a fairness opinion, recommendation, valuation or opinion of any kind, and is necessarily incomplete and should be viewed solely in conjunction with the oral presentation provided by Centerview. 2
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – TD Cowen Disclaimer These materials were prepared solely for the information and benefit of Personalis, Inc. (“PELICAN”) in connection with a proposed transaction with Tempus AI, Inc. (the Transaction ). These materials are preliminary and for discussion purposes only. TD Securities (USA) LLC ( TD Securities ) expresses no view as to PELICAN’s underlying business decision to effect the proposed Transaction, the relative merits of the proposed Transaction as compared to other business strategies or transactions that might be available to PELICAN or to any other aspect or implication of the proposed Transaction or any other agreement, arrangement or understanding entered into in connection with the proposed Transaction or otherwise. In preparing these materials, TD Securities has, with PELICAN’s consent, relied upon information provided to TD Securities by PELICAN management, or publicly available information or information otherwise reviewed by TD Securities. TD Securities has not independently verified any such information and has relied on it being complete and accurate in all material respects. To the extent such information includes estimates and forecasts of future financial performance prepared by PELICAN management or obtained from public sources, TD Securities has utilized such estimates and forecasts at PELICAN’s direction and has assumed that such estimates and forecasts have been reasonably prepared on bases reflecting the best currently available estimates and judgments of PELICAN management or, with respect to estimates and forecasts obtained from public sources, represent reasonable estimates and forecasts. Please note that these materials are based on the business and operations of PELICAN as represented to TD Securities as of the date hereof and do not purport to take into consideration any information or events arising subsequent to such date. TD Securities makes no representation or warranty that there has been no material change in the information provided or reviewed by TD Securities in connection herewith. TD Securities has no obligation to update these materials. The information contained herein is highly confidential and has been prepared exclusively for the benefit and use of PELICAN in its consideration of the proposed Transaction, and may not be used for any other purpose or disclosed, copied, reproduced, disseminated, quoted or referred to at any time, in any manner or for any purpose without TD Securities’ prior written consent, except as specifically set forth in the engagement letter between TD Securities and PELICAN. These materials are not for the benefit of, and do not convey any rights or remedies to, any holder of securities of PELICAN or any other person. These materials are subject to various assumptions, qualifications and limitations, and does not constitute a recommendation by TD Securities to PELICAN or any other person on how to act with respect to any such proposed Transaction. TD Securities does not address any legal, regulatory, tax or accounting effects of the proposed Transaction and nothing contained herein should be construed as legal, regulatory, tax or accounting advice. TD Securities” is a trademark of The Toronto-Dominion Bank (“TD”) and represents certain investment banking, capital markets and wholesale banking activities conducted through certain subsidiaries and branches of TD. “TD Cowen” is a division of TD Securities and represents a marketing name of certain businesses within TD Securities. © Copyright 2026 TD. All rights reserved. ® The TD logo and other TD trademarks are the property of TD or its subsidiaries. TD Securities Inc. is regulated by the Canadian Investment Regulatory Organization of Canada. TD Securities Inc. is a member of the Canadian Investor Protection Fund and a member of Canadian Marketplaces. TD Securities (USA) LLC, TD Prime Services LLC, TD Financial Products LLC, TD Arranged Services LLC and Westminster Research Associates LLC are registered with the U.S. Securities and Exchange Commission and are members of the Financial Industry Regulatory Authority (FINRA) and of the Securities Investor Protection Corporation (SIPC). 3
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Today’s Agenda and Objectives 1. Refresh on the Toucan Value Indication 2. Banks’ Preliminary Financial Analyses – Pelican – Toucan 3. Toucan Value Indication in Context 4. Next Steps 4
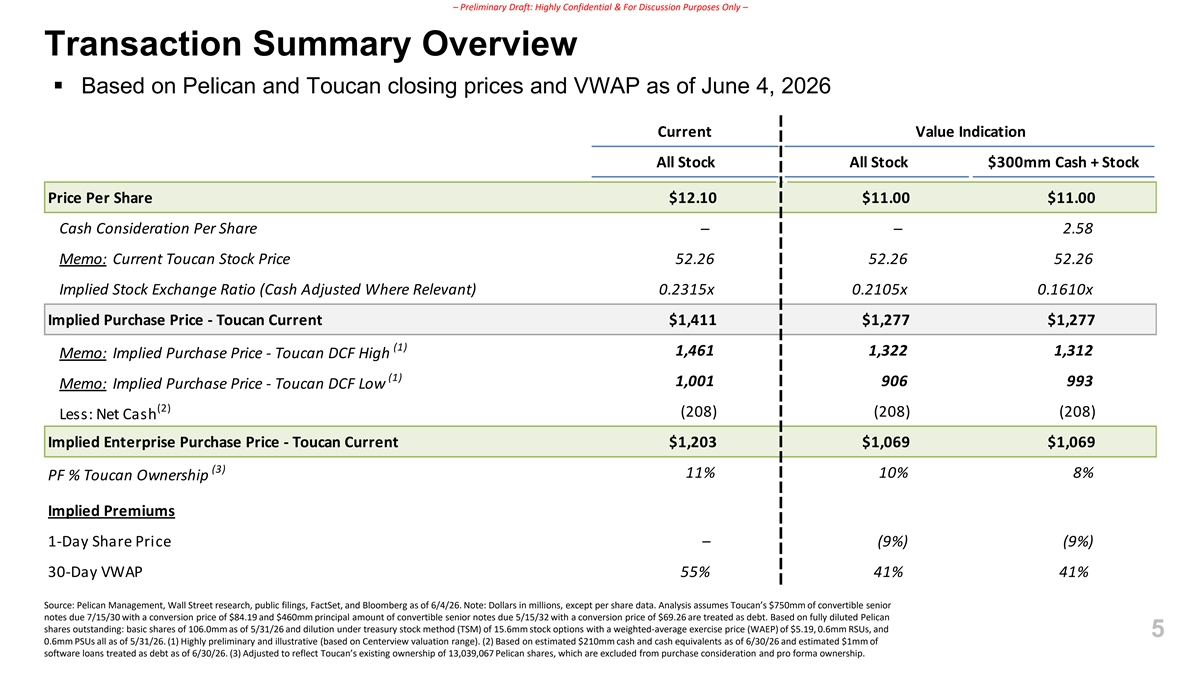
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Transaction Summary Overview ▪ Based on Pelican and Toucan closing prices and VWAP as of June 4, 2026 Current Value Indication All Stock All Stock $300mm Cash + Stock Price Per Share $12.10 $11.00 $11.00 Cash Consideration Per Share–– 2.58 Memo: Current Toucan Stock Price 52.26 52.26 52.26 Implied Stock Exchange Ratio (Cash Adjusted Where Relevant) 0.2315x 0.2105x 0.1610x Implied Purchase Price - Toucan Current $1,411 $1,277 $1,277 (1) 1,461 1,322 1,312 Memo: Implied Purchase Price - Toucan DCF High (1) 1,001 906 993 Memo: Implied Purchase Price - Toucan DCF Low (2) (208) (208) (208) Less: Net Cash Implied Enterprise Purchase Price - Toucan Current $1,203 $1,069 $1,069 (3) 11% 10% 8% PF % Toucan Ownership Implied Premiums 1-Day Share Price – (9%) (9%) 30-Day VWAP 55% 41% 41% Source: Pelican Management, Wall Street research, public filings, FactSet, and Bloomberg as of 6/4/26. Note: Dollars in millions, except per share data. Analysis assumes Toucan’s $750mm of convertible senior notes due 7/15/30 with a conversion price of $84.19 and $460mm principal amount of convertible senior notes due 5/15/32 with a conversion price of $69.26 are treated as debt. Based on fully diluted Pelican shares outstanding: basic shares of 106.0mm as of 5/31/26 and dilution under treasury stock method (TSM) of 15.6mm stock options with a weighted-average exercise price (WAEP) of $5.19, 0.6mm RSUs, and 5 0.6mm PSUs all as of 5/31/26. (1) Highly preliminary and illustrative (based on Centerview valuation range). (2) Based on estimated $210mm cash and cash equivalents as of 6/30/26 and estimated $1mm of software loans treated as debt as of 6/30/26. (3) Adjusted to reflect Toucan’s existing ownership of 13,039,067 Pelican shares, which are excluded from purchase consideration and pro forma ownership.
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican Public Market Perspectives 6
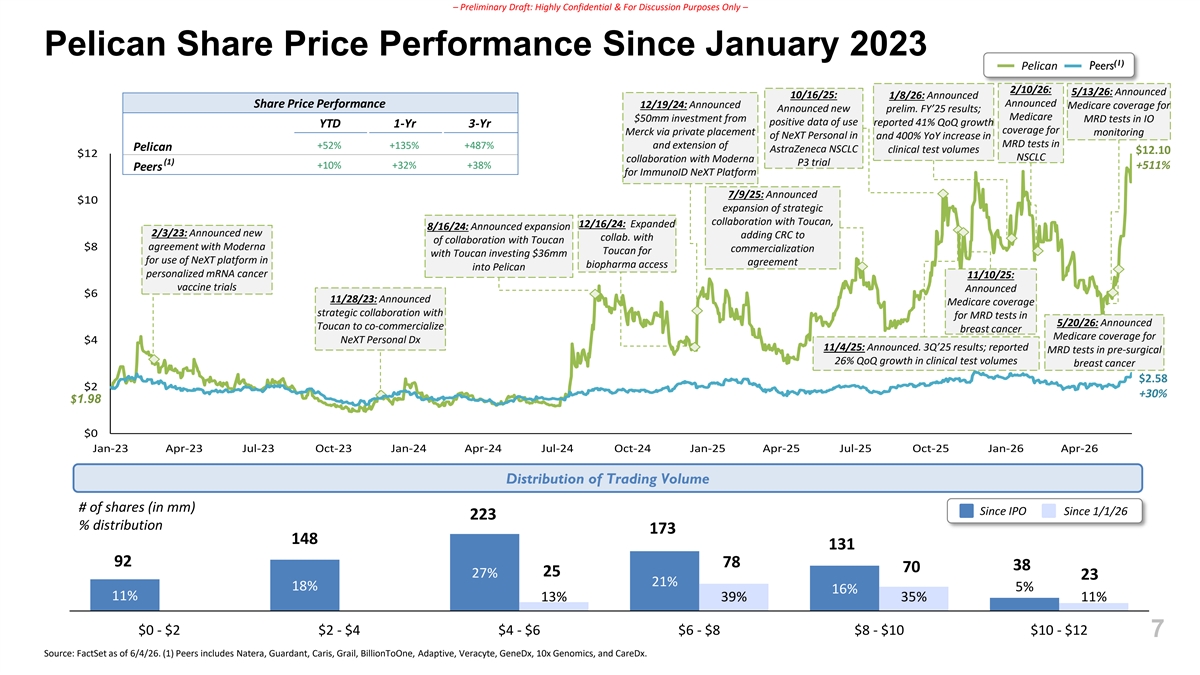
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican Share Price Performance Since January 2023 (1) Pelican Peers 2/10/26: 5/13/26: Announced 10/16/25: 1/8/26: Announced Announced Share Price Performance 12/19/24: Announced Medicare coverage for Announced new prelim. FY’25 results; Medicare $50mm investment from MRD tests in IO positive data of use reported 41% QoQ growth YTD 1-Yr 3-Yr coverage for Merck via private placement monitoring of NeXT Personal in and 400% YoY increase in MRD tests in +52% +135% +487% and extension of Pelican AstraZeneca NSCLC clinical test volumes $12.10 $12 NSCLC collaboration with Moderna (1) P3 trial +10% +32% +38% +511% Peers for ImmunoID NeXT Platform 7/9/25: Announced $10 expansion of strategic collaboration with Toucan, 12/16/24: Expanded 8/16/24: Announced expansion 2/3/23: Announced new adding CRC to collab. with of collaboration with Toucan $8 agreement with Moderna commercialization Toucan for with Toucan investing $36mm for use of NeXT platform in agreement biopharma access into Pelican personalized mRNA cancer 11/10/25: vaccine trials Announced $6 11/28/23: Announced Medicare coverage strategic collaboration with for MRD tests in 5/20/26: Announced Toucan to co-commercialize breast cancer Medicare coverage for $4 NeXT Personal Dx 11/4/25: Announced. 3Q’25 results; reported MRD tests in pre-surgical 26% QoQ growth in clinical test volumes breast cancer $2.58 $2 +30% $1.98 $0 Jan-23 Apr-23 Jul-23 Oct-23 Jan-24 Apr-24 Jul-24 Oct-24 Jan-25 Apr-25 Jul-25 Oct-25 Jan-26 Apr-26 Distribution of Trading Volume # of shares (in mm) Since IPO Since 1/1/26 223 % distribution 173 148 131 92 78 38 70 25 27% 23 21% 18% 5% 16% 11% 13% 39% 35% 11% $0 - $2 $2 - $4 $4 - $6 $6 - $8 $8 - $10 $10 - $12 7 Source: FactSet as of 6/4/26. (1) Peers includes Natera, Guardant, Caris, Grail, BillionToOne, Adaptive, Veracyte, GeneDx, 10x Genomics, and CareDx.
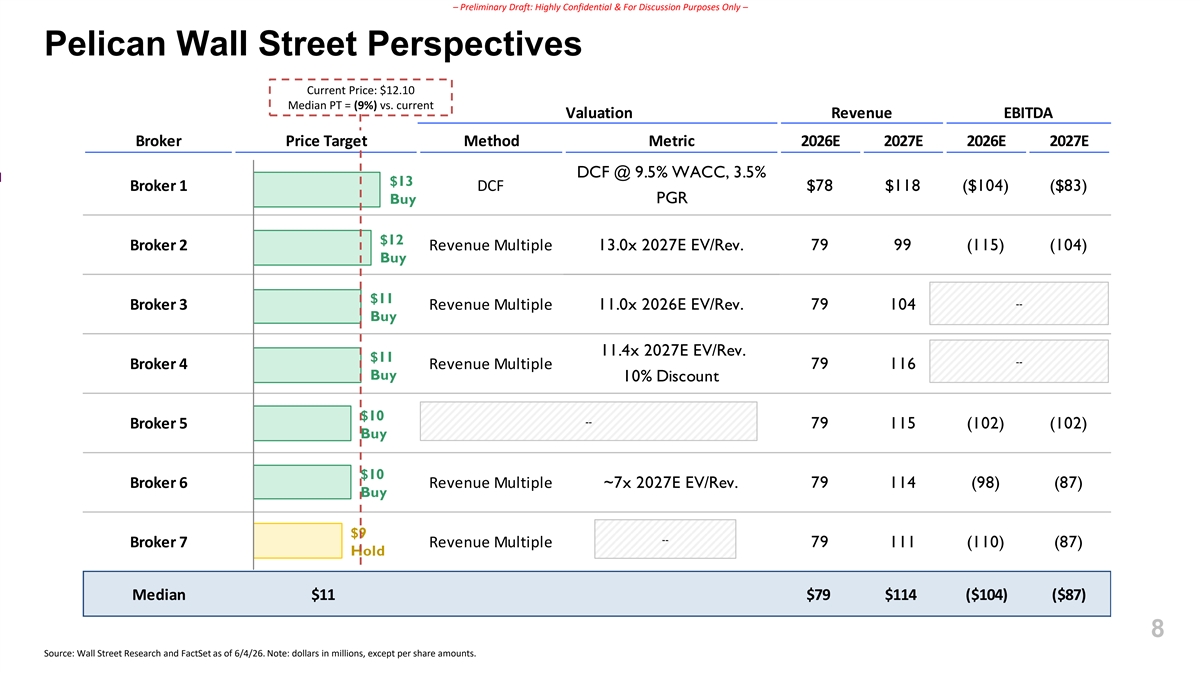
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican Wall Street Perspectives Current Price: $12.10 Median PT = (9%) vs. current Valuation Revenue EBITDA Broker Price Target Method Metric 2026E 2027E 2026E 2027E DCF @ 9.5% WACC, 3.5% $13 Broker 1 DCF $78 $118 ($104) ($83) Buy PGR $12 Broker 2 Revenue Multiple 13.0x 2027E EV/Rev. 79 99 (115) (104) Buy $11 -- Broker 3 Revenue Multiple 11.0x 2026E EV/Rev. 79 104 n.a. n.a. Buy 11.4x 2027E EV/Rev. $11 -- Broker 4 Revenue Multiple 79 116 n.a. n.a. Buy 10% Discount $10 -- Broker 5 -- -- 79 115 (102) (102) Buy $10 Broker 6 Revenue Multiple ~7x 2027E EV/Rev. 79 114 (98) (87) Buy $9 -- Broker 7 Revenue Multiple -- 79 111 (110) (87) Hold Median $11 $79 $114 ($104) ($87) 8 Source: Wall Street Research and FactSet as of 6/4/26. Note: dollars in millions, except per share amounts.
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Pelican Management Financial Projections 9
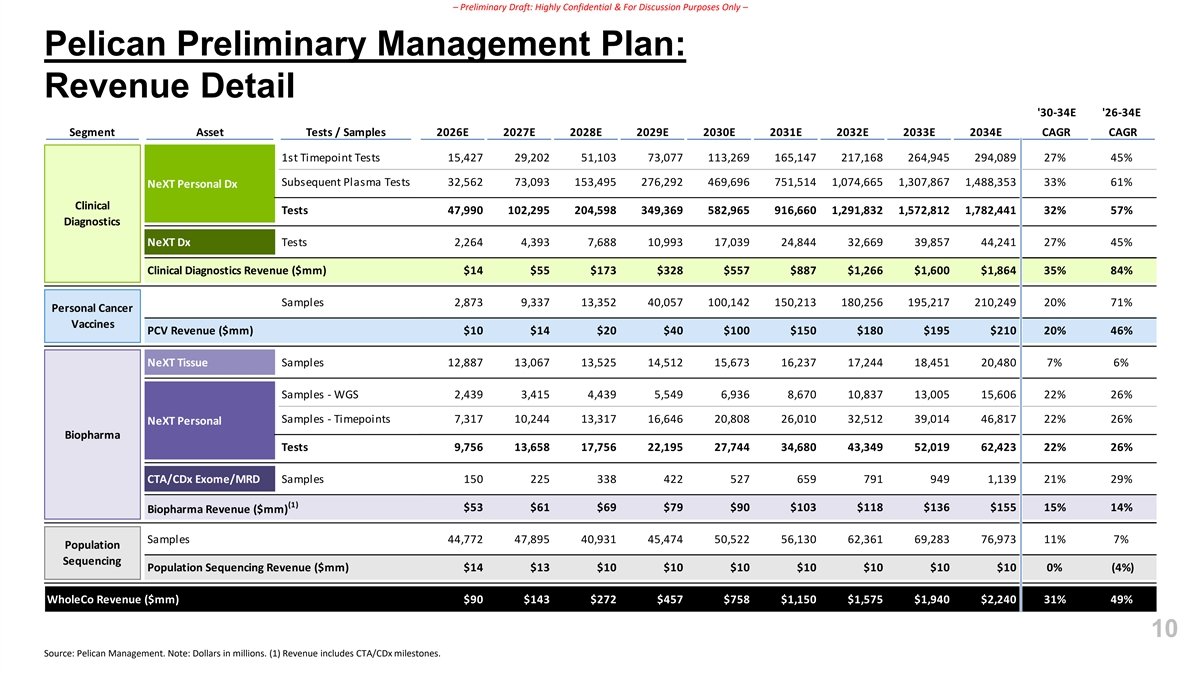
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican Preliminary Management Plan: Revenue Detail '30-34E '26-34E Segment Asset Tests / Samples 2026E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E CAGR CAGR 1st Timepoint Tests 15,427 29,202 51,103 73,077 113,269 165,147 217,168 264,945 294,089 27% 45% Subsequent Plasma Tests 32,562 73,093 153,495 276,292 469,696 751,514 1,074,665 1,307,867 1,488,353 33% 61% NeXT Personal Dx Clinical Tests 47,990 102,295 204,598 349,369 582,965 916,660 1,291,832 1,572,812 1,782,441 32% 57% Diagnostics NeXT Dx Tests 2,264 4,393 7,688 10,993 17,039 24,844 32,669 39,857 44,241 27% 45% Clinical Diagnostics Revenue ($mm) $14 $55 $173 $328 $557 $887 $1,266 $1,600 $1,864 35% 84% Samples 2,873 9,337 13,352 40,057 100,142 150,213 180,256 195,217 210,249 20% 71% Personal Cancer Vaccines PCV Revenue ($mm) $10 $14 $20 $40 $100 $150 $180 $195 $210 20% 46% NeXT Tissue Samples 12,887 13,067 13,525 14,512 15,673 16,237 17,244 18,451 20,480 7% 6% Samples - WGS 2,439 3,415 4,439 5,549 6,936 8,670 10,837 13,005 15,606 22% 26% Samples - Timepoints 7,317 10,244 13,317 16,646 20,808 26,010 32,512 39,014 46,817 22% 26% NeXT Personal Biopharma Tests 9,756 13,658 17,756 22,195 27,744 34,680 43,349 52,019 62,423 22% 26% CTA/CDx Exome/MRD Samples 150 225 338 422 527 659 791 949 1,139 21% 29% (1) $53 $61 $69 $79 $90 $103 $118 $136 $155 15% 14% Biopharma Revenue ($mm) Samples 44,772 47,895 40,931 45,474 50,522 56,130 62,361 69,283 76,973 11% 7% Population Sequencing Population Sequencing Revenue ($mm) $14 $13 $10 $10 $10 $10 $10 $10 $10 0% (4%) WholeCo Revenue ($mm) $90 $143 $272 $457 $758 $1,150 $1,575 $1,940 $2,240 31% 49% 10 Source: Pelican Management. Note: Dollars in millions. (1) Revenue includes CTA/CDx milestones.
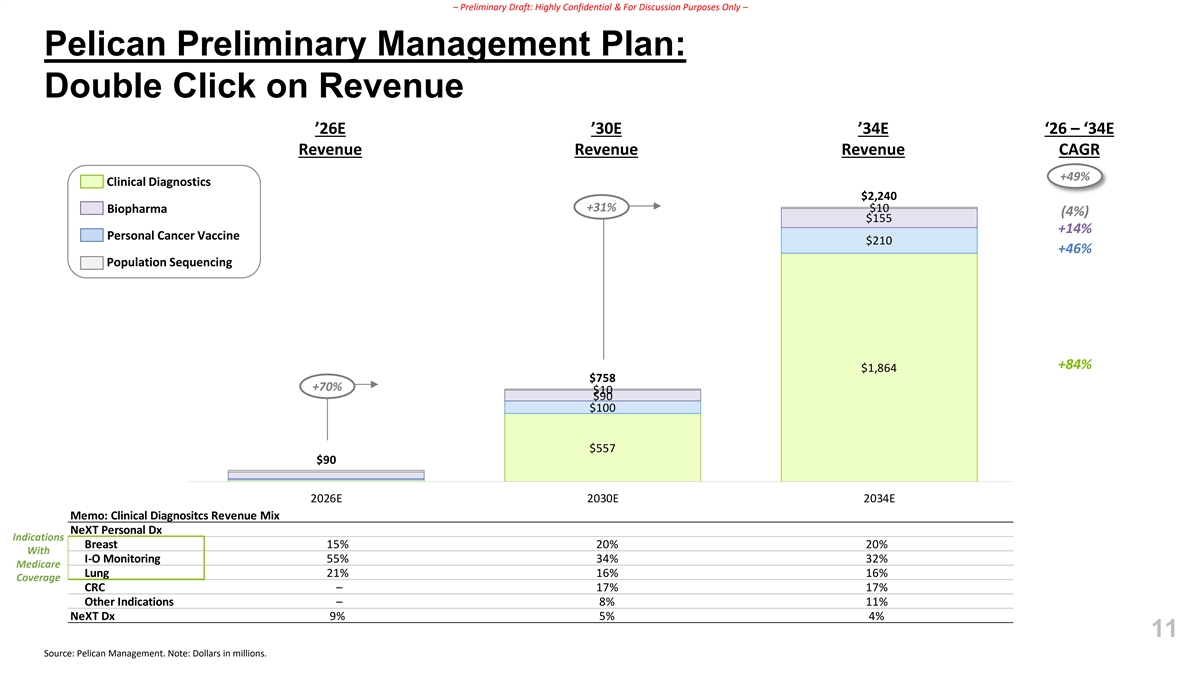
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican Preliminary Management Plan: Double Click on Revenue ’26E ’30E ’34E ‘26 – ‘34E Revenue Revenue Revenue CAGR +49% Clinical Diagnostics $2,240 +31% Biopharma $10 (4%) $155 +14% Personal Cancer Vaccine $210 +46% Population Sequencing +84% $1,864 $758 +70% $10 $90 $100 $557 $90 2026E 2030E 2034E Memo: Clinical Diagnositcs Revenue Mix NeXT Personal Dx Indications Breast 15% 20% 20% With I-O Monitoring 55% 34% 32% Medicare Lung 21% 16% 16% Coverage CRC – 17% 17% Other Indications – 8% 11% NeXT Dx 9% 5% 4% 11 Source: Pelican Management. Note: Dollars in millions.
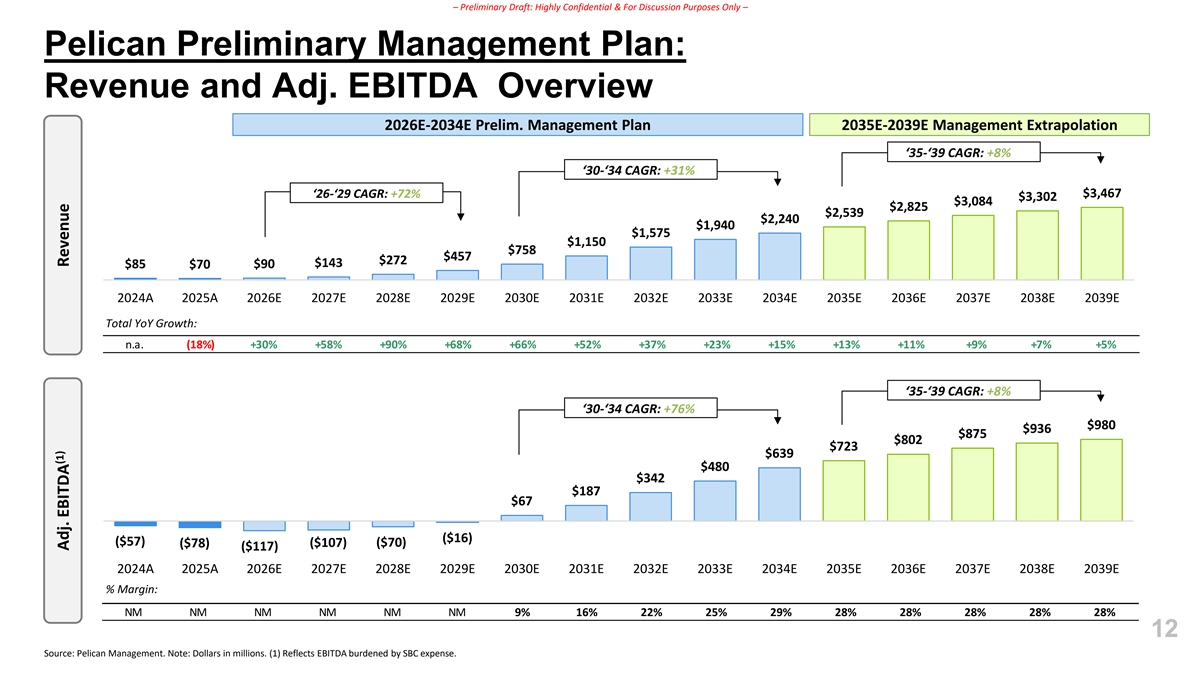
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican Preliminary Management Plan: Revenue and Adj. EBITDA Overview 2026E-2034E Prelim. Management Plan 2035E-2039E Management Extrapolation ‘35-‘39 CAGR: +8% ‘30-‘34 CAGR: +31% ‘26-‘29 CAGR: +72% $3,467 $3,302 $3,084 $2,825 $2,539 $2,240 $1,940 $1,575 $1,150 $758 $457 $272 $143 $85 $70 $90 2024A 2025A 2026E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E 2036E 2037E 2038E 2039E Total YoY Growth: n.a. (18%) +30% +58% +90% +68% +66% +52% +37% +23% +15% +13% +11% +9% +7% +5% ‘35-‘39 CAGR: +8% ‘30-‘34 CAGR: +76% $980 $936 $875 $802 $723 $639 $480 $342 $187 $67 ($16) ($57) ($78) ($107) ($70) ($117) 2024A 2025A 2026E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E 2036E 2037E 2038E 2039E % Margin: NM NM NM NM NM NM 9% 16% 22% 25% 29% 28% 28% 28% 28% 28% 12 Source: Pelican Management. Note: Dollars in millions. (1) Reflects EBITDA burdened by SBC expense. (1) Adj. EBITDA Revenue
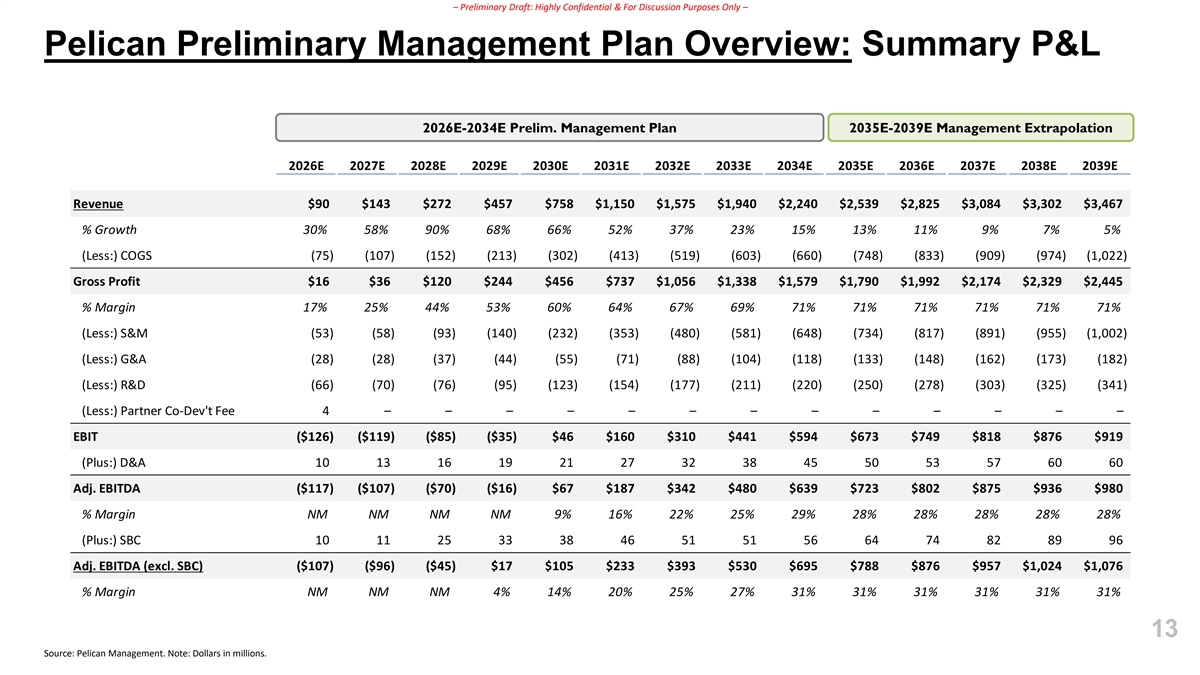
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican Preliminary Management Plan Overview: Summary P&L 2026E-2034E Prelim. Management Plan 2035E-2039E Management Extrapolation 2026E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E 2036E 2037E 2038E 2039E Revenue $90 $143 $272 $457 $758 $1,150 $1,575 $1,940 $2,240 $2,539 $2,825 $3,084 $3,302 $3,467 % Growth 30% 58% 90% 68% 66% 52% 37% 23% 15% 13% 11% 9% 7% 5% (Less:) COGS (75) (107) (152) (213) (302) (413) (519) (603) (660) (748) (833) (909) (974) (1,022) Gross Profit $16 $36 $120 $244 $456 $737 $1,056 $1,338 $1,579 $1,790 $1,992 $2,174 $2,329 $2,445 % Margin 17% 25% 44% 53% 60% 64% 67% 69% 71% 71% 71% 71% 71% 71% (Less:) S&M (53) (58) (93) (140) (232) (353) (480) (581) (648) (734) (817) (891) (955) (1,002) (Less:) G&A (28) (28) (37) (44) (55) (71) (88) (104) (118) (133) (148) (162) (173) (182) (Less:) R&D (66) (70) (76) (95) (123) (154) (177) (211) (220) (250) (278) (303) (325) (341) (Less:) Partner Co-Dev't Fee 4 – – – – – – – – – – – – – EBIT ($126) ($119) ($85) ($35) $46 $160 $310 $441 $594 $673 $749 $818 $876 $919 (Plus:) D&A 10 13 16 19 21 27 32 38 45 50 53 57 60 60 Adj. EBITDA ($117) ($107) ($70) ($16) $67 $187 $342 $480 $639 $723 $802 $875 $936 $980 % Margin NM NM NM NM 9% 16% 22% 25% 29% 28% 28% 28% 28% 28% (Plus:) SBC 10 11 25 33 38 46 51 51 56 64 74 82 89 96 Adj. EBITDA (excl. SBC) ($107) ($96) ($45) $17 $105 $233 $393 $530 $695 $788 $876 $957 $1,024 $1,076 % Margin NM NM NM 4% 14% 20% 25% 27% 31% 31% 31% 31% 31% 31% 13 Source: Pelican Management. Note: Dollars in millions.
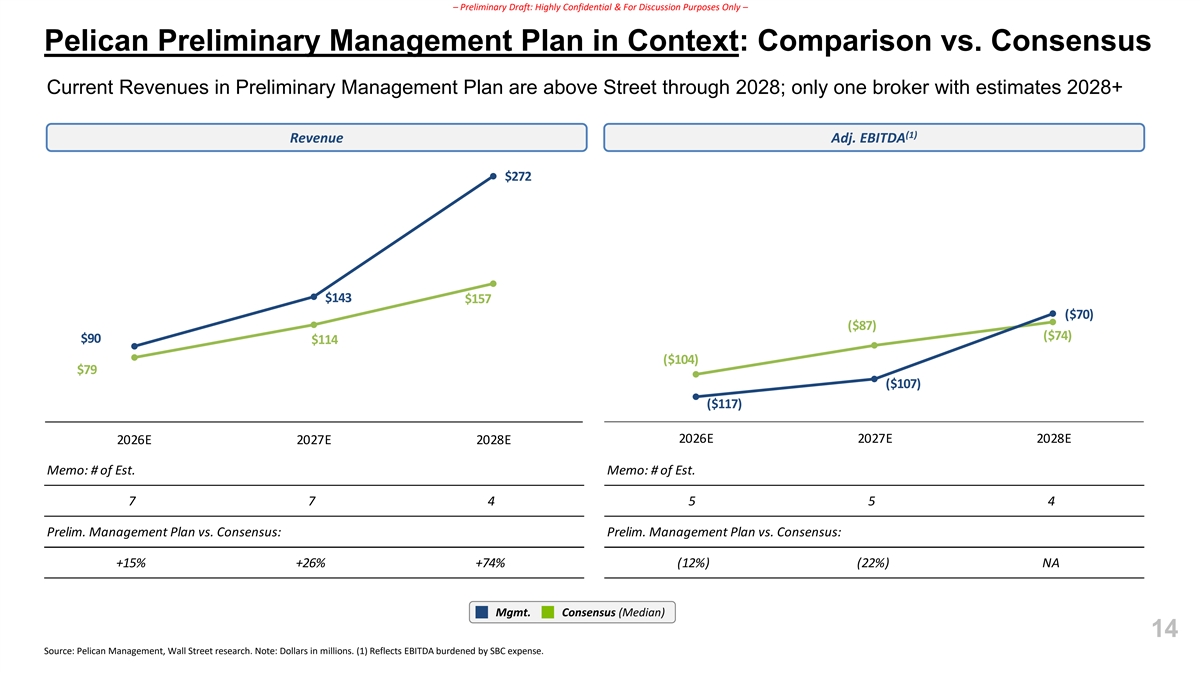
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican Preliminary Management Plan in Context: Comparison vs. Consensus Current Revenues in Preliminary Management Plan are above Street through 2028; only one broker with estimates 2028+ (1) Revenue Adj. EBITDA $272 $143 $157 ($70) ($87) ($74) $90 $114 ($104) $79 ($107) ($117) 2026E 2027E 2028E 2026E 2027E 2028E Memo: # of Est. Memo: # of Est. 7 7 4 5 5 4 Prelim. Management Plan vs. Consensus: Prelim. Management Plan vs. Consensus: +15% +26% +74% (12%) (22%) NA Mgmt. Consensus (Median) 14 Source: Pelican Management, Wall Street research. Note: Dollars in millions. (1) Reflects EBITDA burdened by SBC expense.
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Centerview Pelican Financial Analysis 15
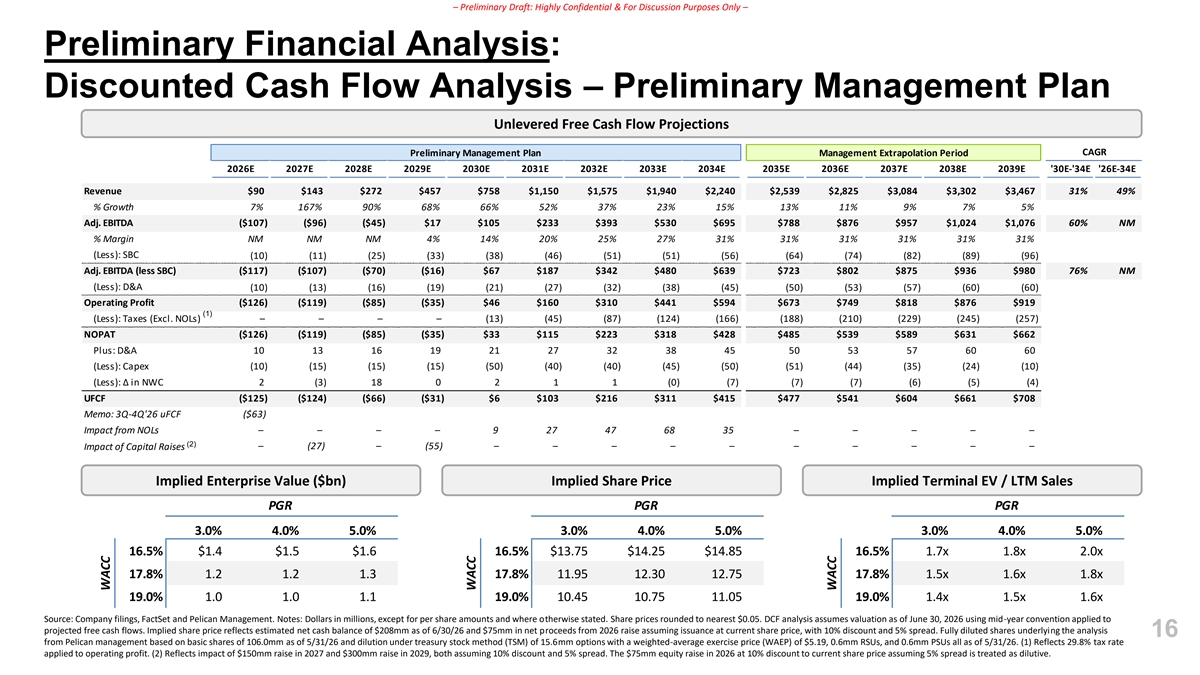
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Financial Analysis: Discounted Cash Flow Analysis – Preliminary Management Plan Unlevered Free Cash Flow Projections CAGR Preliminary Management Plan Management Extrapolation Period 2026E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E 2036E 2037E 2038E 2039E '30E-'34E '26E-34E Revenue $90 $143 $272 $457 $758 $1,150 $1,575 $1,940 $2,240 $2,539 $2,825 $3,084 $3,302 $3,467 31% 49% % Growth 7% 167% 90% 68% 66% 52% 37% 23% 15% 13% 11% 9% 7% 5% Adj. EBITDA ($107) ($96) ($45) $17 $105 $233 $393 $530 $695 $788 $876 $957 $1,024 $1,076 60% NM % Margin NM NM NM 4% 14% 20% 25% 27% 31% 31% 31% 31% 31% 31% (Less): SBC (10) (11) (25) (33) (38) (46) (51) (51) (56) (64) (74) (82) (89) (96) Adj. EBITDA (less SBC) ($117) ($107) ($70) ($16) $67 $187 $342 $480 $639 $723 $802 $875 $936 $980 76% NM (Less): D&A (10) (13) (16) (19) (21) (27) (32) (38) (45) (50) (53) (57) (60) (60) Operating Profit ($126) ($119) ($85) ($35) $46 $160 $310 $441 $594 $673 $749 $818 $876 $919 (1) (Less): Taxes (Excl. NOLs) – – – – (13) (45) (87) (124) (166) (188) (210) (229) (245) (257) NOPAT ($126) ($119) ($85) ($35) $33 $115 $223 $318 $428 $485 $539 $589 $631 $662 Plus: D&A 10 13 16 19 21 27 32 38 45 50 53 57 60 60 (Less): Capex (10) (15) (15) (15) (50) (40) (40) (45) (50) (51) (44) (35) (24) (10) (Less): Δ in NWC 2 (3) 18 0 2 1 1 (0) (7) (7) (7) (6) (5) (4) UFCF ($125) ($124) ($66) ($31) $6 $103 $216 $311 $415 $477 $541 $604 $661 $708 Memo: 3Q-4Q'26 uFCF ($63) Impact from NOLs – – – – 9 27 47 68 35 – – – – – (2) Impact of Capital Raises – (27) – (55) – – – – – – – – – – Implied Enterprise Value ($bn) Implied Share Price Implied Terminal EV / LTM Sales PGR PGR PGRPGR 3.0% 4.0% 5.0% 3.0% 4.0% 5.0% 3.0% 4.0% 5.0% 16.5% $1.4 $1.5 $1.6 16.5% $13.75 $14.25 $14.85 16.5% 1.7x 1.8x 2.0x 17.8% 1.2 1.2 1.3 17.8% 11.95 12.30 12.75 17.8% 1.5x 1.6x 1.8x 19.0% 1.0 1.0 1.1 19.0% 10.45 10.75 11.05 19.0% 1.4x 1.5x 1.6x Source: Company filings, FactSet and Pelican Management. Notes: Dollars in millions, except for per share amounts and where otherwise stated. Share prices rounded to nearest $0.05. DCF analysis assumes valuation as of June 30, 2026 using mid-year convention applied to projected free cash flows. Implied share price reflects estimated net cash balance of $208mm as of 6/30/26 and $75mm in net proceeds from 2026 raise assuming issuance at current share price, with 10% discount and 5% spread. Fully diluted shares underlying the analysis 16 from Pelican management based on basic shares of 106.0mm as of 5/31/26 and dilution under treasury stock method (TSM) of 15.6mm options with a weighted-average exercise price (WAEP) of $5.19, 0.6mm RSUs, and 0.6mm PSUs all as of 5/31/26. (1) Reflects 29.8% tax rate applied to operating profit. (2) Reflects impact of $150mm raise in 2027 and $300mm raise in 2029, both assuming 10% discount and 5% spread. The $75mm equity raise in 2026 at 10% discount to current share price assuming 5% spread is treated as dilutive. WACC WACC WACC
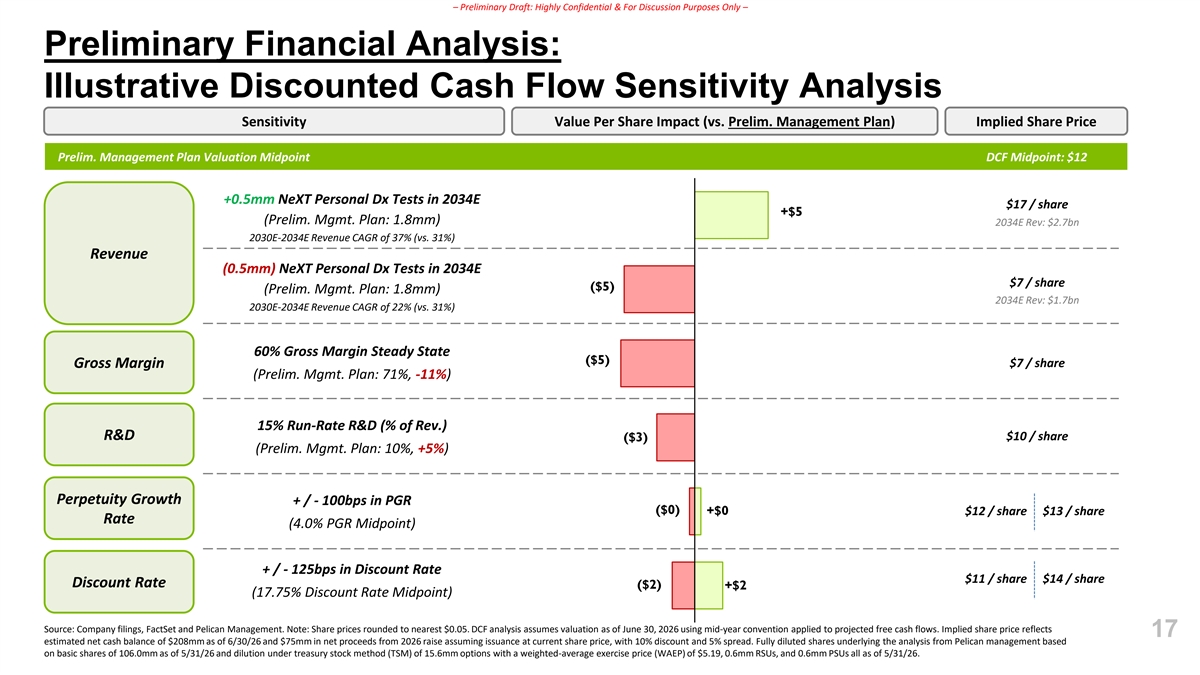
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Financial Analysis: Illustrative Discounted Cash Flow Sensitivity Analysis Sensitivity Value Per Share Impact (vs. Prelim. Management Plan) Implied Share Price Prelim. Management Plan Valuation Midpoint DCF Midpoint: $12 +0.5mm NeXT Personal Dx Tests in 2034E $17 / share +$5 (Prelim. Mgmt. Plan: 1.8mm) 2034E Rev: $2.7bn 2030E-2034E Revenue CAGR of 37% (vs. 31%) Revenue (0.5mm) NeXT Personal Dx Tests in 2034E $7 / share ($5) (Prelim. Mgmt. Plan: 1.8mm) 2034E Rev: $1.7bn 2030E-2034E Revenue CAGR of 22% (vs. 31%) 60% Gross Margin Steady State ($5) Gross Margin $7 / share (Prelim. Mgmt. Plan: 71%, -11%) 15% Run-Rate R&D (% of Rev.) R&D $10 / share ($3) (Prelim. Mgmt. Plan: 10%, +5%) Perpetuity Growth + / - 100bps in PGR ($0) +$0 $12 / share $13 / share Rate (4.0% PGR Midpoint) + / - 125bps in Discount Rate $11 / share $14 / share Discount Rate ($2) +$2 (17.75% Discount Rate Midpoint) Source: Company filings, FactSet and Pelican Management. Note: Share prices rounded to nearest $0.05. DCF analysis assumes valuation as of June 30, 2026 using mid-year convention applied to projected free cash flows. Implied share price reflects 17 estimated net cash balance of $208mm as of 6/30/26 and $75mm in net proceeds from 2026 raise assuming issuance at current share price, with 10% discount and 5% spread. Fully diluted shares underlying the analysis from Pelican management based on basic shares of 106.0mm as of 5/31/26 and dilution under treasury stock method (TSM) of 15.6mm options with a weighted-average exercise price (WAEP) of $5.19, 0.6mm RSUs, and 0.6mm PSUs all as of 5/31/26.
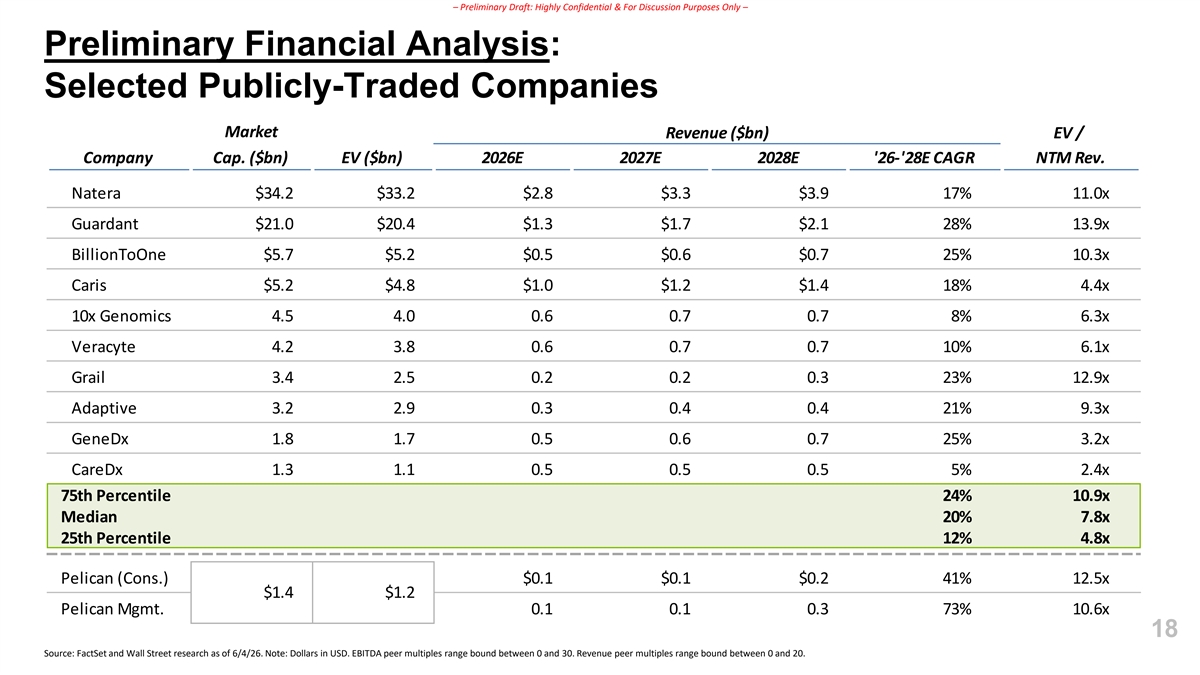
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Financial Analysis: Selected Publicly-Traded Companies Market Revenue ($bn) EV / Company Cap. ($bn) EV ($bn) 2026E 2027E 2028E '26-'28E CAGR NTM Rev. Natera $34.2 $33.2 $2.8 $3.3 $3.9 17% 11.0x Guardant $21.0 $20.4 $1.3 $1.7 $2.1 28% 13.9x BillionToOne $5.7 $5.2 $0.5 $0.6 $0.7 25% 10.3x Caris $5.2 $4.8 $1.0 $1.2 $1.4 18% 4.4x 10x Genomics 4.5 4.0 0.6 0.7 0.7 8% 6.3x Veracyte 4.2 3.8 0.6 0.7 0.7 10% 6.1x Grail 3.4 2.5 0.2 0.2 0.3 23% 12.9x Adaptive 3.2 2.9 0.3 0.4 0.4 21% 9.3x GeneDx 1.8 1.7 0.5 0.6 0.7 25% 3.2x CareDx 1.3 1.1 0.5 0.5 0.5 5% 2.4x 75th Percentile 24% 10.9x Median 20% 7.8x 25th Percentile 12% 4.8x Pelican (Cons.) $0.1 $0.1 $0.2 41% 12.5x $1.4 $1.2 Pelican Mgmt. 0.1 0.1 0.3 73% 10.6x 18 Source: FactSet and Wall Street research as of 6/4/26. Note: Dollars in USD. EBITDA peer multiples range bound between 0 and 30. Revenue peer multiples range bound between 0 and 20.
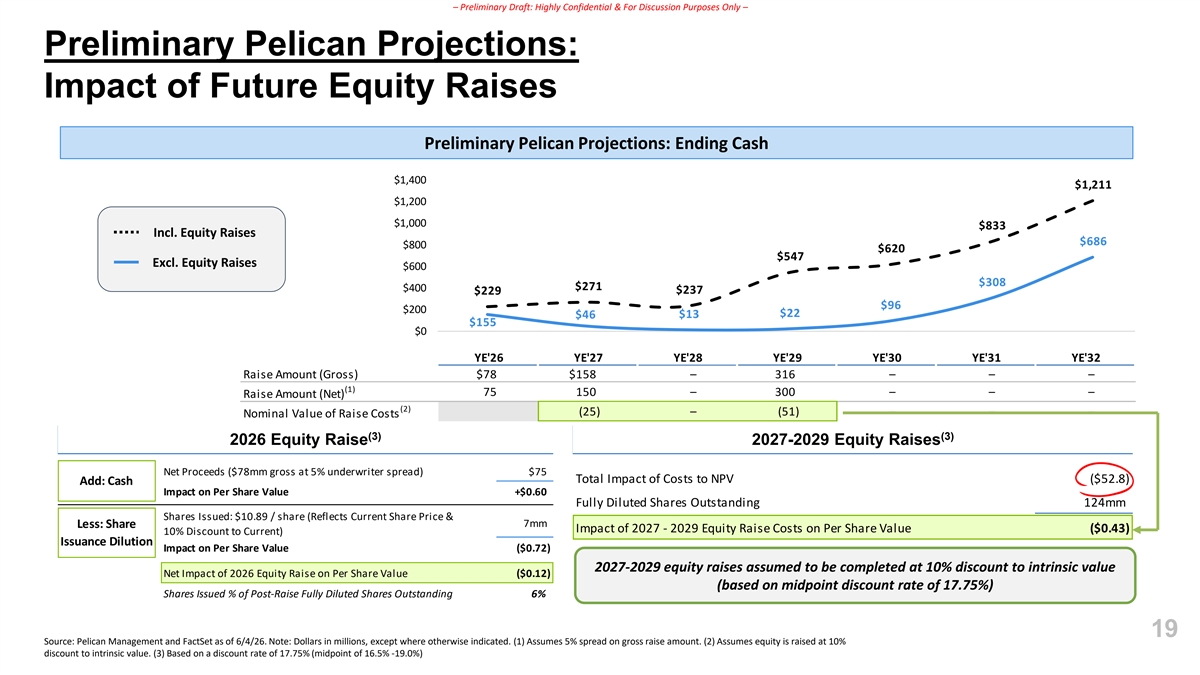
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Pelican Projections: Impact of Future Equity Raises Preliminary Pelican Projections: Ending Cash $1,400 $1,211 $1,200 $1,000 $833 Incl. Equity Raises $686 $800 $620 $547 Excl. Equity Raises $600 $308 $271 $400 $237 $229 $96 $200 $22 $46 $13 $155 $0 YE'26 YE'27 YE'28 YE'29 YE'30 YE'31 YE'32 Raise Amount (Gross) $78 $158 – 316 – – – (1) 75 150 – 300 – – – Raise Amount (Net) (2) (25) – (51) – – – Nominal Value of Raise Costs (3) (3) 2026 Equity Raise 2027-2029 Equity Raises Net Proceeds ($78mm gross at 5% underwriter spread) $75 Total Impact of Costs to NPV ($52.8) Add: Cash Impact on Per Share Value +$0.60 Fully Diluted Shares Outstanding 124mm Shares Issued: $10.89 / share (Reflects Current Share Price & 7mm Less: Share Impact of 2027 - 2029 Equity Raise Costs on Per Share Value ($0.43) 10% Discount to Current) Issuance Dilution Impact on Per Share Value ($0.72) 2027-2029 equity raises assumed to be completed at 10% discount to intrinsic value Net Impact of 2026 Equity Raise on Per Share Value ($0.12) (based on midpoint discount rate of 17.75%) Shares Issued % of Post-Raise Fully Diluted Shares Outstanding 6% 19 Source: Pelican Management and FactSet as of 6/4/26. Note: Dollars in millions, except where otherwise indicated. (1) Assumes 5% spread on gross raise amount. (2) Assumes equity is raised at 10% discount to intrinsic value. (3) Based on a discount rate of 17.75% (midpoint of 16.5% -19.0%)
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary TD Cowen Pelican Financial Analysis 20
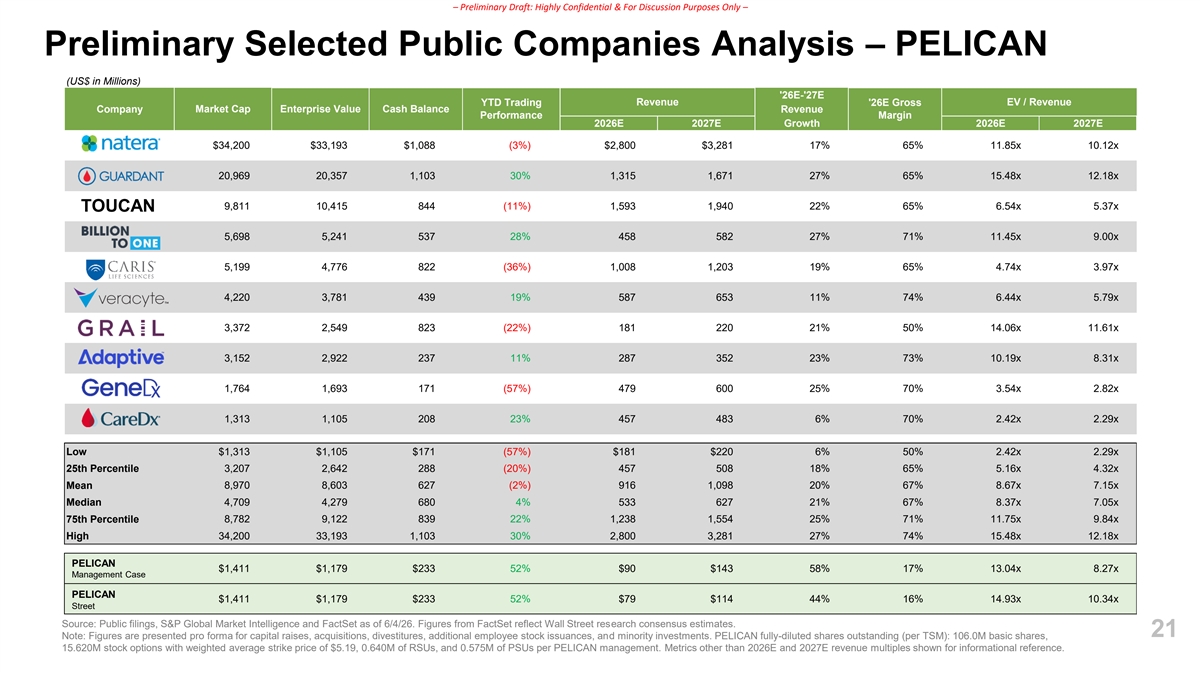
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Selected Public Companies Analysis – PELICAN (US$ in Millions) '26E-'27E Revenue EV / Revenue YTD Trading '26E Gross Company Market Cap Enterprise Value Cash Balance Revenue Performance Margin 2026E 2027E Growth 2026E 2027E $34,200 $33,193 $1,088 (3%) $2,800 $3,281 17% 65% 11.85x 10.12x 20,969 20,357 1,103 30% 1,315 1,671 27% 65% 15.48x 12.18x 9,811 10,415 844 (11%) 1,593 1,940 22% 65% 6.54x 5.37x TOUCAN 5,698 5,241 537 28% 458 582 27% 71% 11.45x 9.00x 5,199 4,776 822 (36%) 1,008 1,203 19% 65% 4.74x 3.97x 4,220 3,781 439 19% 587 653 11% 74% 6.44x 5.79x 3,372 2,549 823 (22%) 181 220 21% 50% 14.06x 11.61x 3,152 2,922 237 11% 287 352 23% 73% 10.19x 8.31x 1,764 1,693 171 (57%) 479 600 25% 70% 3.54x 2.82x 1,313 1,105 208 23% 457 483 6% 70% 2.42x 2.29x Low $1,313 $1,105 $171 (57%) $181 $220 6% 50% 2.42x 2.29x 25th Percentile 3,207 2,642 288 (20%) 457 508 18% 65% 5.16x 4.32x Mean 8,970 8,603 627 (2%) 916 1,098 20% 67% 8.67x 7.15x Median 4,709 4,279 680 4% 533 627 21% 67% 8.37x 7.05x 75th Percentile 8,782 9,122 839 22% 1,238 1,554 25% 71% 11.75x 9.84x High 34,200 33,193 1,103 30% 2,800 3,281 27% 74% 15.48x 12.18x PELICAN $1,411 $1,179 $233 52% $90 $143 58% 17% 13.04x 8.27x Management Case PELICAN $1,411 $1,179 $233 52% $79 $114 44% 16% 14.93x 10.34x Street Source: Public filings, S&P Global Market Intelligence and FactSet as of 6/4/26. Figures from FactSet reflect Wall Street research consensus estimates. 21 Note: Figures are presented pro forma for capital raises, acquisitions, divestitures, additional employee stock issuances, and minority investments. PELICAN fully-diluted shares outstanding (per TSM): 106.0M basic shares, 15.620M stock options with weighted average strike price of $5.19, 0.640M of RSUs, and 0.575M of PSUs per PELICAN management. Metrics other than 2026E and 2027E revenue multiples shown for informational reference.
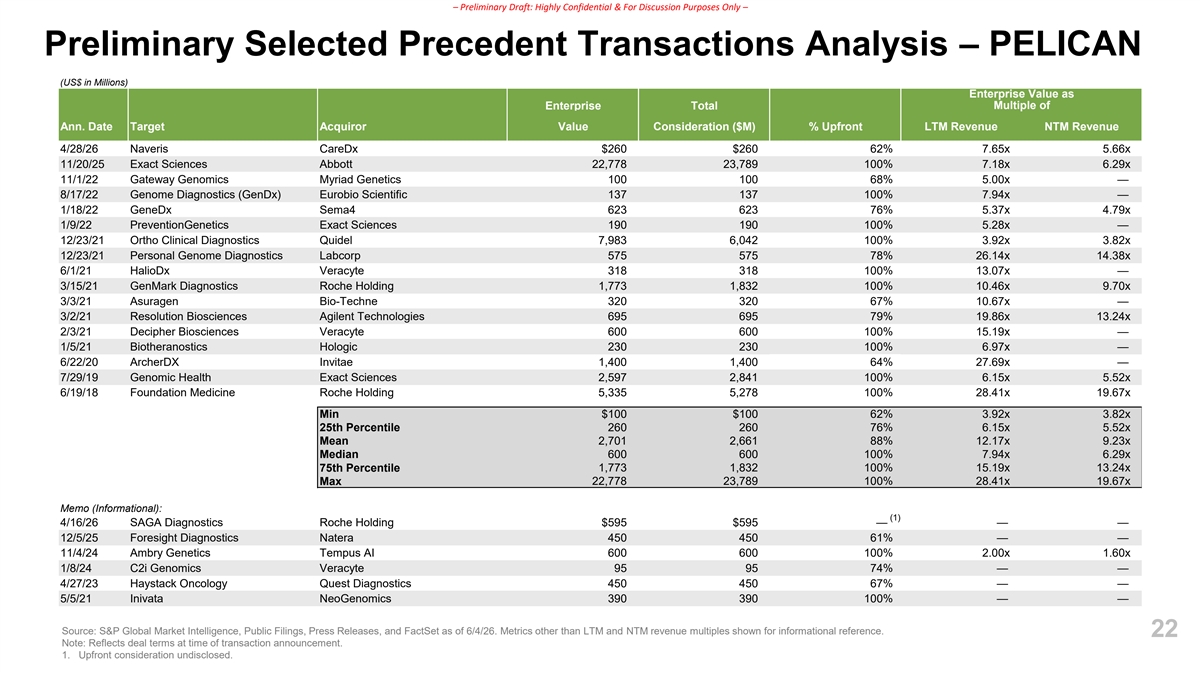
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Selected Precedent Transactions Analysis – PELICAN (US$ in Millions) Enterprise Value as Multiple of Enterprise Total Ann. Date Target Acquiror Value Consideration ($M) % Upfront LTM Revenue NTM Revenue 4/28/26 Naveris CareDx $260 $260 62% 7.65x 5.66x 11/20/25 Exact Sciences Abbott 22,778 23,789 100% 7.18x 6.29x 11/1/22 Gateway Genomics Myriad Genetics 100 100 68% 5.00x — 8/17/22 Genome Diagnostics (GenDx) Eurobio Scientific 137 137 100% 7.94x — 1/18/22 GeneDx Sema4 623 623 76% 5.37x 4.79x 1/9/22 PreventionGenetics Exact Sciences 190 190 100% 5.28x — 12/23/21 Ortho Clinical Diagnostics Quidel 7,983 6,042 100% 3.92x 3.82x 12/23/21 Personal Genome Diagnostics Labcorp 575 575 78% 26.14x 14.38x 6/1/21 HalioDx Veracyte 318 318 100% 13.07x — 3/15/21 GenMark Diagnostics Roche Holding 1,773 1,832 100% 10.46x 9.70x 3/3/21 Asuragen Bio-Techne 320 320 67% 10.67x — 3/2/21 Resolution Biosciences Agilent Technologies 695 695 79% 19.86x 13.24x 2/3/21 Decipher Biosciences Veracyte 600 600 100% 15.19x — 1/5/21 Biotheranostics Hologic 230 230 100% 6.97x — 6/22/20 ArcherDX Invitae 1,400 1,400 64% 27.69x — 7/29/19 Genomic Health Exact Sciences 2,597 2,841 100% 6.15x 5.52x 6/19/18 Foundation Medicine Roche Holding 5,335 5,278 100% 28.41x 19.67x Min $100 $100 62% 3.92x 3.82x 25th Percentile 260 260 76% 6.15x 5.52x Mean 2,701 2,661 88% 12.17x 9.23x Median 600 600 100% 7.94x 6.29x 75th Percentile 1,773 1,832 100% 15.19x 13.24x Max 22,778 23,789 100% 28.41x 19.67x Memo (Informational): (1) 4/16/26 SAGA Diagnostics Roche Holding $595 $595 — — — 12/5/25 Foresight Diagnostics Natera 450 450 61% — — 11/4/24 Ambry Genetics Tempus AI 600 600 100% 2.00x 1.60x 1/8/24 C2i Genomics Veracyte 95 95 74% — — 4/27/23 Haystack Oncology Quest Diagnostics 450 450 67% — — 5/5/21 Inivata NeoGenomics 390 390 100% — — Source: S&P Global Market Intelligence, Public Filings, Press Releases, and FactSet as of 6/4/26. Metrics other than LTM and NTM revenue multiples shown for informational reference. 22 Note: Reflects deal terms at time of transaction announcement. 1. Upfront consideration undisclosed.
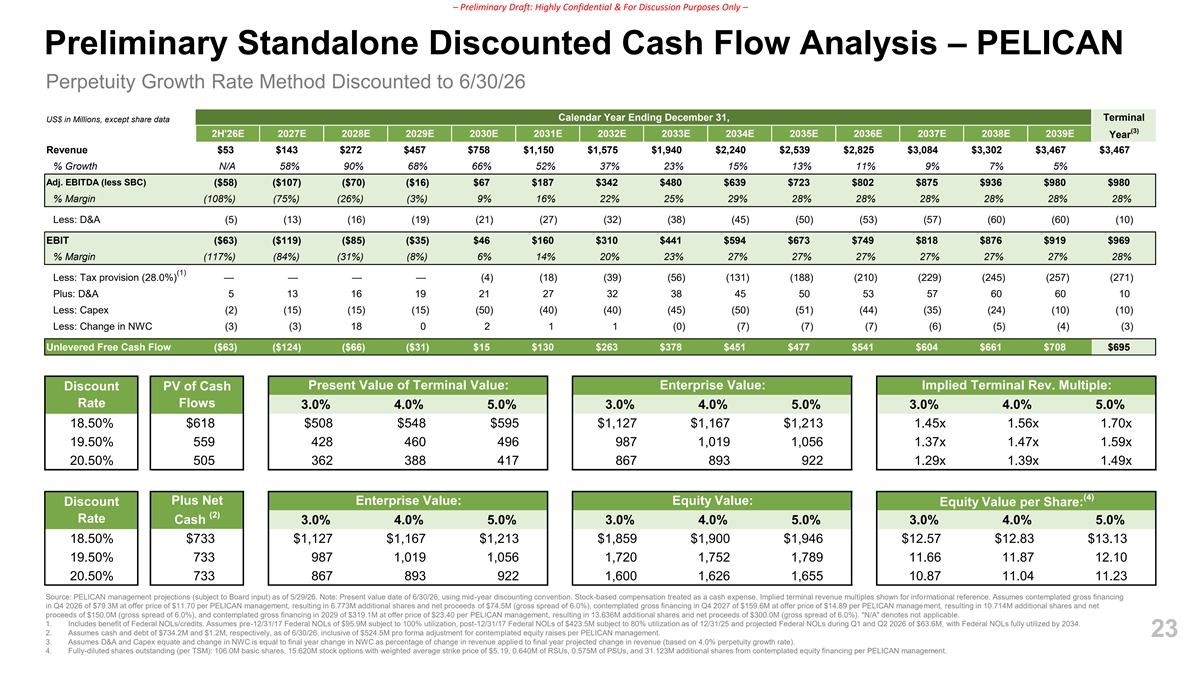
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Standalone Discounted Cash Flow Analysis – PELICAN Perpetuity Growth Rate Method Discounted to 6/30/26 Calendar Year Ending December 31, Terminal US$ in Millions, except share data (3) 2H'26E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E 2036E 2037E 2038E 2039E Year Revenue $53 $143 $272 $457 $758 $1,150 $1,575 $1,940 $2,240 $2,539 $2,825 $3,084 $3,302 $3,467 $3,467 % Growth N/A 58% 90% 68% 66% 52% 37% 23% 15% 13% 11% 9% 7% 5% Adj. EBITDA (less SBC) ($58) ($107) ($70) ($16) $67 $187 $342 $480 $639 $723 $802 $875 $936 $980 $980 % Margin (108%) (75%) (26%) (3%) 9% 16% 22% 25% 29% 28% 28% 28% 28% 28% 28% Less: D&A (5) (13) (16) (19) (21) (27) (32) (38) (45) (50) (53) (57) (60) (60) (10) EBIT ($63) ($119) ($85) ($35) $46 $160 $310 $441 $594 $673 $749 $818 $876 $919 $969 % Margin (117%) (84%) (31%) (8%) 6% 14% 20% 23% 27% 27% 27% 27% 27% 27% 28% (1) Less: Tax provision (28.0%) — — — — (4) (18) (39) (56) (131) (188) (210) (229) (245) (257) (271) Plus: D&A 5 13 16 19 21 27 32 38 45 50 53 57 60 60 10 Less: Capex (2) (15) (15) (15) (50) (40) (40) (45) (50) (51) (44) (35) (24) (10) (10) Less: Change in NWC (3) (3) 18 0 2 1 1 (0) (7) (7) (7) (6) (5) (4) (3) Unlevered Free Cash Flow ($63) ($124) ($66) ($31) $15 $130 $263 $378 $451 $477 $541 $604 $661 $708 $695 Present Value of Terminal Value: Enterprise Value: Implied Terminal Rev. Multiple: Discount PV of Cash Rate Flows 3.0% 4.0% 5.0% 3.0% 4.0% 5.0% 3.0% 4.0% 5.0% 18.50% $618 $508 $548 $595 $1,127 $1,167 $1,213 1.45x 1.56x 1.70x 19.50% 559 428 460 496 987 1,019 1,056 1.37x 1.47x 1.59x 20.50% 505 362 388 417 867 893 922 1.29x 1.39x 1.49x (4) Plus Net Enterprise Value: Equity Value: Discount Equity Value per Share: (2) Rate Cash 3.0% 4.0% 5.0% 3.0% 4.0% 5.0% 3.0% 4.0% 5.0% 18.50% $733 $1,127 $1,167 $1,213 $1,859 $1,900 $1,946 $12.57 $12.83 $13.13 19.50% 733 987 1,019 1,056 1,720 1,752 1,789 11.66 11.87 12.10 20.50% 733 867 893 922 1,600 1,626 1,655 10.87 11.04 11.23 Source: PELICAN management projections (subject to Board input) as of 5/29/26. Note: Present value date of 6/30/26, using mid-year discounting convention. Stock-based compensation treated as a cash expense. Implied terminal revenue multiples shown for informational reference. Assumes contemplated gross financing in Q4 2026 of $79.3M at offer price of $11.70 per PELICAN management, resulting in 6.773M additional shares and net proceeds of $74.5M (gross spread of 6.0%), contemplated gross financing in Q4 2027 of $159.6M at offer price of $14.89 per PELICAN management, resulting in 10.714M additional shares and net proceeds of $150.0M (gross spread of 6.0%), and contemplated gross financing in 2029 of $319.1M at offer price of $23.40 per PELICAN management, resulting in 13.636M additional shares and net proceeds of $300.0M (gross spread of 6.0%). N/A denotes not applicable. 1. Includes benefit of Federal NOLs/credits. Assumes pre-12/31/17 Federal NOLs of $95.9M subject to 100% utilization, post-12/31/17 Federal NOLs of $423.5M subject to 80% utilization as of 12/31/25 and projected Federal NOLs during Q1 and Q2 2026 of $63.6M, with Federal NOLs fully utilized by 2034. 2. Assumes cash and debt of $734.2M and $1.2M, respectively, as of 6/30/26, inclusive of $524.5M pro forma adjustment for contemplated equity raises per PELICAN management. 23 3. Assumes D&A and Capex equate and change in NWC is equal to final year change in NWC as percentage of change in revenue applied to final year projected change in revenue (based on 4.0% perpetuity growth rate). 4. Fully-diluted shares outstanding (per TSM): 106.0M basic shares, 15.620M stock options with weighted average strike price of $5.19, 0.640M of RSUs, 0.575M of PSUs, and 31.123M additional shares from contemplated equity financing per PELICAN management.
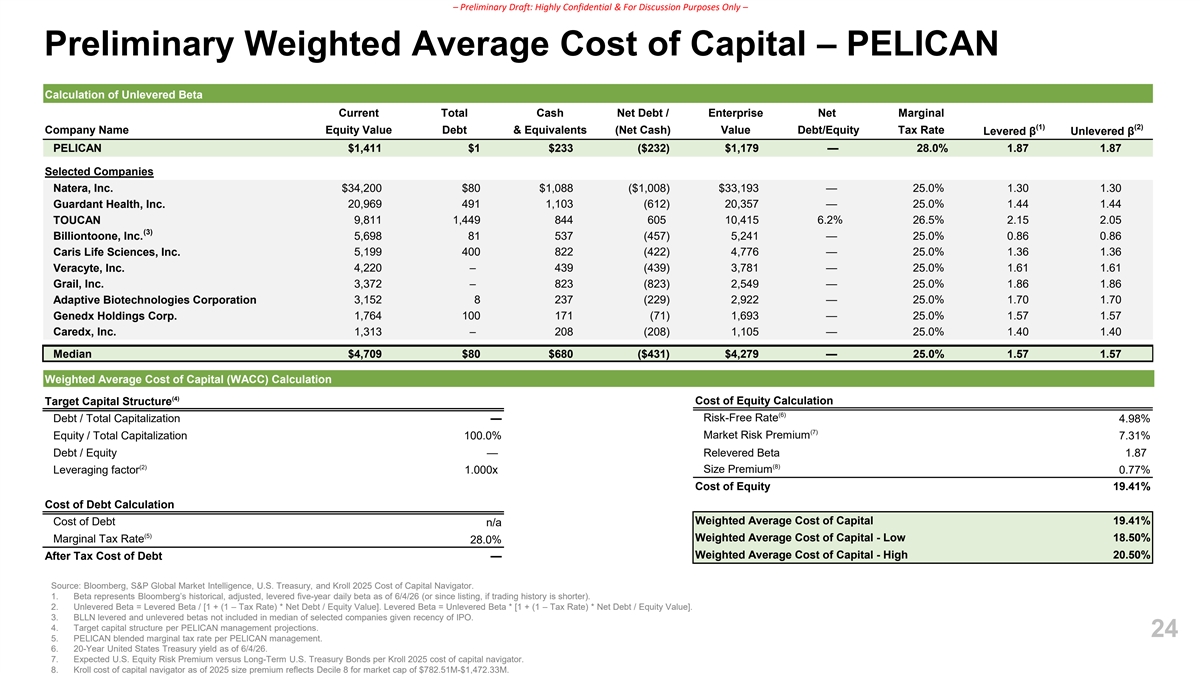
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Weighted Average Cost of Capital – PELICAN Calculation of Unlevered Beta Current Total Cash Net Debt / Enterprise Net Marginal (1) (2) Company Name Equity Value Debt & Equivalents (Net Cash) Value Debt/Equity Tax Rate Levered β Unlevered β PELICAN $1,411 $1 $233 ($232) $1,179 — 28.0% 1.87 1.87 Selected Companies Natera, Inc. $34,200 $80 $1,088 ($1,008) $33,193 — 25.0% 1.30 1.30 20,969 491 1,103 (612) 20,357 — 25.0% 1.44 1.44 Guardant Health, Inc. TOUCAN 9,811 1,449 844 605 10,415 6.2% 26.5% 2.15 2.05 (3) Billiontoone, Inc. 5,698 81 537 (457) 5,241 — 25.0% 0.86 0.86 Caris Life Sciences, Inc. 5,199 400 822 (422) 4,776 — 25.0% 1.36 1.36 4,220 – 439 (439) 3,781 — 25.0% 1.61 1.61 Veracyte, Inc. Grail, Inc. 3,372 – 823 (823) 2,549 — 25.0% 1.86 1.86 Adaptive Biotechnologies Corporation 3,152 8 237 (229) 2,922 — 25.0% 1.70 1.70 Genedx Holdings Corp. 1,764 100 171 (71) 1,693 — 25.0% 1.57 1.57 Caredx, Inc. 1,313 – 208 (208) 1,105 — 25.0% 1.40 1.40 Median $4,709 $80 $680 ($431) $4,279 — 25.0% 1.57 1.57 Weighted Average Cost of Capital (WACC) Calculation (4) Target Capital Structure Cost of Equity Calculation (6) Risk-Free Rate Debt / Total Capitalization — 4.98% (7) Market Risk Premium Equity / Total Capitalization 100.0% 7.31% Debt / Equity — Relevered Beta 1.87 (8) (2) Leveraging factor 1.000x Size Premium 0.77% Cost of Equity 19.41% Cost of Debt Calculation Cost of Debt Weighted Average Cost of Capital 19.41% n/a (5) Weighted Average Cost of Capital - Low 18.50% Marginal Tax Rate 28.0% Weighted Average Cost of Capital - High 20.50% After Tax Cost of Debt — Source: Bloomberg, S&P Global Market Intelligence, U.S. Treasury, and Kroll 2025 Cost of Capital Navigator. 1. Beta represents Bloomberg’s historical, adjusted, levered five-year daily beta as of 6/4/26 (or since listing, if trading history is shorter). 2. Unlevered Beta = Levered Beta / [1 + (1 – Tax Rate) * Net Debt / Equity Value]. Levered Beta = Unlevered Beta * [1 + (1 – Tax Rate) * Net Debt / Equity Value]. 3. BLLN levered and unlevered betas not included in median of selected companies given recency of IPO. 4. Target capital structure per PELICAN management projections. 24 5. PELICAN blended marginal tax rate per PELICAN management. 6. 20-Year United States Treasury yield as of 6/4/26. 7. Expected U.S. Equity Risk Premium versus Long-Term U.S. Treasury Bonds per Kroll 2025 cost of capital navigator. 8. Kroll cost of capital navigator as of 2025 size premium reflects Decile 8 for market cap of $782.51M-$1,472.33M.
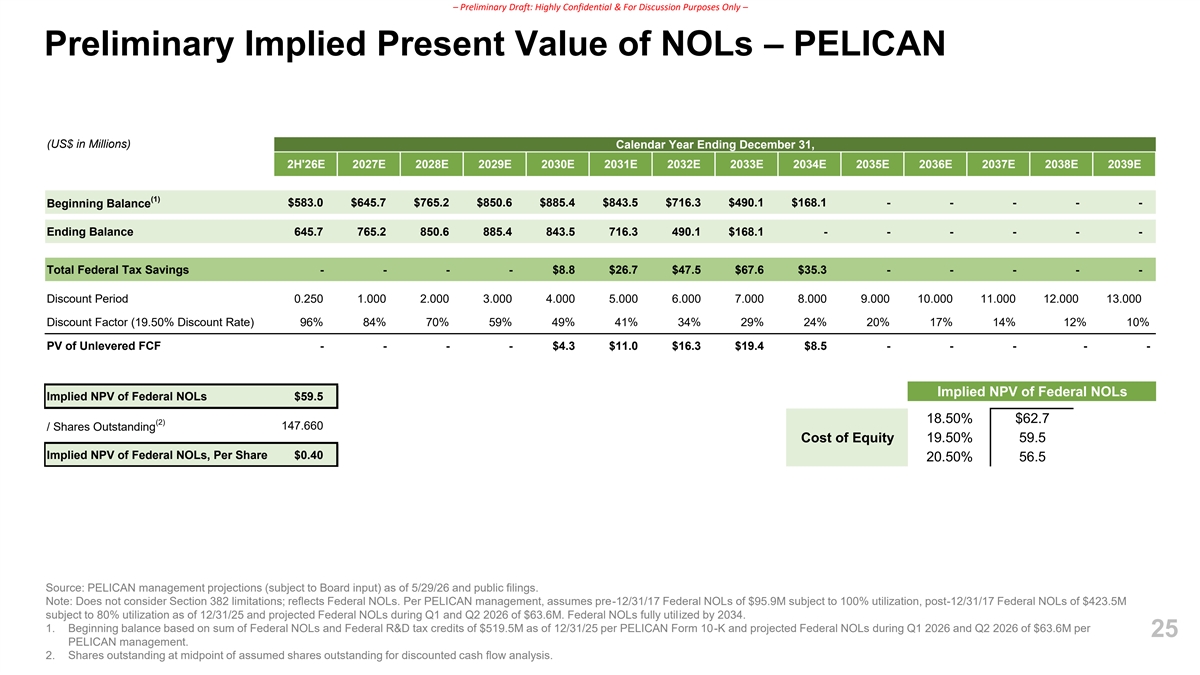
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Implied Present Value of NOLs – PELICAN (US$ in Millions) Calendar Year Ending December 31, 2H'26E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E 2036E 2037E 2038E 2039E (1) $583.0 $645.7 $765.2 $850.6 $885.4 $843.5 $716.3 $490.1 $168.1 - - - - - Beginning Balance Ending Balance 645.7 765.2 850.6 885.4 843.5 716.3 490.1 $168.1 - - - - - - Total Federal Tax Savings - - - - $8.8 $26.7 $47.5 $67.6 $35.3 - - - - - Discount Period 0.250 1.000 2.000 3.000 4.000 5.000 6.000 7.000 8.000 9.000 10.000 11.000 12.000 13.000 Discount Factor (19.50% Discount Rate) 96% 84% 70% 59% 49% 41% 34% 29% 24% 20% 17% 14% 12% 10% PV of Unlevered FCF - - - - $4.3 $11.0 $16.3 $19.4 $8.5 - - - - - Implied NPV of Federal NOLs Implied NPV of Federal NOLs $59.5 18.50% $62.7 (2) 147.660 / Shares Outstanding Cost of Equity 19.50% 59.5 Implied NPV of Federal NOLs, Per Share $0.40 20.50% 56.5 Source: PELICAN management projections (subject to Board input) as of 5/29/26 and public filings. Note: Does not consider Section 382 limitations; reflects Federal NOLs. Per PELICAN management, assumes pre-12/31/17 Federal NOLs of $95.9M subject to 100% utilization, post-12/31/17 Federal NOLs of $423.5M subject to 80% utilization as of 12/31/25 and projected Federal NOLs during Q1 and Q2 2026 of $63.6M. Federal NOLs fully utilized by 2034. 1. Beginning balance based on sum of Federal NOLs and Federal R&D tax credits of $519.5M as of 12/31/25 per PELICAN Form 10-K and projected Federal NOLs during Q1 2026 and Q2 2026 of $63.6M per 25 PELICAN management. 2. Shares outstanding at midpoint of assumed shares outstanding for discounted cash flow analysis.
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Toucan Public Market Perspectives and Preliminary Financial Projections 26
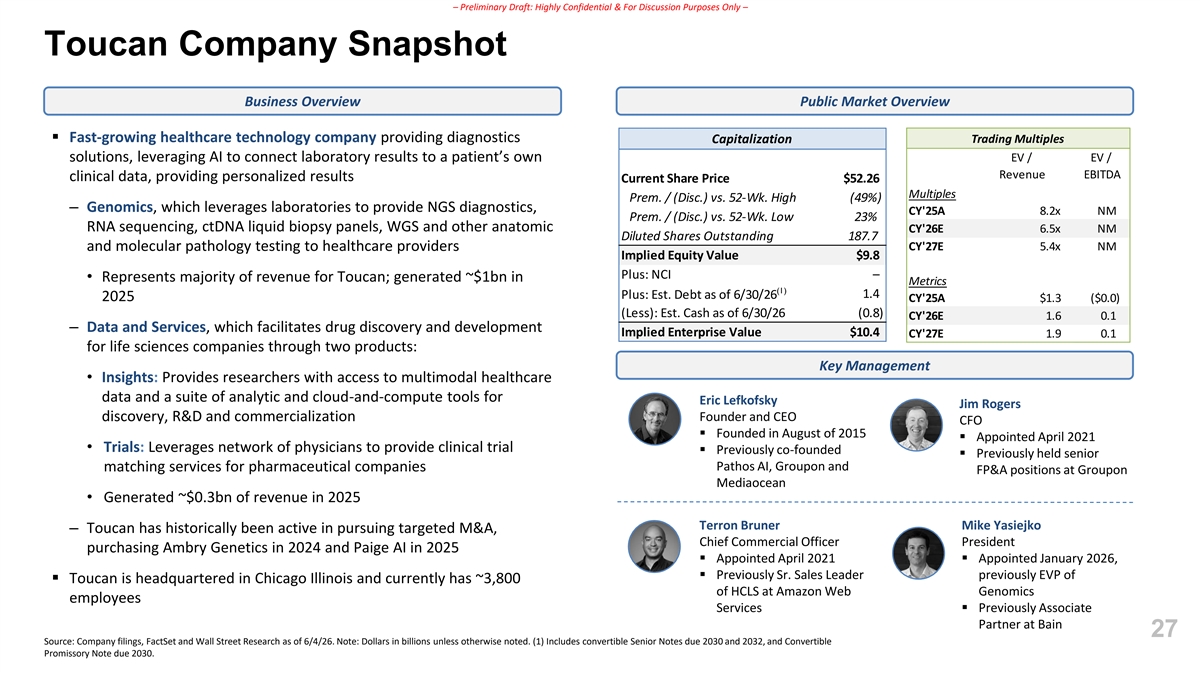
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Toucan Company Snapshot Business Overview Public Market Overview ▪ Fast-growing healthcare technology company providing diagnostics Trading Multiples Capitalization solutions, leveraging AI to connect laboratory results to a patient’s own EV / EV / Revenue EBITDA clinical data, providing personalized results Current Share Price $52.26 Multiples Prem. / (Disc.) vs. 52-Wk. High (49%) – Genomics, which leverages laboratories to provide NGS diagnostics, CY'25A 8.2x NM Prem. / (Disc.) vs. 52-Wk. Low 23% RNA sequencing, ctDNA liquid biopsy panels, WGS and other anatomic CY'26E 6.5x NM Diluted Shares Outstanding 187.7 CY'27E 5.4x NM and molecular pathology testing to healthcare providers Implied Equity Value $9.8 Plus: NCI – • Represents majority of revenue for Toucan; generated ~$1bn in Metrics (1) Plus: Est. Debt as of 6/30/26 1.4 2025 CY'25A $1.3 ($0.0) (Less): Est. Cash as of 6/30/26 (0.8) CY'26E 1.6 0.1 – Data and Services, which facilitates drug discovery and development Implied Enterprise Value $10.4 CY'27E 1.9 0.1 for life sciences companies through two products: Key Management Financial Profile • Insights: Provides researchers with access to multimodal healthcare ’24A-’29E CAGR Sales by Segment ($mm) data and a suite of analytic and cloud-and-compute tools for Eric Lefkofsky Jim Rogers +34% discovery, R&D and commercialization Founder and CEO CFO ▪ Founded in August of 2015 ▪ Appointed April 2021 +29% • Trials: Leverages network of physicians to provide clinical trial ▪ Previously co-founded ▪ Previously held senior + matching services for pharmaceutical companies Pathos AI, Groupon and FP&A positions at Groupon + Data and Mediaocean +36% Services • Generated ~$0.3bn of revenue in 2025 Terron Bruner Mike Yasiejko Genomics – Toucan has historically been active in pursuing targeted M&A, Chief Commercial Officer President purchasing Ambry Genetics in 2024 and Paige AI in 2025 ▪ Appointed April 2021▪ Appointed January 2026, WholeCo Growth %: ▪ Previously Sr. Sales Leader previously EVP of ▪ Toucan is headquartered in Chicago Illinois and currently has ~3,800 of HCLS at Amazon Web Genomics employees Genomics Growth %: Services▪ Previously Associate Partner at Bain 27 Source: Company filings, FactSet and Wall Street Research as of 6/4/26. Note: Dollars in billions unless otherwise noted. (1) Includes convertible Senior Notes due 2030 and 2032, and Convertible Promissory Note due 2030.
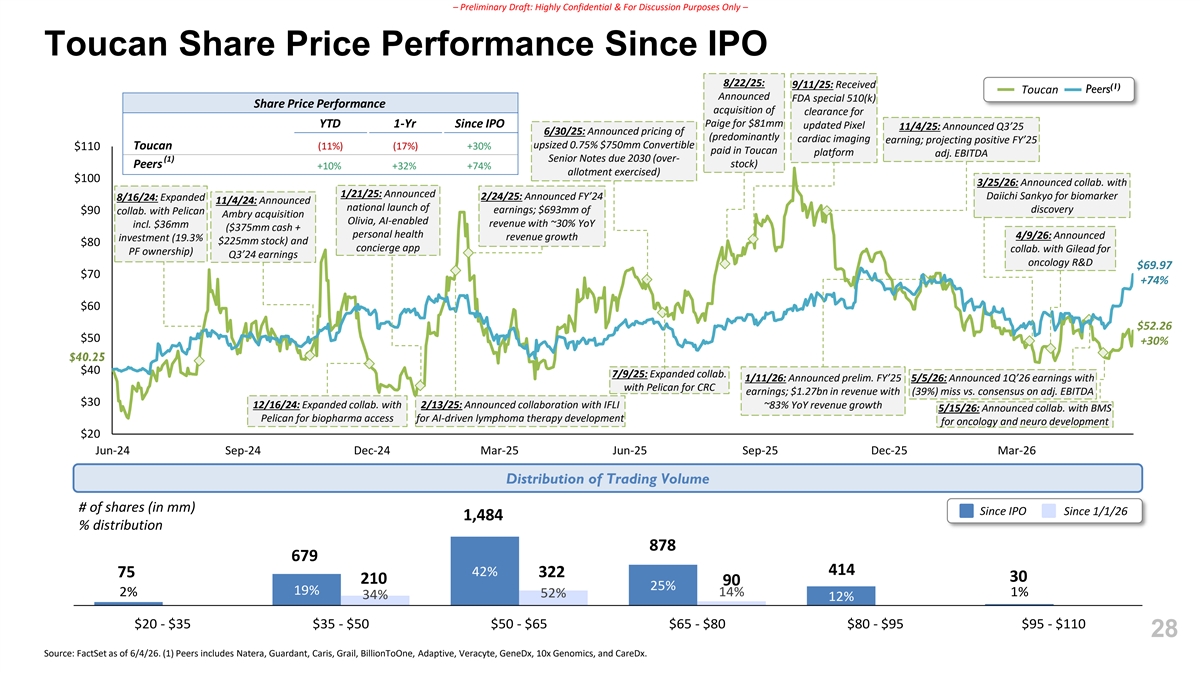
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Toucan Share Price Performance Since IPO 8/22/25: 9/11/25: Received (1) Toucan Peers Announced FDA special 510(k) Share Price Performance acquisition of clearance for YTD 1-Yr Since IPO Paige for $81mm updated Pixel 11/4/25: Announced Q3’25 6/30/25: Announced pricing of (predominantly cardiac imaging earning; projecting positive FY’25 upsized 0.75% $750mm Convertible $110 Toucan (11%) (17%) +30% paid in Toucan platform adj. EBITDA (1) Senior Notes due 2030 (over- stock) Peers +10% +32% +74% allotment exercised) $100 3/25/26: Announced collab. with 1/21/25: Announced 2/24/25: Announced FY’24 Daiichi Sankyo for biomarker 8/16/24: Expanded 11/4/24: Announced national launch of discovery $90 earnings; $693mm of collab. with Pelican Ambry acquisition Olivia, AI-enabled incl. $36mm revenue with ~30% YoY ($375mm cash + personal health 4/9/26: Announced revenue growth investment (19.3% $225mm stock) and $80 concierge app collab. with Gilead for PF ownership) Q3’24 earnings oncology R&D $69.97 $70 +74% $60 $52.26 $50 +30% $40.25 $40 7/9/25: Expanded collab. 1/11/26: Announced prelim. FY’25 5/5/26: Announced 1Q’26 earnings with with Pelican for CRC earnings; $1.27bn in revenue with (39%) miss vs. consensus on adj. EBITDA $30 12/16/24: Expanded collab. with 2/13/25: Announced collaboration with IFLI ~83% YoY revenue growth 5/15/26: Announced collab. with BMS Pelican for biopharma access for AI-driven lymphoma therapy development for oncology and neuro development $20 Jun-24 Sep-24 Dec-24 Mar-25 Jun-25 Sep-25 Dec-25 Mar-26 Distribution of Trading Volume # of shares (in mm) Since IPO Since 1/1/26 1,484 % distribution 878 679 414 42% 75 322 30 210 90 25% 19% 2% 14% 1% 52% 34% 12% $20 - $35 $35 - $50 $50 - $65 $65 - $80 $80 - $95 $95 - $110 28 Source: FactSet as of 6/4/26. (1) Peers includes Natera, Guardant, Caris, Grail, BillionToOne, Adaptive, Veracyte, GeneDx, 10x Genomics, and CareDx.
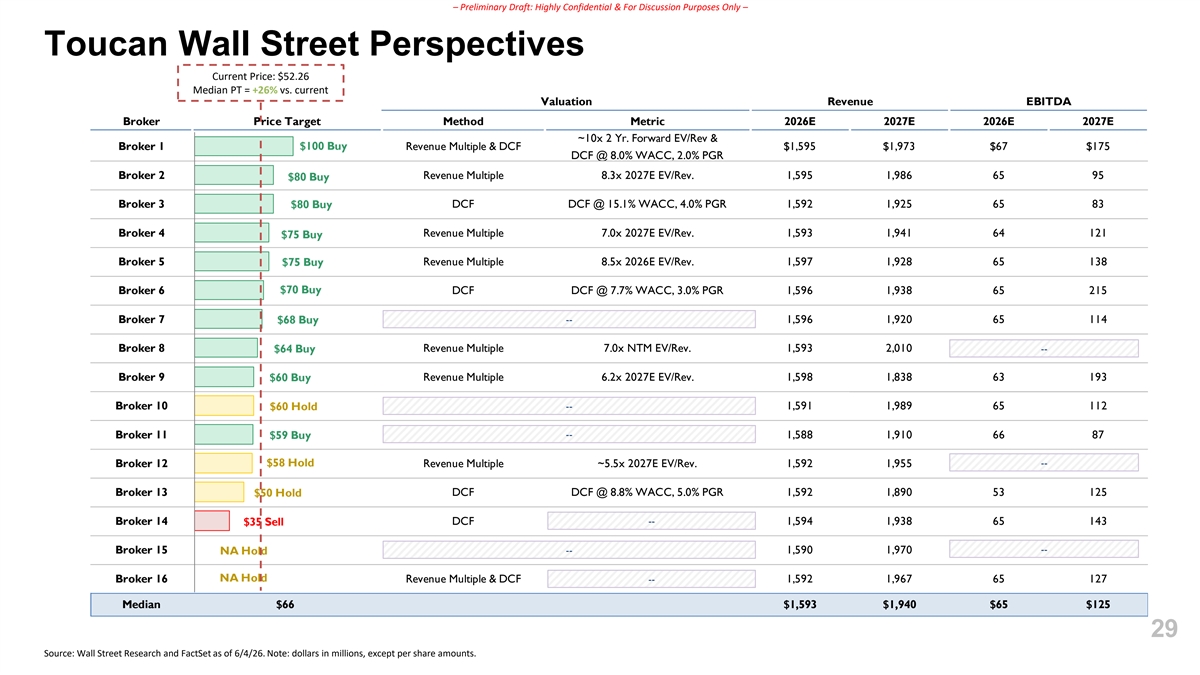
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Toucan Wall Street Perspectives Current Price: $52.26 Median PT = +26% vs. current Valuation Revenue EBITDA Broker Price Target Method Metric 2026E 2027E 2026E 2027E ~10x 2 Yr. Forward EV/Rev & Broker 1 $100 Buy Revenue Multiple & DCF $1,595 $1,973 $67 $175 DCF @ 8.0% WACC, 2.0% PGR Broker 2 Revenue Multiple 8.3x 2027E EV/Rev. 1,595 1,986 65 95 $80 Buy Broker 3 DCF DCF @ 15.1% WACC, 4.0% PGR 1,592 1,925 65 83 $80 Buy Broker 4 Revenue Multiple 7.0x 2027E EV/Rev. 1,593 1,941 64 121 $75 Buy Broker 5 Revenue Multiple 8.5x 2026E EV/Rev. 1,597 1,928 65 138 $75 Buy $70 Buy Broker 6 DCF DCF @ 7.7% WACC, 3.0% PGR 1,596 1,938 65 215 -- Broker 7 $68 Buy 1,596 1,920 65 114 Broker 8 $64 Buy Revenue Multiple 7.0x NTM EV/Rev. 1,593 2,010 -- -- -- Broker 9 $60 Buy Revenue Multiple 6.2x 2027E EV/Rev. 1,598 1,838 63 193 Broker 10 $60 Hold -- 1,591 1,989 65 112 -- Broker 11 $59 Buy 1,588 1,910 66 87 $58 Hold -- Broker 12 Revenue Multiple ~5.5x 2027E EV/Rev. 1,592 1,955 -- -- Broker 13 DCF DCF @ 8.8% WACC, 5.0% PGR 1,592 1,890 53 125 $50 Hold Broker 14 DCF -- -- 1,594 1,938 65 143 $35 Sell -- Broker 15 -- 1,590 1,970 -- -- NA Hold Broker 16 NA Hold Revenue Multiple & DCF -- -- 1,592 1,967 65 127 Median $66 $1,593 $1,940 $65 $125 29 Source: Wall Street Research and FactSet as of 6/4/26. Note: dollars in millions, except per share amounts.
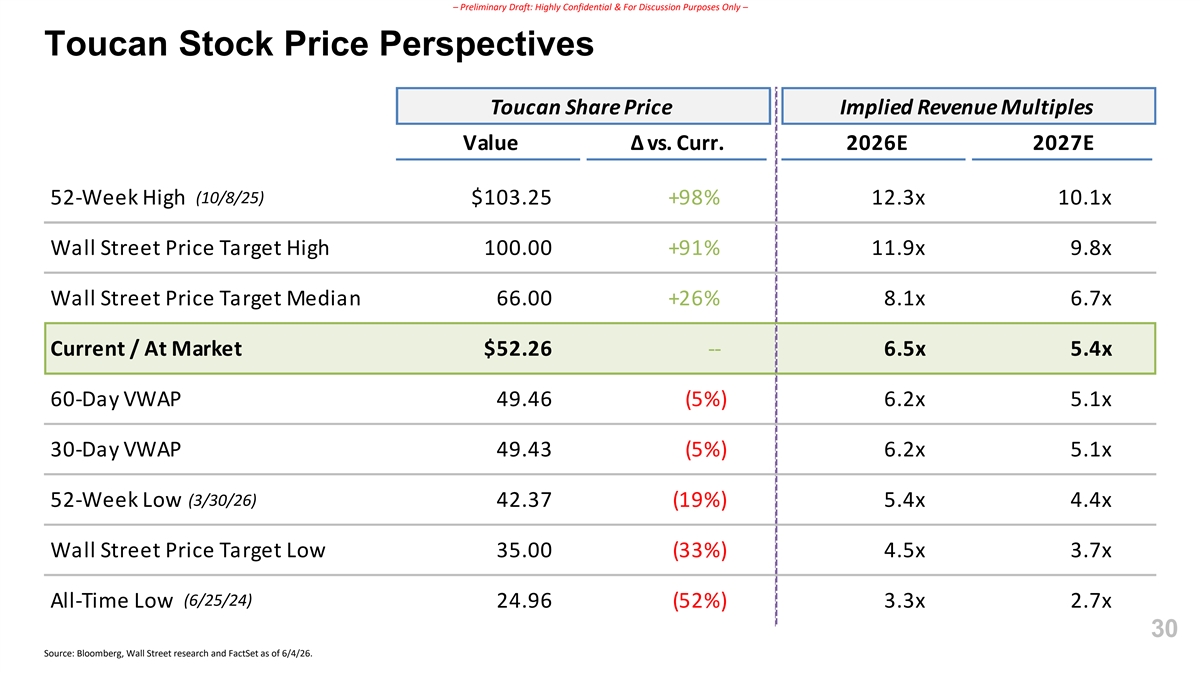
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Toucan Stock Price Perspectives Toucan Share Price Implied Revenue Multiples Value Δ vs. Curr. 2026E 2027E (10/8/25) 52-Week High $103.25 +98% 12.3x 10.1x Wall Street Price Target High 100.00 +91% 11.9x 9.8x Wall Street Price Target Median 66.00 +26% 8.1x 6.7x Current / At Market $52.26 -- 6.5x 5.4x 60-Day VWAP 49.46 (5%) 6.2x 5.1x 30-Day VWAP 49.43 (5%) 6.2x 5.1x (3/30/26) 52-Week Low 42.37 (19%) 5.4x 4.4x Wall Street Price Target Low 35.00 (33%) 4.5x 3.7x (6/25/24) All-Time Low 24.96 (52%) 3.3x 2.7x 30 Source: Bloomberg, Wall Street research and FactSet as of 6/4/26.
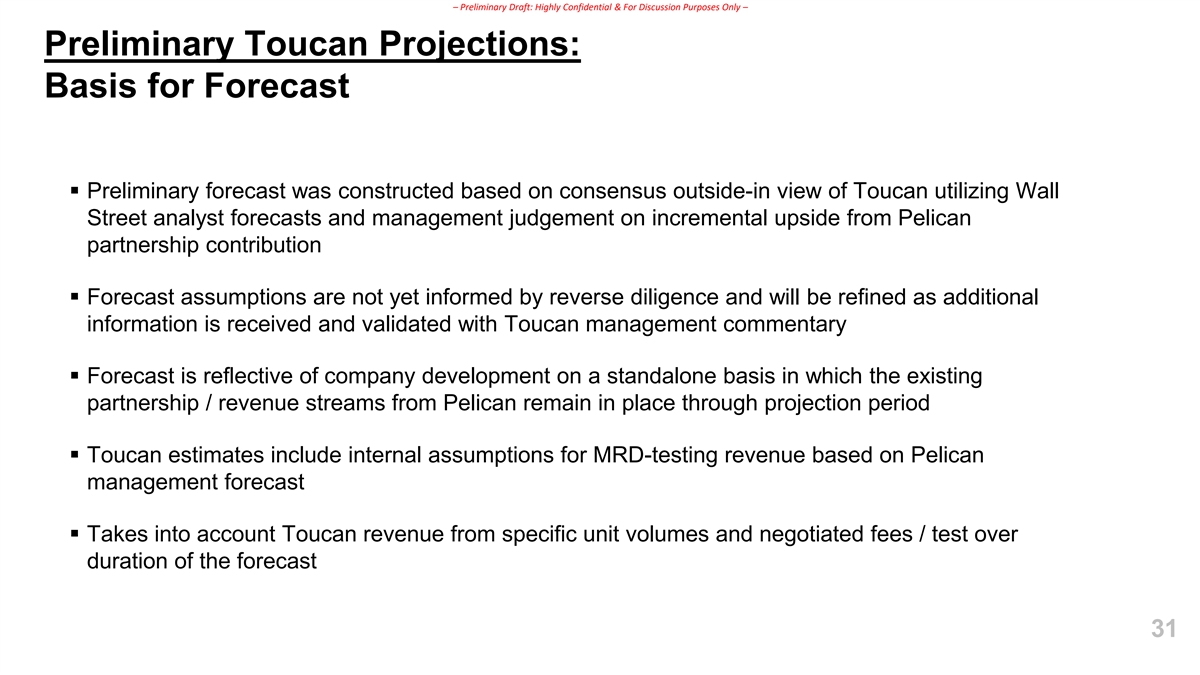
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Toucan Projections: Basis for Forecast ▪ Preliminary forecast was constructed based on consensus outside-in view of Toucan utilizing Wall Street analyst forecasts and management judgement on incremental upside from Pelican partnership contribution ▪ Forecast assumptions are not yet informed by reverse diligence and will be refined as additional information is received and validated with Toucan management commentary ▪ Forecast is reflective of company development on a standalone basis in which the existing partnership / revenue streams from Pelican remain in place through projection period ▪ Toucan estimates include internal assumptions for MRD-testing revenue based on Pelican management forecast ▪ Takes into account Toucan revenue from specific unit volumes and negotiated fees / test over duration of the forecast 31
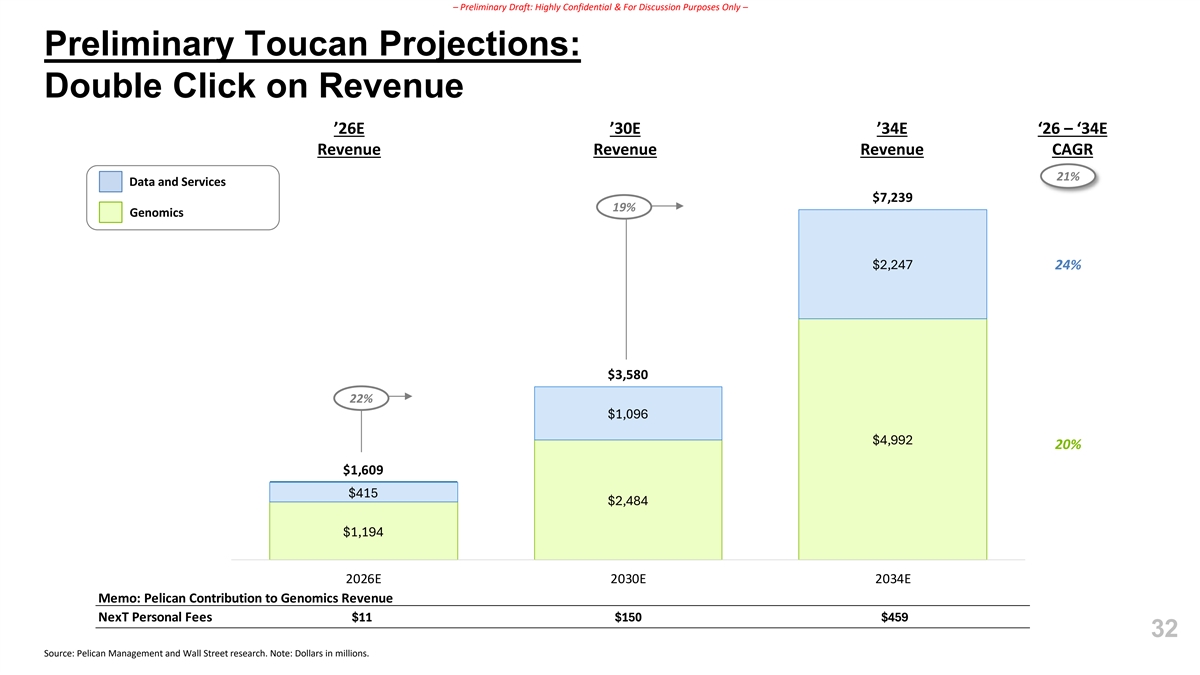
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Toucan Projections: Double Click on Revenue ’26E ’30E ’34E ‘26 – ‘34E Revenue Revenue Revenue CAGR 21% Data and Services $7,239 19% Genomics $2,247 24% $3,580 22% $1,096 $4,992 20% $1,609 $415 $2,484 $1,194 2026E 2030E 2034E Memo: Pelican Contribution to Genomics Revenue NexT Personal Fees $11 $150 $459 32 Source: Pelican Management and Wall Street research. Note: Dollars in millions.
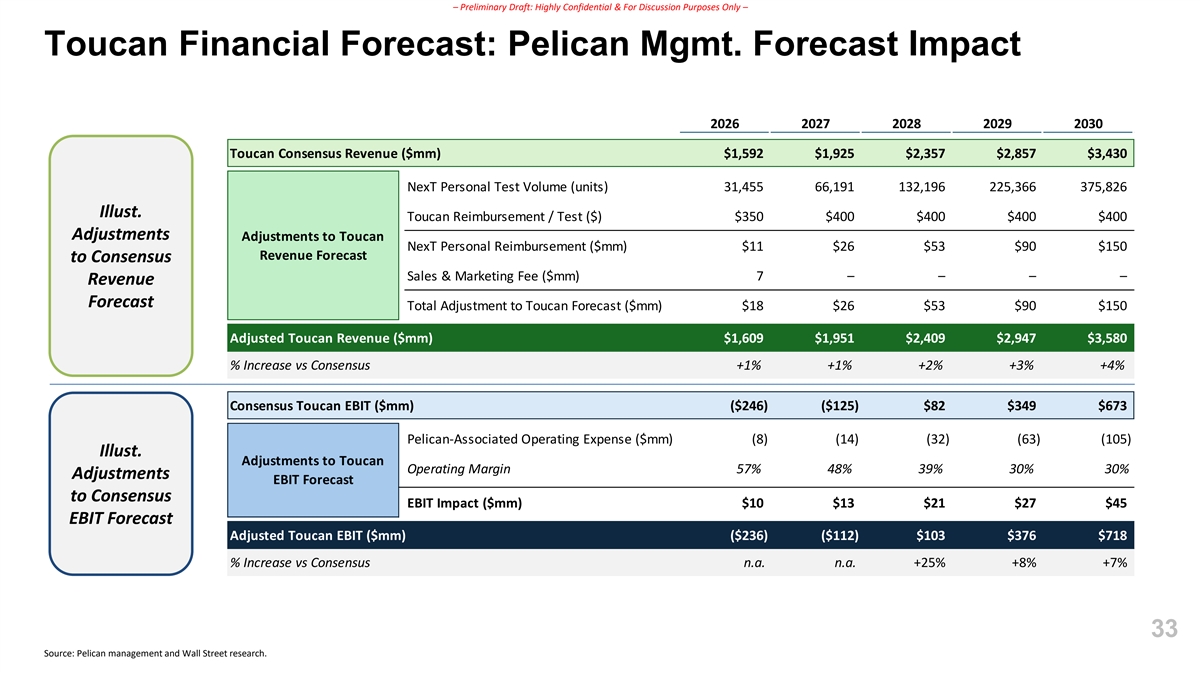
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Toucan Financial Forecast: Pelican Mgmt. Forecast Impact 2026 2027 2028 2029 2030 Toucan Consensus Revenue ($mm) $1,592 $1,925 $2,357 $2,857 $3,430 NexT Personal Test Volume (units) 31,455 66,191 132,196 225,366 375,826 Illust. Toucan Reimbursement / Test ($) $350 $400 $400 $400 $400 Adjustments Adjustments to Toucan NexT Personal Reimbursement ($mm) $11 $26 $53 $90 $150 Revenue Forecast to Consensus Sales & Marketing Fee ($mm) 7 – – – – Revenue Forecast Total Adjustment to Toucan Forecast ($mm) $18 $26 $53 $90 $150 Adjusted Toucan Revenue ($mm) $1,609 $1,951 $2,409 $2,947 $3,580 % Increase vs Consensus +1% +1% +2% +3% +4% Consensus Toucan EBIT ($mm) ($246) ($125) $82 $349 $673 Pelican-Associated Operating Expense ($mm) (8) (14) (32) (63) (105) Illust. Adjustments to Toucan Operating Margin 57% 48% 39% 30% 30% Adjustments EBIT Forecast to Consensus EBIT Impact ($mm) $10 $13 $21 $27 $45 EBIT Forecast Adjusted Toucan EBIT ($mm) ($236) ($112) $103 $376 $718 % Increase vs Consensus n.a. n.a. +25% +8% +7% 33 Source: Pelican management and Wall Street research.
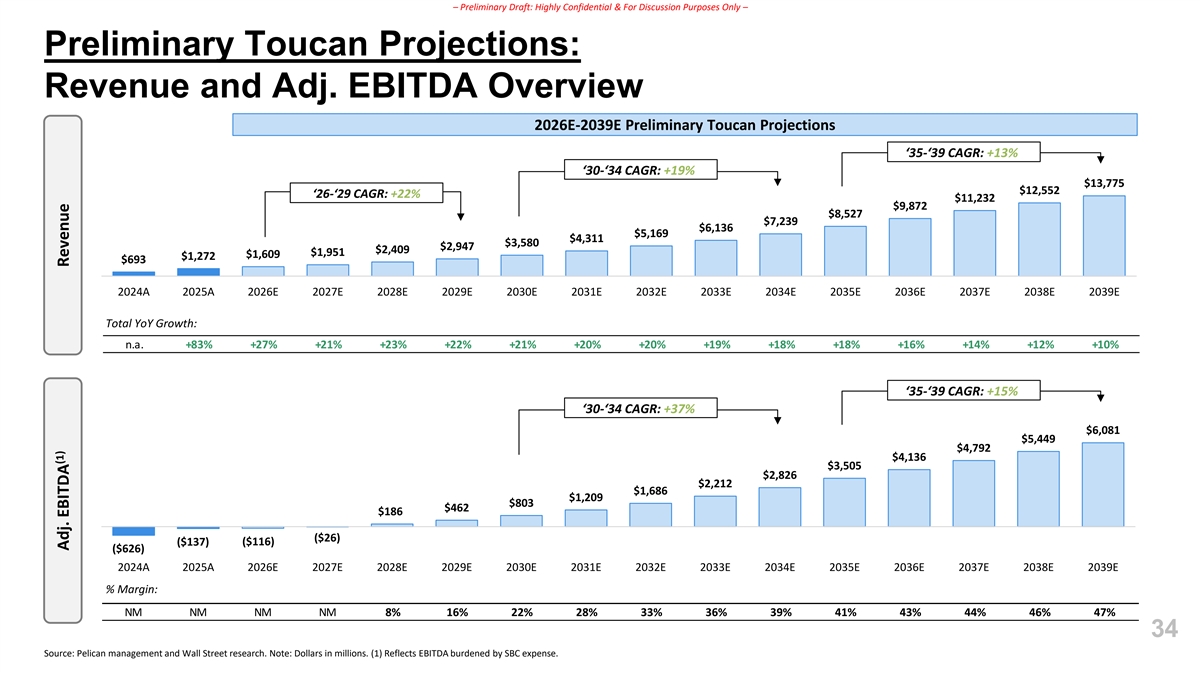
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Toucan Projections: Revenue and Adj. EBITDA Overview 2026E-2039E Preliminary Toucan Projections ‘35-‘39 CAGR: +13% ‘30-‘34 CAGR: +19% $13,775 $12,552 ‘26-‘29 CAGR: +22% $11,232 $9,872 $8,527 $7,239 $6,136 $5,169 $4,311 $3,580 $2,947 $2,409 $1,951 $1,609 $1,272 $693 2024A 2025A 2026E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E 2036E 2037E 2038E 2039E Total YoY Growth: n.a. +83% +27% +21% +23% +22% +21% +20% +20% +19% +18% +18% +16% +14% +12% +10% ‘35-‘39 CAGR: +15% ‘30-‘34 CAGR: +37% $6,081 $5,449 $4,792 $4,136 $3,505 $2,826 $2,212 $1,686 $1,209 $803 $462 $186 ($26) ($116) ($137) ($626) 2024A 2025A 2026E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E 2036E 2037E 2038E 2039E % Margin: NM NM NM NM 8% 16% 22% 28% 33% 36% 39% 41% 43% 44% 46% 47% 34 Source: Pelican management and Wall Street research. Note: Dollars in millions. (1) Reflects EBITDA burdened by SBC expense. (1) Adj. EBITDA Revenue
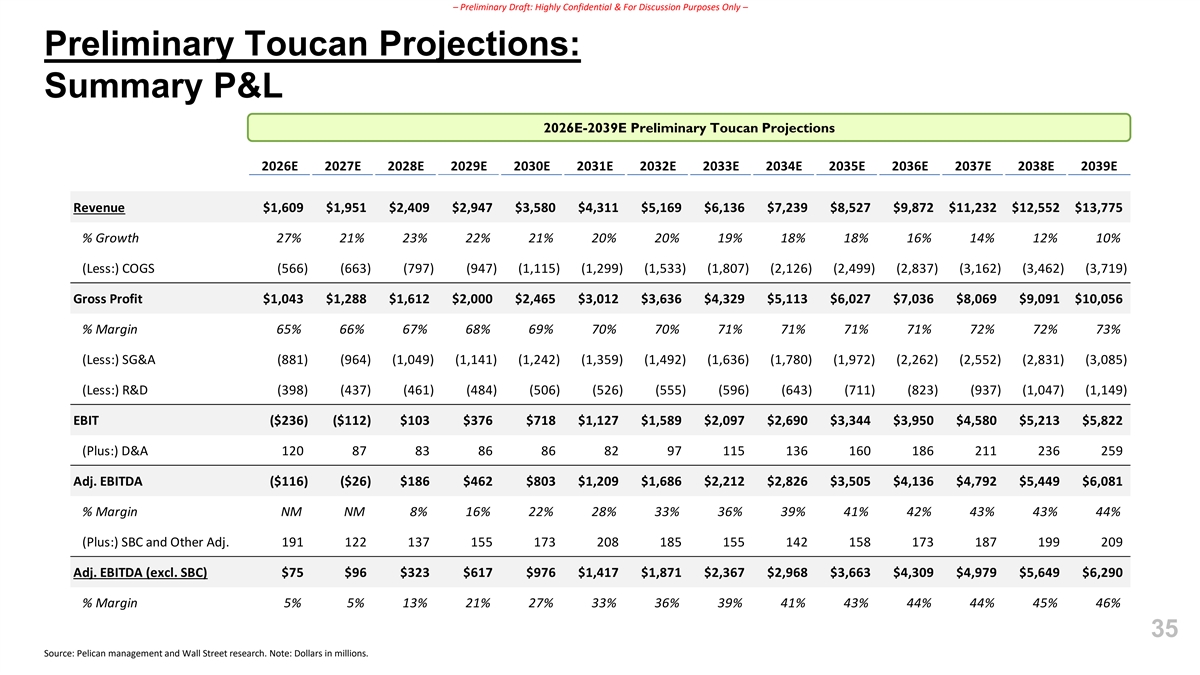
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Output @ Preliminary Toucan Projections: Case 1 Summary P&L 2026E-2039E Preliminary Toucan Projections 2026E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E 2036E 2037E 2038E 2039E Revenue $1,609 $1,951 $2,409 $2,947 $3,580 $4,311 $5,169 $6,136 $7,239 $8,527 $9,872 $11,232 $12,552 $13,775 % Growth 27% 21% 23% 22% 21% 20% 20% 19% 18% 18% 16% 14% 12% 10% (Less:) COGS (566) (663) (797) (947) (1,115) (1,299) (1,533) (1,807) (2,126) (2,499) (2,837) (3,162) (3,462) (3,719) Gross Profit $1,043 $1,288 $1,612 $2,000 $2,465 $3,012 $3,636 $4,329 $5,113 $6,027 $7,036 $8,069 $9,091 $10,056 % Margin 65% 66% 67% 68% 69% 70% 70% 71% 71% 71% 71% 72% 72% 73% (Less:) SG&A (881) (964) (1,049) (1,141) (1,242) (1,359) (1,492) (1,636) (1,780) (1,972) (2,262) (2,552) (2,831) (3,085) (Less:) R&D (398) (437) (461) (484) (506) (526) (555) (596) (643) (711) (823) (937) (1,047) (1,149) EBIT ($236) ($112) $103 $376 $718 $1,127 $1,589 $2,097 $2,690 $3,344 $3,950 $4,580 $5,213 $5,822 (Plus:) D&A 120 87 83 86 86 82 97 115 136 160 186 211 236 259 Adj. EBITDA ($116) ($26) $186 $462 $803 $1,209 $1,686 $2,212 $2,826 $3,505 $4,136 $4,792 $5,449 $6,081 % Margin NM NM 8% 16% 22% 28% 33% 36% 39% 41% 42% 43% 43% 44% (Plus:) SBC and Other Adj. 191 122 137 155 173 208 185 155 142 158 173 187 199 209 Adj. EBITDA (excl. SBC) $75 $96 $323 $617 $976 $1,417 $1,871 $2,367 $2,968 $3,663 $4,309 $4,979 $5,649 $6,290 % Margin 5% 5% 13% 21% 27% 33% 36% 39% 41% 43% 44% 44% 45% 46% 35 Source: Pelican management and Wall Street research. Note: Dollars in millions.
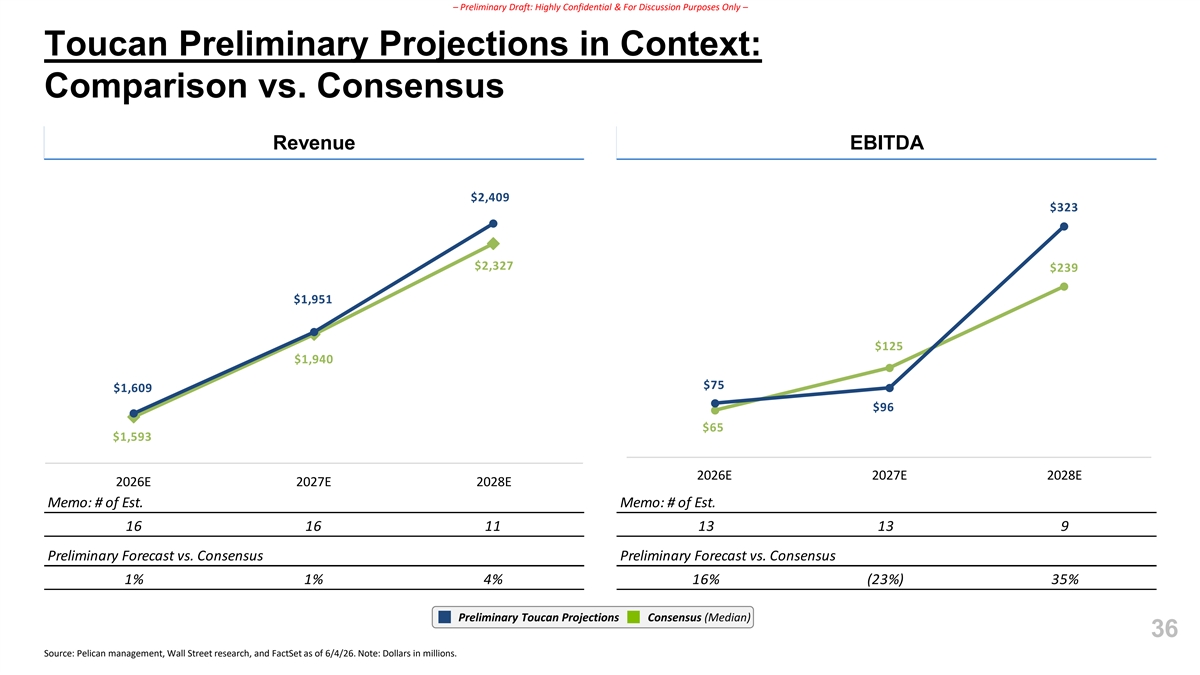
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Toucan Preliminary Projections in Context: Comparison vs. Consensus Update Revenue EBITDA $2,409 $323 $2,327 $239 $1,951 $125 $1,940 $75 $1,609 $96 $65 $1,593 2026E 2027E 2028E 2026E 2027E 2028E Memo: # of Est. Memo: # of Est. 16 16 11 13 13 9 Preliminary Forecast vs. Consensus Preliminary Forecast vs. Consensus 1% 1% 4% 16% (23%) 35% Preliminary Toucan Projections Consensus (Median) 36 Source: Pelican management, Wall Street research, and FactSet as of 6/4/26. Note: Dollars in millions.
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Centerview Toucan Financial Analysis 37
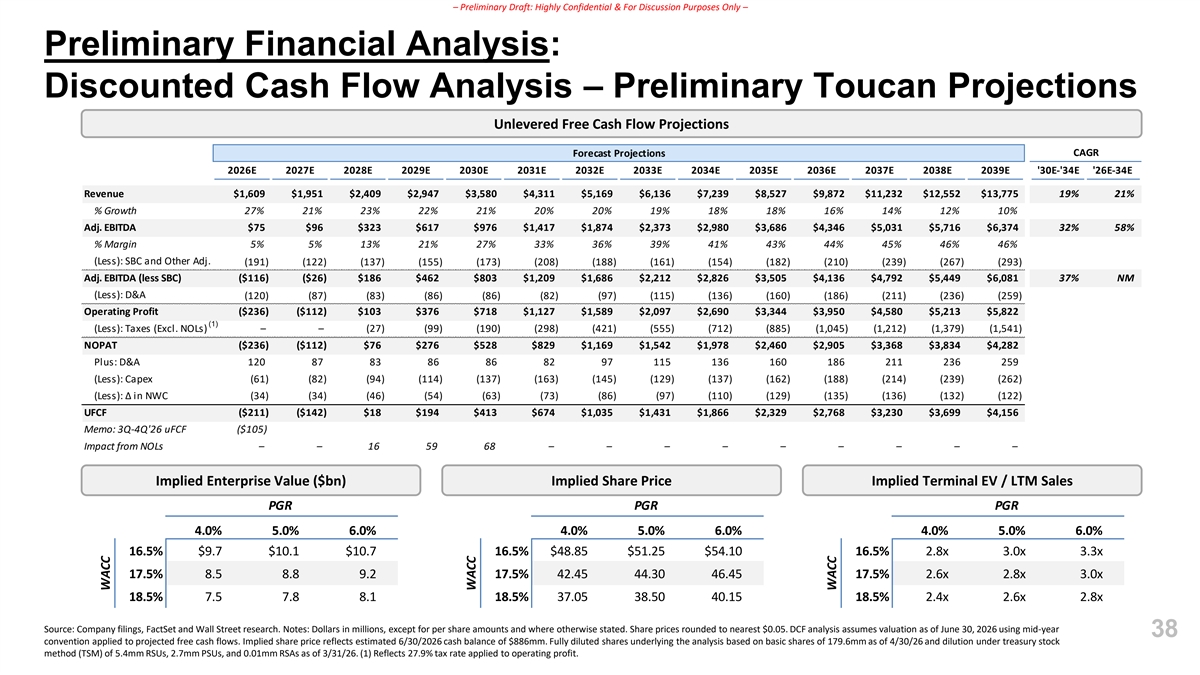
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Output @ Preliminary Financial Analysis: Case 1 Discounted Cash Flow Analysis – Preliminary Toucan Projections Unlevered Free Cash Flow Projections CAGR Forecast Projections 2026E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E 2036E 2037E 2038E 2039E '30E-'34E '26E-34E Revenue $1,609 $1,951 $2,409 $2,947 $3,580 $4,311 $5,169 $6,136 $7,239 $8,527 $9,872 $11,232 $12,552 $13,775 19% 21% % Growth 27% 21% 23% 22% 21% 20% 20% 19% 18% 18% 16% 14% 12% 10% Adj. EBITDA $75 $96 $323 $617 $976 $1,417 $1,874 $2,373 $2,980 $3,686 $4,346 $5,031 $5,716 $6,374 32% 58% % Margin 5% 5% 13% 21% 27% 33% 36% 39% 41% 43% 44% 45% 46% 46% (Less): SBC and Other Adj. (191) (122) (137) (155) (173) (208) (188) (161) (154) (182) (210) (239) (267) (293) Adj. EBITDA (less SBC) ($116) ($26) $186 $462 $803 $1,209 $1,686 $2,212 $2,826 $3,505 $4,136 $4,792 $5,449 $6,081 37% NM (Less): D&A (120) (87) (83) (86) (86) (82) (97) (115) (136) (160) (186) (211) (236) (259) Operating Profit ($236) ($112) $103 $376 $718 $1,127 $1,589 $2,097 $2,690 $3,344 $3,950 $4,580 $5,213 $5,822 (1) (Less): Taxes (Excl. NOLs) – – (27) (99) (190) (298) (421) (555) (712) (885) (1,045) (1,212) (1,379) (1,541) NOPAT ($236) ($112) $76 $276 $528 $829 $1,169 $1,542 $1,978 $2,460 $2,905 $3,368 $3,834 $4,282 Plus: D&A 120 87 83 86 86 82 97 115 136 160 186 211 236 259 (Less): Capex (61) (82) (94) (114) (137) (163) (145) (129) (137) (162) (188) (214) (239) (262) (Less): Δ in NWC (34) (34) (46) (54) (63) (73) (86) (97) (110) (129) (135) (136) (132) (122) UFCF ($211) ($142) $18 $194 $413 $674 $1,035 $1,431 $1,866 $2,329 $2,768 $3,230 $3,699 $4,156 Memo: 3Q-4Q'26 uFCF ($105) Impact from NOLs – – 16 59 68 – – – – – – – – – Implied Enterprise Value ($bn) Implied Share Price Implied Terminal EV / LTM Sales PGR PGR PGRPGR 4.0% 5.0% 6.0% 4.0% 5.0% 6.0% 4.0% 5.0% 6.0% 16.5% $9.7 $10.1 $10.7 16.5% $48.85 $51.25 $54.10 16.5% 2.8x 3.0x 3.3x 17.5% 8.5 8.8 9.2 17.5% 42.45 44.30 46.45 17.5% 2.6x 2.8x 3.0x 18.5% 7.5 7.8 8.1 18.5% 37.05 38.50 40.15 18.5% 2.4x 2.6x 2.8x Source: Company filings, FactSet and Wall Street research. Notes: Dollars in millions, except for per share amounts and where otherwise stated. Share prices rounded to nearest $0.05. DCF analysis assumes valuation as of June 30, 2026 using mid-year 38 convention applied to projected free cash flows. Implied share price reflects estimated 6/30/2026 cash balance of $886mm. Fully diluted shares underlying the analysis based on basic shares of 179.6mm as of 4/30/26 and dilution under treasury stock method (TSM) of 5.4mm RSUs, 2.7mm PSUs, and 0.01mm RSAs as of 3/31/26. (1) Reflects 27.9% tax rate applied to operating profit. WACC WACC WACC
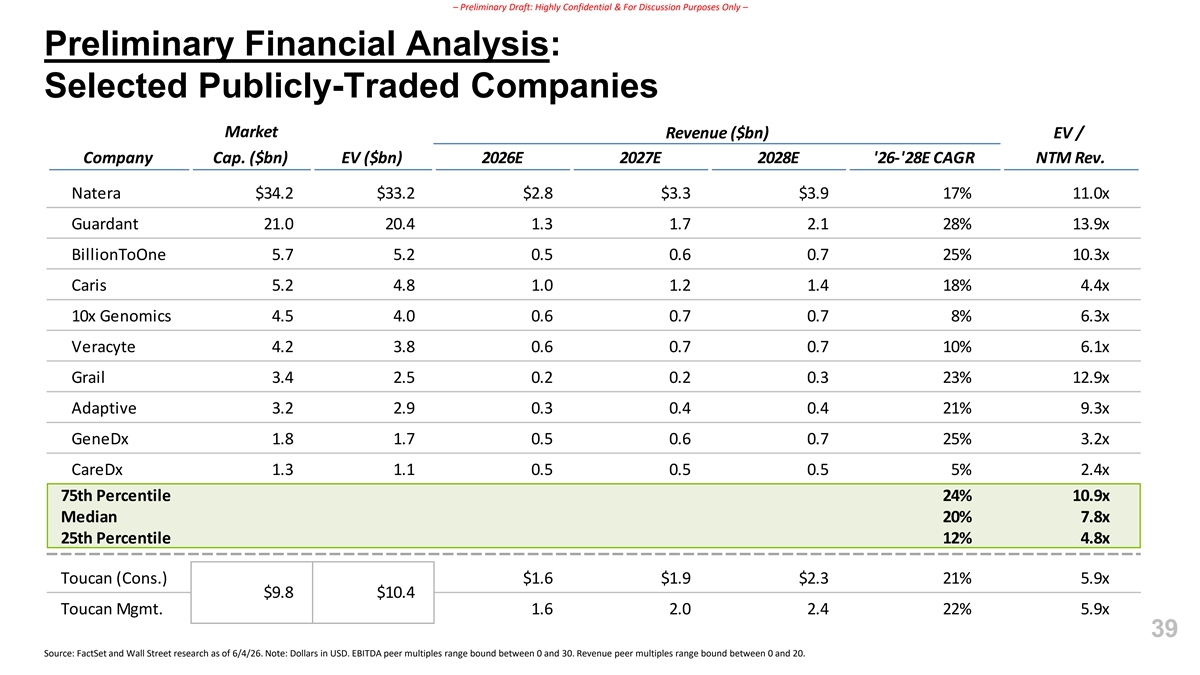
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Financial Analysis: Selected Publicly-Traded Companies Market Revenue ($bn) EV / Company Cap. ($bn) EV ($bn) 2026E 2027E 2028E '26-'28E CAGR NTM Rev. Natera $34.2 $33.2 $2.8 $3.3 $3.9 17% 11.0x Guardant 21.0 20.4 1.3 1.7 2.1 28% 13.9x BillionToOne 5.7 5.2 0.5 0.6 0.7 25% 10.3x Caris 5.2 4.8 1.0 1.2 1.4 18% 4.4x 10x Genomics 4.5 4.0 0.6 0.7 0.7 8% 6.3x Veracyte 4.2 3.8 0.6 0.7 0.7 10% 6.1x Grail 3.4 2.5 0.2 0.2 0.3 23% 12.9x Adaptive 3.2 2.9 0.3 0.4 0.4 21% 9.3x GeneDx 1.8 1.7 0.5 0.6 0.7 25% 3.2x CareDx 1.3 1.1 0.5 0.5 0.5 5% 2.4x 75th Percentile 24% 10.9x Median 20% 7.8x 25th Percentile 12% 4.8x Toucan (Cons.) $1.6 $1.9 $2.3 21% 5.9x $9.8 $10.4 Toucan Mgmt. 1.6 2.0 2.4 22% 5.9x 39 Source: FactSet and Wall Street research as of 6/4/26. Note: Dollars in USD. EBITDA peer multiples range bound between 0 and 30. Revenue peer multiples range bound between 0 and 20.
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Cowen Toucan Financial Analysis 40
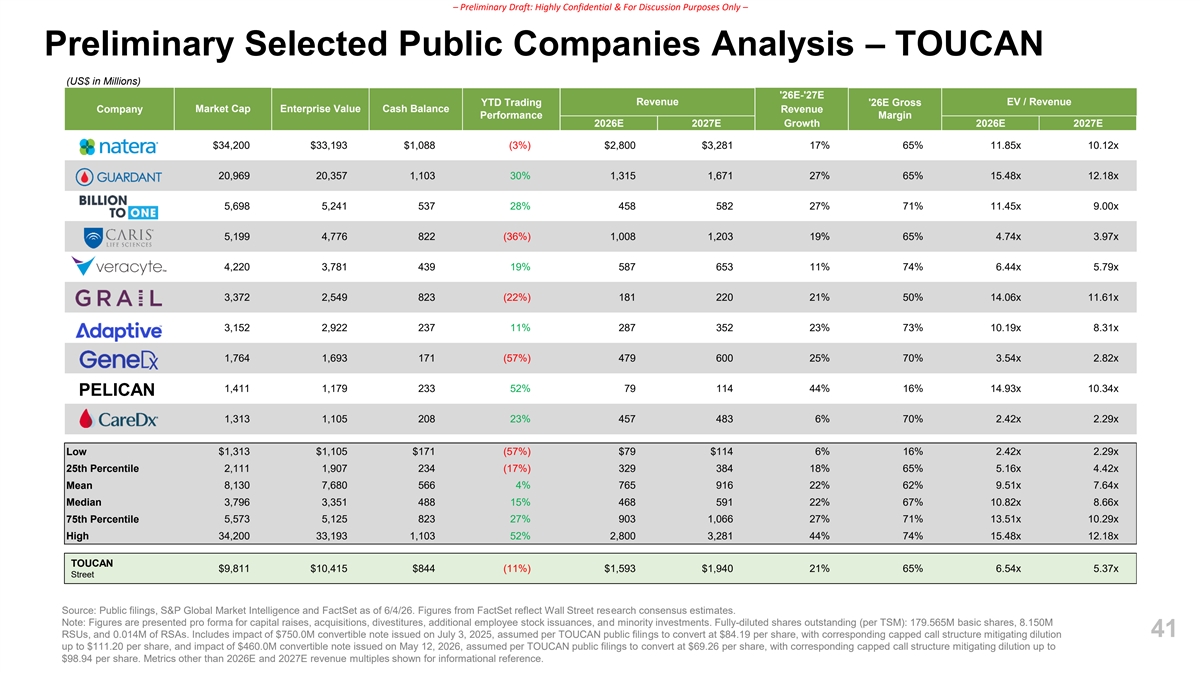
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Selected Public Companies Analysis – TOUCAN (US$ in Millions) '26E-'27E Revenue EV / Revenue YTD Trading '26E Gross Company Market Cap Enterprise Value Cash Balance Revenue Performance Margin 2026E 2027E Growth 2026E 2027E $34,200 $33,193 $1,088 (3%) $2,800 $3,281 17% 65% 11.85x 10.12x 20,969 20,357 1,103 30% 1,315 1,671 27% 65% 15.48x 12.18x 5,698 5,241 537 28% 458 582 27% 71% 11.45x 9.00x 5,199 4,776 822 (36%) 1,008 1,203 19% 65% 4.74x 3.97x 4,220 3,781 439 19% 587 653 11% 74% 6.44x 5.79x 3,372 2,549 823 (22%) 181 220 21% 50% 14.06x 11.61x 3,152 2,922 237 11% 287 352 23% 73% 10.19x 8.31x 1,764 1,693 171 (57%) 479 600 25% 70% 3.54x 2.82x 1,411 1,179 233 52% 79 114 44% 16% 14.93x 10.34x PELICAN 1,313 1,105 208 23% 457 483 6% 70% 2.42x 2.29x Low $1,313 $1,105 $171 (57%) $79 $114 6% 16% 2.42x 2.29x 25th Percentile 2,111 1,907 234 (17%) 329 384 18% 65% 5.16x 4.42x Mean 8,130 7,680 566 4% 765 916 22% 62% 9.51x 7.64x Median 3,796 3,351 488 15% 468 591 22% 67% 10.82x 8.66x 75th Percentile 5,573 5,125 823 27% 903 1,066 27% 71% 13.51x 10.29x High 34,200 33,193 1,103 52% 2,800 3,281 44% 74% 15.48x 12.18x TOUCAN $9,811 $10,415 $844 (11%) $1,593 $1,940 21% 65% 6.54x 5.37x Street Source: Public filings, S&P Global Market Intelligence and FactSet as of 6/4/26. Figures from FactSet reflect Wall Street research consensus estimates. Note: Figures are presented pro forma for capital raises, acquisitions, divestitures, additional employee stock issuances, and minority investments. Fully-diluted shares outstanding (per TSM): 179.565M basic shares, 8.150M RSUs, and 0.014M of RSAs. Includes impact of $750.0M convertible note issued on July 3, 2025, assumed per TOUCAN public filings to convert at $84.19 per share, with corresponding capped call structure mitigating dilution 41 up to $111.20 per share, and impact of $460.0M convertible note issued on May 12, 2026, assumed per TOUCAN public filings to convert at $69.26 per share, with corresponding capped call structure mitigating dilution up to $98.94 per share. Metrics other than 2026E and 2027E revenue multiples shown for informational reference.
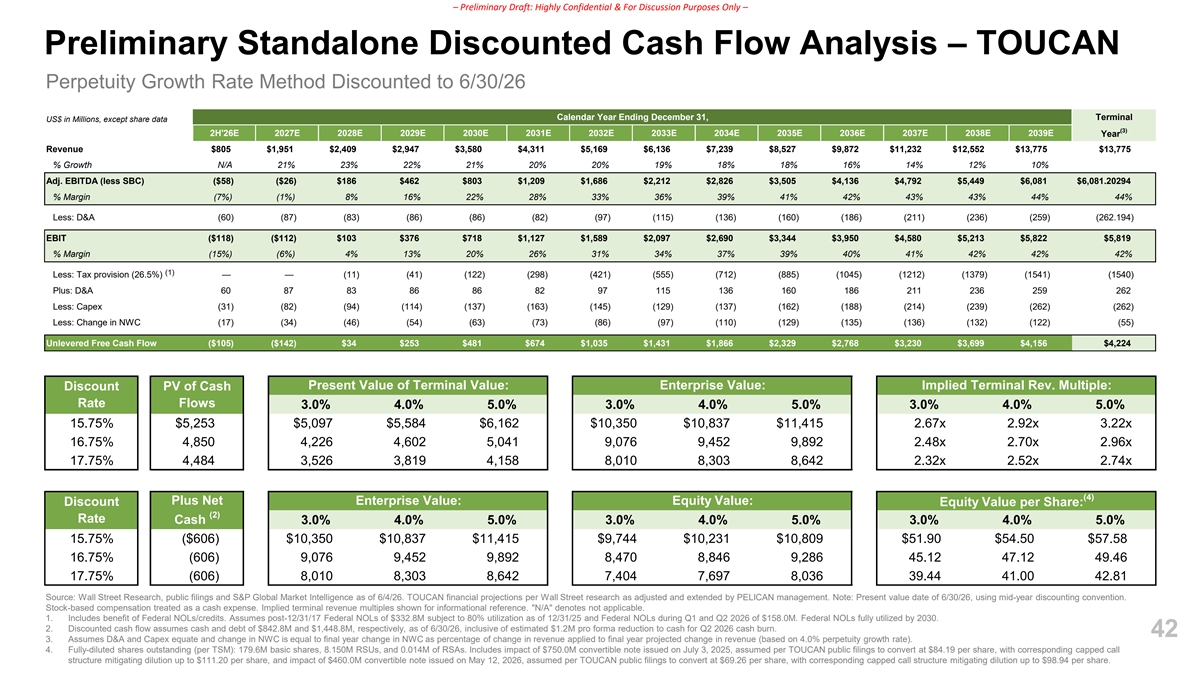
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Standalone Discounted Cash Flow Analysis – TOUCAN Perpetuity Growth Rate Method Discounted to 6/30/26 Calendar Year Ending December 31, Terminal US$ in Millions, except share data (3) 2H'26E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E 2036E 2037E 2038E 2039E Year Revenue $805 $1,951 $2,409 $2,947 $3,580 $4,311 $5,169 $6,136 $7,239 $8,527 $9,872 $11,232 $12,552 $13,775 $13,775 % Growth N/A 21% 23% 22% 21% 20% 20% 19% 18% 18% 16% 14% 12% 10% Adj. EBITDA (less SBC) ($58) ($26) $186 $462 $803 $1,209 $1,686 $2,212 $2,826 $3,505 $4,136 $4,792 $5,449 $6,081 $6,081.20294 % Margin (7%) (1%) 8% 16% 22% 28% 33% 36% 39% 41% 42% 43% 43% 44% 44% Less: D&A (60) (87) (83) (86) (86) (82) (97) (115) (136) (160) (186) (211) (236) (259) (262.194) EBIT ($118) ($112) $103 $376 $718 $1,127 $1,589 $2,097 $2,690 $3,344 $3,950 $4,580 $5,213 $5,822 $5,819 % Margin (15%) (6%) 4% 13% 20% 26% 31% 34% 37% 39% 40% 41% 42% 42% 42% (1) Less: Tax provision (26.5%) — — (11) (41) (122) (298) (421) (555) (712) (885) (1045) (1212) (1379) (1541) (1540) Plus: D&A 60 87 83 86 86 82 97 115 136 160 186 211 236 259 262 Less: Capex (31) (82) (94) (114) (137) (163) (145) (129) (137) (162) (188) (214) (239) (262) (262) Less: Change in NWC (17) (34) (46) (54) (63) (73) (86) (97) (110) (129) (135) (136) (132) (122) (55) Unlevered Free Cash Flow ($105) ($142) $34 $253 $481 $674 $1,035 $1,431 $1,866 $2,329 $2,768 $3,230 $3,699 $4,156 $4,224 Present Value of Terminal Value: Enterprise Value: Implied Terminal Rev. Multiple: Discount PV of Cash Rate Flows 3.0% 4.0% 5.0% 3.0% 4.0% 5.0% 3.0% 4.0% 5.0% 15.75% $5,253 $5,097 $5,584 $6,162 $10,350 $10,837 $11,415 2.67x 2.92x 3.22x 16.75% 4,850 4,226 4,602 5,041 9,076 9,452 9,892 2.48x 2.70x 2.96x 17.75% 4,484 3,526 3,819 4,158 8,010 8,303 8,642 2.32x 2.52x 2.74x (4) Plus Net Enterprise Value: Equity Value: Discount Equity Value per Share: (2) Rate Cash 3.0% 4.0% 5.0% 3.0% 4.0% 5.0% 3.0% 4.0% 5.0% 15.75% ($606) $10,350 $10,837 $11,415 $9,744 $10,231 $10,809 $51.90 $54.50 $57.58 16.75% (606) 9,076 9,452 9,892 8,470 8,846 9,286 45.12 47.12 49.46 17.75% (606) 8,010 8,303 8,642 7,404 7,697 8,036 39.44 41.00 42.81 Source: Wall Street Research, public filings and S&P Global Market Intelligence as of 6/4/26. TOUCAN financial projections per Wall Street research as adjusted and extended by PELICAN management. Note: Present value date of 6/30/26, using mid-year discounting convention. Stock-based compensation treated as a cash expense. Implied terminal revenue multiples shown for informational reference. N/A denotes not applicable. 1. Includes benefit of Federal NOLs/credits. Assumes post-12/31/17 Federal NOLs of $332.8M subject to 80% utilization as of 12/31/25 and Federal NOLs during Q1 and Q2 2026 of $158.0M. Federal NOLs fully utilized by 2030. 2. Discounted cash flow assumes cash and debt of $842.8M and $1,448.8M, respectively, as of 6/30/26, inclusive of estimated $1.2M pro forma reduction to cash for Q2 2026 cash burn. 42 3. Assumes D&A and Capex equate and change in NWC is equal to final year change in NWC as percentage of change in revenue applied to final year projected change in revenue (based on 4.0% perpetuity growth rate). 4. Fully-diluted shares outstanding (per TSM): 179.6M basic shares, 8.150M RSUs, and 0.014M of RSAs. Includes impact of $750.0M convertible note issued on July 3, 2025, assumed per TOUCAN public filings to convert at $84.19 per share, with corresponding capped call structure mitigating dilution up to $111.20 per share, and impact of $460.0M convertible note issued on May 12, 2026, assumed per TOUCAN public filings to convert at $69.26 per share, with corresponding capped call structure mitigating dilution up to $98.94 per share.
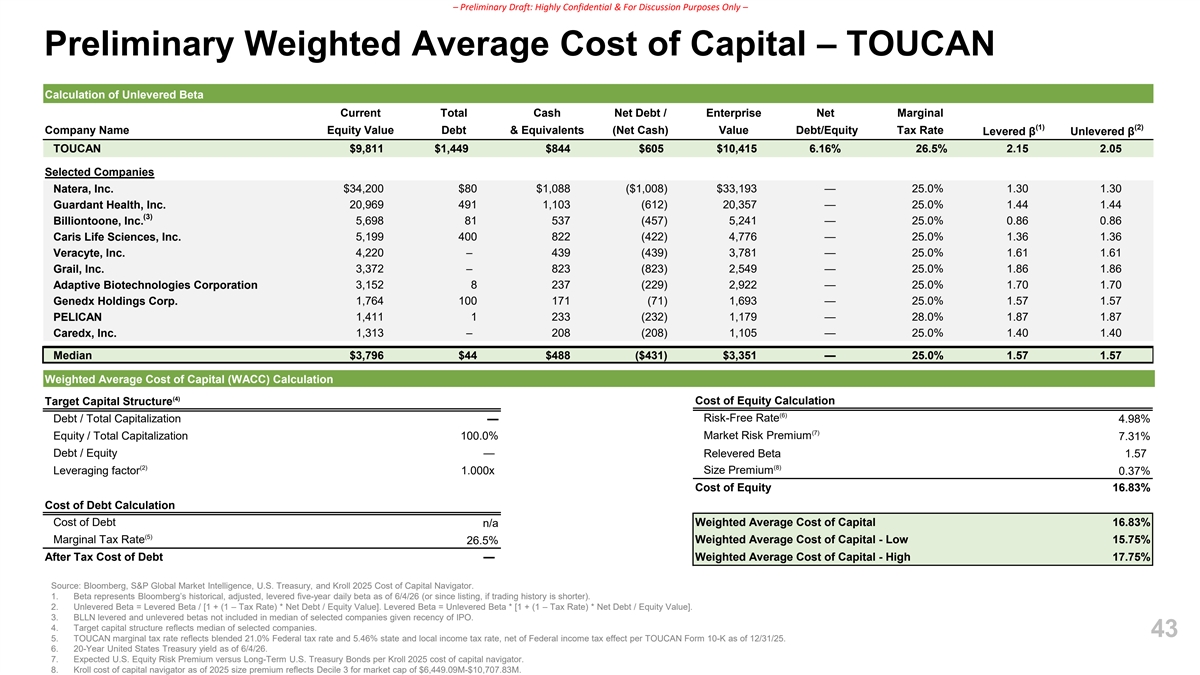
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Weighted Average Cost of Capital – TOUCAN Calculation of Unlevered Beta Current Total Cash Net Debt / Enterprise Net Marginal (1) (2) Company Name Equity Value Debt & Equivalents (Net Cash) Value Debt/Equity Tax Rate Levered β Unlevered β TOUCAN $9,811 $1,449 $844 $605 $10,415 6.16% 26.5% 2.15 2.05 Selected Companies Natera, Inc. $34,200 $80 $1,088 ($1,008) $33,193 — 25.0% 1.30 1.30 Guardant Health, Inc. 20,969 491 1,103 (612) 20,357 — 25.0% 1.44 1.44 (3) Billiontoone, Inc. 5,698 81 537 (457) 5,241 — 25.0% 0.86 0.86 Caris Life Sciences, Inc. 5,199 400 822 (422) 4,776 — 25.0% 1.36 1.36 4,220 – 439 (439) 3,781 — 25.0% 1.61 1.61 Veracyte, Inc. Grail, Inc. 3,372 – 823 (823) 2,549 — 25.0% 1.86 1.86 Adaptive Biotechnologies Corporation 3,152 8 237 (229) 2,922 — 25.0% 1.70 1.70 Genedx Holdings Corp. 1,764 100 171 (71) 1,693 — 25.0% 1.57 1.57 PELICAN 1,411 1 233 (232) 1,179 — 28.0% 1.87 1.87 Caredx, Inc. 1,313 – 208 (208) 1,105 — 25.0% 1.40 1.40 Median $3,796 $44 $488 ($431) $3,351 — 25.0% 1.57 1.57 Weighted Average Cost of Capital (WACC) Calculation (4) Target Capital Structure Cost of Equity Calculation (6) Debt / Total Capitalization — Risk-Free Rate 4.98% (7) Equity / Total Capitalization 100.0% Market Risk Premium 7.31% Debt / Equity — Relevered Beta 1.57 (2) (8) Size Premium Leveraging factor 1.000x 0.37% Cost of Equity 16.83% Cost of Debt Calculation Cost of Debt Weighted Average Cost of Capital 16.83% n/a (5) Marginal Tax Rate Weighted Average Cost of Capital - Low 15.75% 26.5% After Tax Cost of Debt — Weighted Average Cost of Capital - High 17.75% Source: Bloomberg, S&P Global Market Intelligence, U.S. Treasury, and Kroll 2025 Cost of Capital Navigator. 1. Beta represents Bloomberg’s historical, adjusted, levered five-year daily beta as of 6/4/26 (or since listing, if trading history is shorter). 2. Unlevered Beta = Levered Beta / [1 + (1 – Tax Rate) * Net Debt / Equity Value]. Levered Beta = Unlevered Beta * [1 + (1 – Tax Rate) * Net Debt / Equity Value]. 3. BLLN levered and unlevered betas not included in median of selected companies given recency of IPO. 4. Target capital structure reflects median of selected companies. 43 5. TOUCAN marginal tax rate reflects blended 21.0% Federal tax rate and 5.46% state and local income tax rate, net of Federal income tax effect per TOUCAN Form 10-K as of 12/31/25. 6. 20-Year United States Treasury yield as of 6/4/26. 7. Expected U.S. Equity Risk Premium versus Long-Term U.S. Treasury Bonds per Kroll 2025 cost of capital navigator. 8. Kroll cost of capital navigator as of 2025 size premium reflects Decile 3 for market cap of $6,449.09M-$10,707.83M.
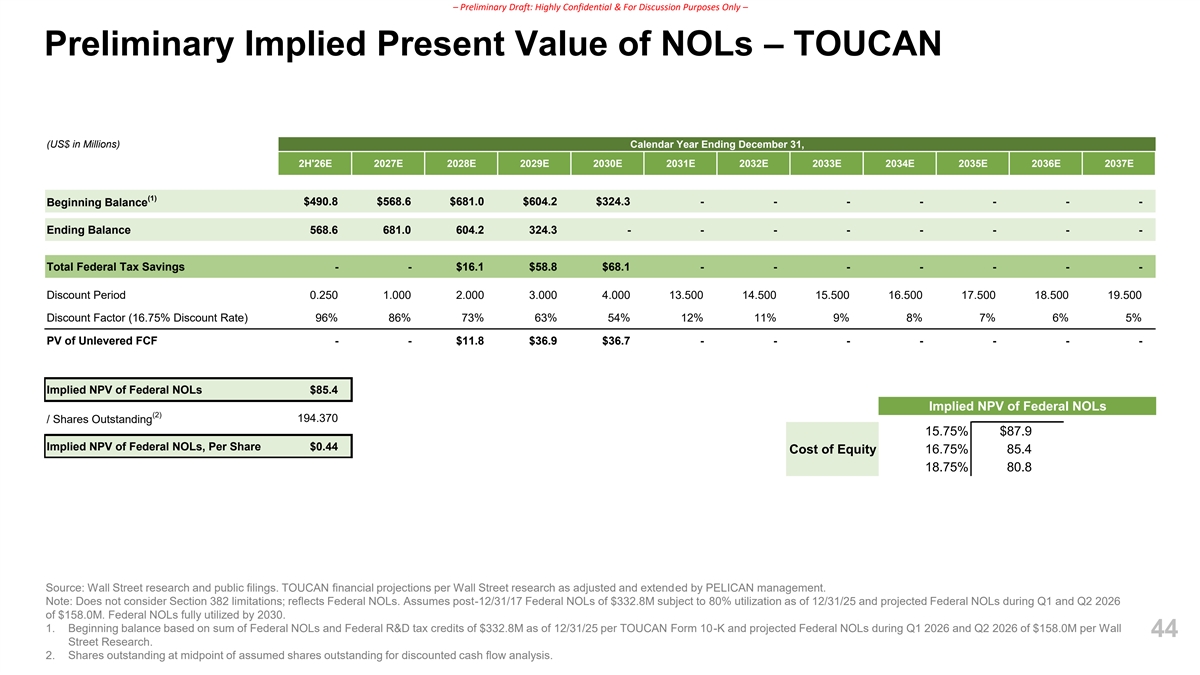
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary Implied Present Value of NOLs – TOUCAN (US$ in Millions) Calendar Year Ending December 31, 2H'26E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E 2036E 2037E (1) $490.8 $568.6 $681.0 $604.2 $324.3 - - - - - - - Beginning Balance Ending Balance 568.6 681.0 604.2 324.3 - - - - - - - - Total Federal Tax Savings - - $16.1 $58.8 $68.1 - - - - - - - Discount Period 0.250 1.000 2.000 3.000 4.000 13.500 14.500 15.500 16.500 17.500 18.500 19.500 Discount Factor (16.75% Discount Rate) 96% 86% 73% 63% 54% 12% 11% 9% 8% 7% 6% 5% PV of Unlevered FCF - - $11.8 $36.9 $36.7 - - - - - - - Implied NPV of Federal NOLs $85.4 Implied NPV of Federal NOLs (2) 194.370 / Shares Outstanding 15.75% $87.9 Implied NPV of Federal NOLs, Per Share $0.44 Cost of Equity 16.75% 85.4 18.75% 80.8 Source: Wall Street research and public filings. TOUCAN financial projections per Wall Street research as adjusted and extended by PELICAN management. Note: Does not consider Section 382 limitations; reflects Federal NOLs. Assumes post-12/31/17 Federal NOLs of $332.8M subject to 80% utilization as of 12/31/25 and projected Federal NOLs during Q1 and Q2 2026 of $158.0M. Federal NOLs fully utilized by 2030. 1. Beginning balance based on sum of Federal NOLs and Federal R&D tax credits of $332.8M as of 12/31/25 per TOUCAN Form 10-K and projected Federal NOLs during Q1 2026 and Q2 2026 of $158.0M per Wall 44 Street Research. 2. Shares outstanding at midpoint of assumed shares outstanding for discounted cash flow analysis.
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Perspectives on Toucan Preliminary Value Indication and Next Steps 45
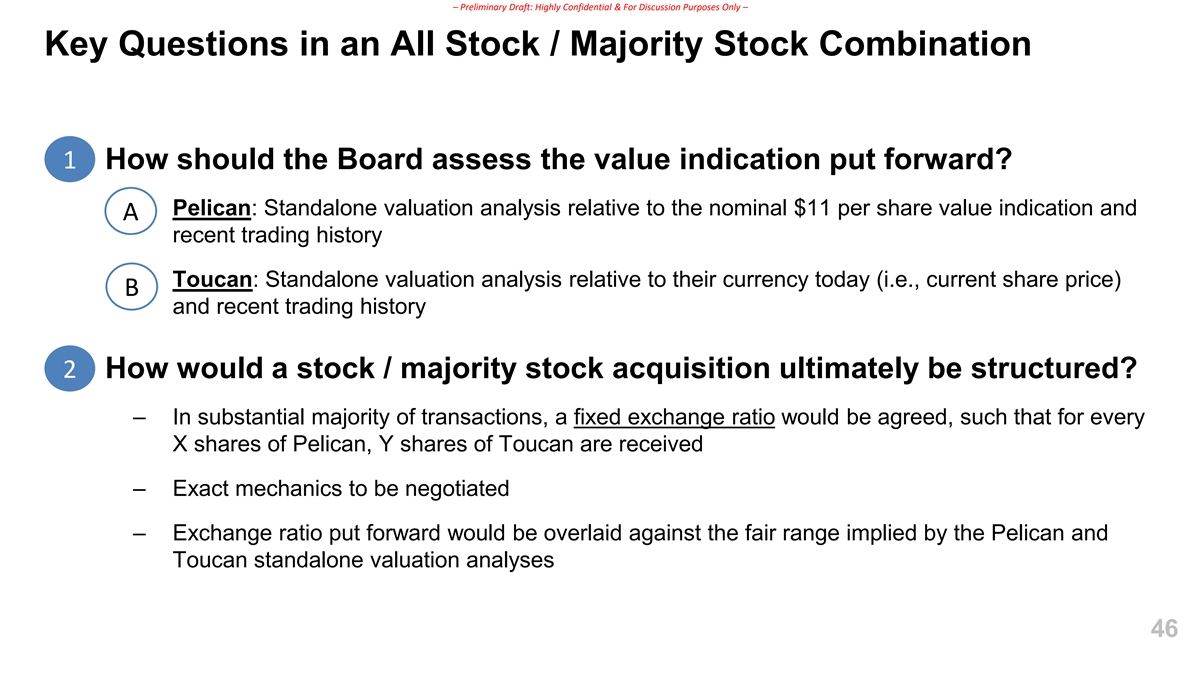
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Key Questions in an All Stock / Majority Stock Combination 1 ▪ How should the Board assess the value indication put forward? – Pelican: Standalone valuation analysis relative to the nominal $11 per share value indication and A recent trading history – Toucan: Standalone valuation analysis relative to their currency today (i.e., current share price) B and recent trading history 2 ▪ How would a stock / majority stock acquisition ultimately be structured? – In substantial majority of transactions, a fixed exchange ratio would be agreed, such that for every X shares of Pelican, Y shares of Toucan are received – Exact mechanics to be negotiated – Exchange ratio put forward would be overlaid against the fair range implied by the Pelican and Toucan standalone valuation analyses 46
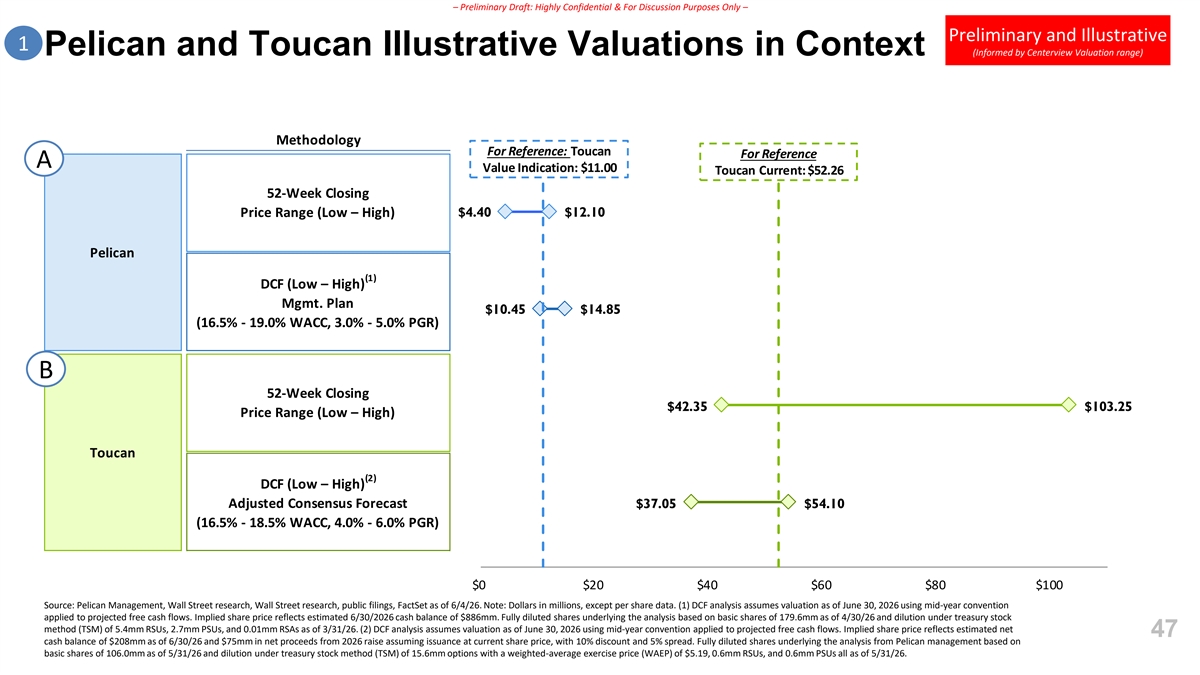
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary and Illustrative 1 Pelican and Toucan Illustrative Valuations in Context (Informed by Centerview Valuation range) Methodology For Reference: Toucan For Reference A Value Indication: $11.00 Toucan Current: $52.26 52-Week Closing Price Range (Low – High) $4.40 $12.10 Pelican (1) DCF (Low – High) Mgmt. Plan $10.45 $14.85 (16.5% - 19.0% WACC, 3.0% - 5.0% PGR) B 52-Week Closing $42.35 $103.25 Price Range (Low – High) Toucan (2) DCF (Low – High) Adjusted Consensus Forecast $37.05 $54.10 (16.5% - 18.5% WACC, 4.0% - 6.0% PGR) $0 $20 $40 $60 $80 $100 Source: Pelican Management, Wall Street research, Wall Street research, public filings, FactSet as of 6/4/26. Note: Dollars in millions, except per share data. (1) DCF analysis assumes valuation as of June 30, 2026 using mid-year convention applied to projected free cash flows. Implied share price reflects estimated 6/30/2026 cash balance of $886mm. Fully diluted shares underlying the analysis based on basic shares of 179.6mm as of 4/30/26 and dilution under treasury stock method (TSM) of 5.4mm RSUs, 2.7mm PSUs, and 0.01mm RSAs as of 3/31/26. (2) DCF analysis assumes valuation as of June 30, 2026 using mid-year convention applied to projected free cash flows. Implied share price reflects estimated net 47 cash balance of $208mm as of 6/30/26 and $75mm in net proceeds from 2026 raise assuming issuance at current share price, with 10% discount and 5% spread. Fully diluted shares underlying the analysis from Pelican management based on basic shares of 106.0mm as of 5/31/26 and dilution under treasury stock method (TSM) of 15.6mm options with a weighted-average exercise price (WAEP) of $5.19, 0.6mm RSUs, and 0.6mm PSUs all as of 5/31/26.
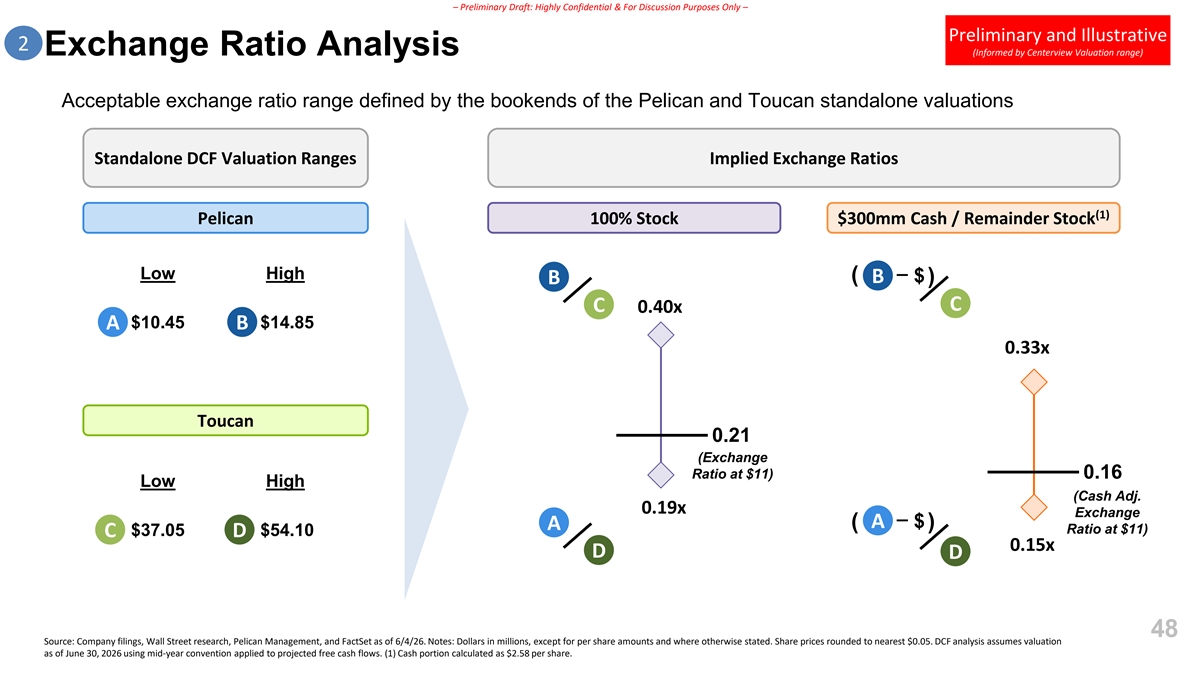
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary and Illustrative 2 Exchange Ratio Analysis (Informed by Centerview Valuation range) Acceptable exchange ratio range defined by the bookends of the Pelican and Toucan standalone valuations Standalone DCF Valuation Ranges Implied Exchange Ratios (1) Pelican 100% Stock $300mm Cash / Remainder Stock Low High ( $ B ) B C C 0.40x $10.45 $14.85 A B 0.33x Toucan 0.21 (Exchange Ratio at $11) 0.16 Low High (Cash Adj. 0.19x Exchange $ ( A ) A Ratio at $11) $37.05 $54.10 C D 0.15x D D 48 Source: Company filings, Wall Street research, Pelican Management, and FactSet as of 6/4/26. Notes: Dollars in millions, except for per share amounts and where otherwise stated. Share prices rounded to nearest $0.05. DCF analysis assumes valuation as of June 30, 2026 using mid-year convention applied to projected free cash flows. (1) Cash portion calculated as $2.58 per share.
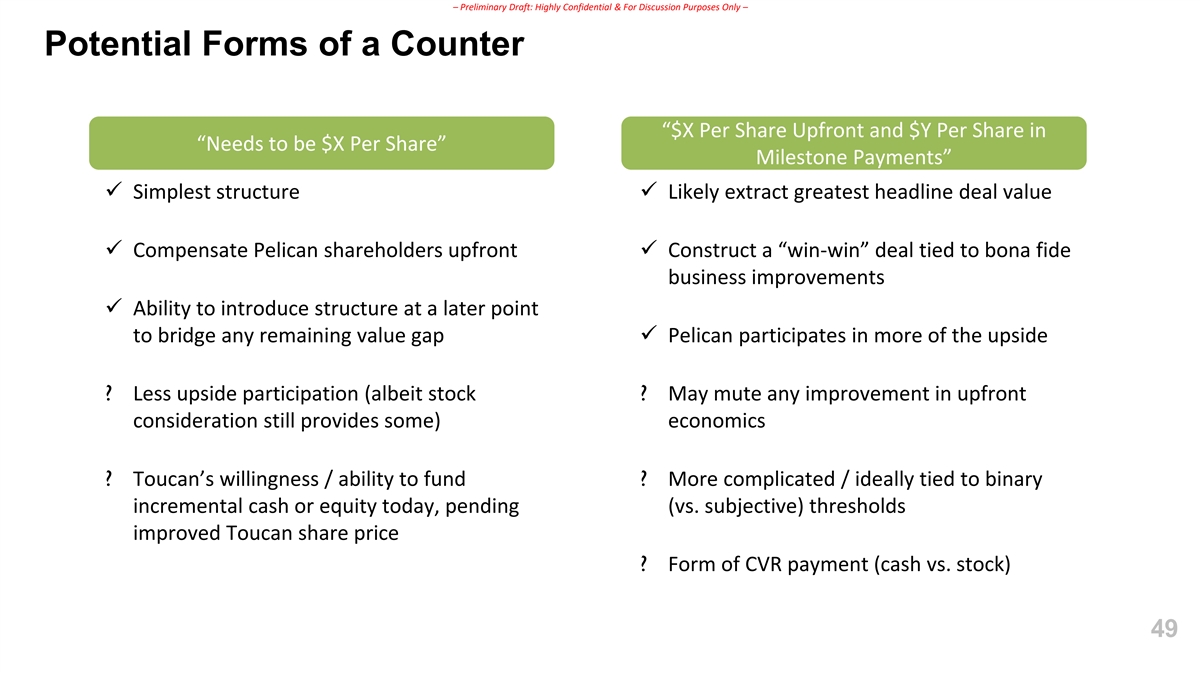
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Potential Forms of a Counter “$X Per Share Upfront and $Y Per Share in “Needs to be $X Per Share” Milestone Payments” ✓ Simplest structure ✓ Likely extract greatest headline deal value ✓ Compensate Pelican shareholders upfront ✓ Construct a “win-win” deal tied to bona fide business improvements ✓ Ability to introduce structure at a later point to bridge any remaining value gap ✓ Pelican participates in more of the upside ? Less upside participation (albeit stock ? May mute any improvement in upfront consideration still provides some) economics ? Toucan’s willingness / ability to fund ? More complicated / ideally tied to binary incremental cash or equity today, pending (vs. subjective) thresholds improved Toucan share price ? Form of CVR payment (cash vs. stock) 49
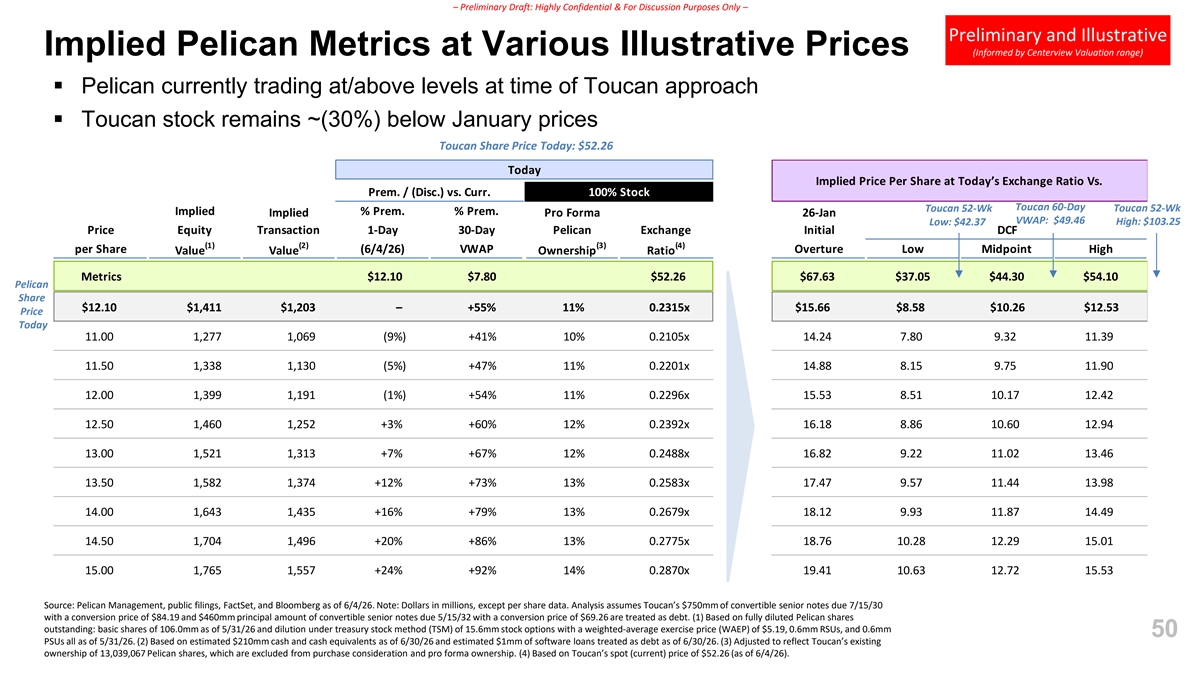
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary and Illustrative Implied Pelican Metrics at Various Illustrative Prices (Informed by Centerview Valuation range) ▪ Pelican currently trading at/above levels at time of Toucan approach ▪ Toucan stock remains ~(30%) below January prices Toucan Share Price Today: $52.26 Today Implied Price Per Share at Today’s Exchange Ratio Vs. Prem. / (Disc.) vs. Curr. 100% Stock Toucan 60-Day Toucan 52-Wk Toucan 52-Wk Implied % Prem. % Prem. Implied Pro Forma 26-Jan VWAP: $49.46 Low: $42.37 High: $103.25 Price Equity Transaction 1-Day 30-Day Pelican Exchange Initial DCF (1) (2) (3) (4) per Share (6/4/26) VWAP Overture Low Midpoint High Value Value Ownership Ratio Metrics $12.10 $7.80 $52.26 $67.63 $37.05 $44.30 $54.10 Pelican Share $12.10 $1,411 $1,203 – +55% 11% 0.2315x $15.66 $8.58 $10.26 $12.53 Price Today 11.00 1,277 1,069 (9%) +41% 10% 0.2105x 14.24 7.80 9.32 11.39 11.50 1,338 1,130 (5%) +47% 11% 0.2201x 14.88 8.15 9.75 11.90 12.00 1,399 1,191 (1%) +54% 11% 0.2296x 15.53 8.51 10.17 12.42 12.50 1,460 1,252 +3% +60% 12% 0.2392x 16.18 8.86 10.60 12.94 13.00 1,521 1,313 +7% +67% 12% 0.2488x 16.82 9.22 11.02 13.46 13.50 1,582 1,374 +12% +73% 13% 0.2583x 17.47 9.57 11.44 13.98 14.00 1,643 1,435 +16% +79% 13% 0.2679x 18.12 9.93 11.87 14.49 14.50 1,704 1,496 +20% +86% 13% 0.2775x 18.76 10.28 12.29 15.01 15.00 1,765 1,557 +24% +92% 14% 0.2870x 19.41 10.63 12.72 15.53 Source: Pelican Management, public filings, FactSet, and Bloomberg as of 6/4/26. Note: Dollars in millions, except per share data. Analysis assumes Toucan’s $750mm of convertible senior notes due 7/15/30 with a conversion price of $84.19 and $460mm principal amount of convertible senior notes due 5/15/32 with a conversion price of $69.26 are treated as debt. (1) Based on fully diluted Pelican shares outstanding: basic shares of 106.0mm as of 5/31/26 and dilution under treasury stock method (TSM) of 15.6mm stock options with a weighted-average exercise price (WAEP) of $5.19, 0.6mm RSUs, and 0.6mm 50 PSUs all as of 5/31/26. (2) Based on estimated $210mm cash and cash equivalents as of 6/30/26 and estimated $1mm of software loans treated as debt as of 6/30/26. (3) Adjusted to reflect Toucan’s existing ownership of 13,039,067 Pelican shares, which are excluded from purchase consideration and pro forma ownership. (4) Based on Toucan’s spot (current) price of $52.26 (as of 6/4/26).
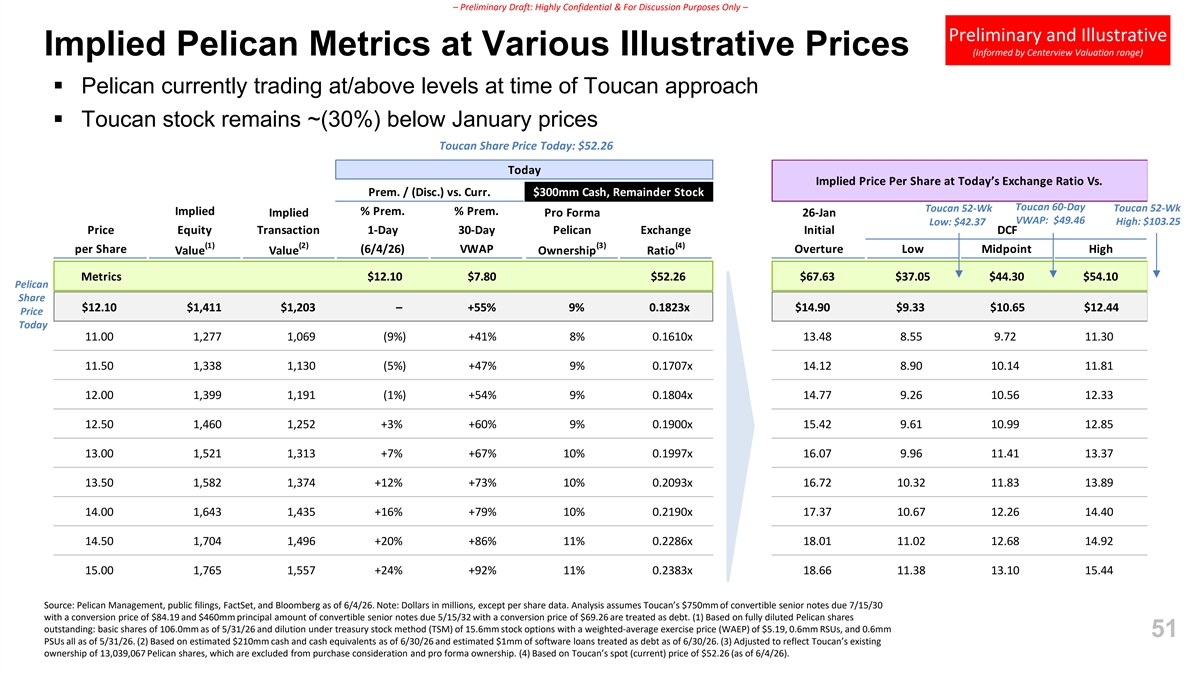
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Preliminary and Illustrative Implied Pelican Metrics at Various Illustrative Prices (Informed by Centerview Valuation range) ▪ Pelican currently trading at/above levels at time of Toucan approach ▪ Toucan stock remains ~(30%) below January prices Toucan Share Price Today: $52.26 Today Implied Price Per Share at Today’s Exchange Ratio Vs. Prem. / (Disc.) vs. Curr. $300mm Cash, Remainder Stock Toucan 60-Day Toucan 52-Wk Toucan 52-Wk Implied % Prem. % Prem. Implied Pro Forma 26-Jan VWAP: $49.46 Low: $42.37 High: $103.25 Price Equity Transaction 1-Day 30-Day Pelican Exchange Initial DCF (1) (2) (3) (4) per Share (6/4/26) VWAP Overture Low Midpoint High Value Value Ownership Ratio Metrics $12.10 $7.80 $52.26 $67.63 $37.05 $44.30 $54.10 Pelican Share $12.10 $1,411 $1,203 – +55% 9% 0.1823x $14.90 $9.33 $10.65 $12.44 Price Today 11.00 1,277 1,069 (9%) +41% 8% 0.1610x 13.48 8.55 9.72 11.30 11.50 1,338 1,130 (5%) +47% 9% 0.1707x 14.12 8.90 10.14 11.81 12.00 1,399 1,191 (1%) +54% 9% 0.1804x 14.77 9.26 10.56 12.33 12.50 1,460 1,252 +3% +60% 9% 0.1900x 15.42 9.61 10.99 12.85 13.00 1,521 1,313 +7% +67% 10% 0.1997x 16.07 9.96 11.41 13.37 13.50 1,582 1,374 +12% +73% 10% 0.2093x 16.72 10.32 11.83 13.89 14.00 1,643 1,435 +16% +79% 10% 0.2190x 17.37 10.67 12.26 14.40 14.50 1,704 1,496 +20% +86% 11% 0.2286x 18.01 11.02 12.68 14.92 15.00 1,765 1,557 +24% +92% 11% 0.2383x 18.66 11.38 13.10 15.44 Source: Pelican Management, public filings, FactSet, and Bloomberg as of 6/4/26. Note: Dollars in millions, except per share data. Analysis assumes Toucan’s $750mm of convertible senior notes due 7/15/30 with a conversion price of $84.19 and $460mm principal amount of convertible senior notes due 5/15/32 with a conversion price of $69.26 are treated as debt. (1) Based on fully diluted Pelican shares outstanding: basic shares of 106.0mm as of 5/31/26 and dilution under treasury stock method (TSM) of 15.6mm stock options with a weighted-average exercise price (WAEP) of $5.19, 0.6mm RSUs, and 0.6mm 51 PSUs all as of 5/31/26. (2) Based on estimated $210mm cash and cash equivalents as of 6/30/26 and estimated $1mm of software loans treated as debt as of 6/30/26. (3) Adjusted to reflect Toucan’s existing ownership of 13,039,067 Pelican shares, which are excluded from purchase consideration and pro forma ownership. (4) Based on Toucan’s spot (current) price of $52.26 (as of 6/4/26).
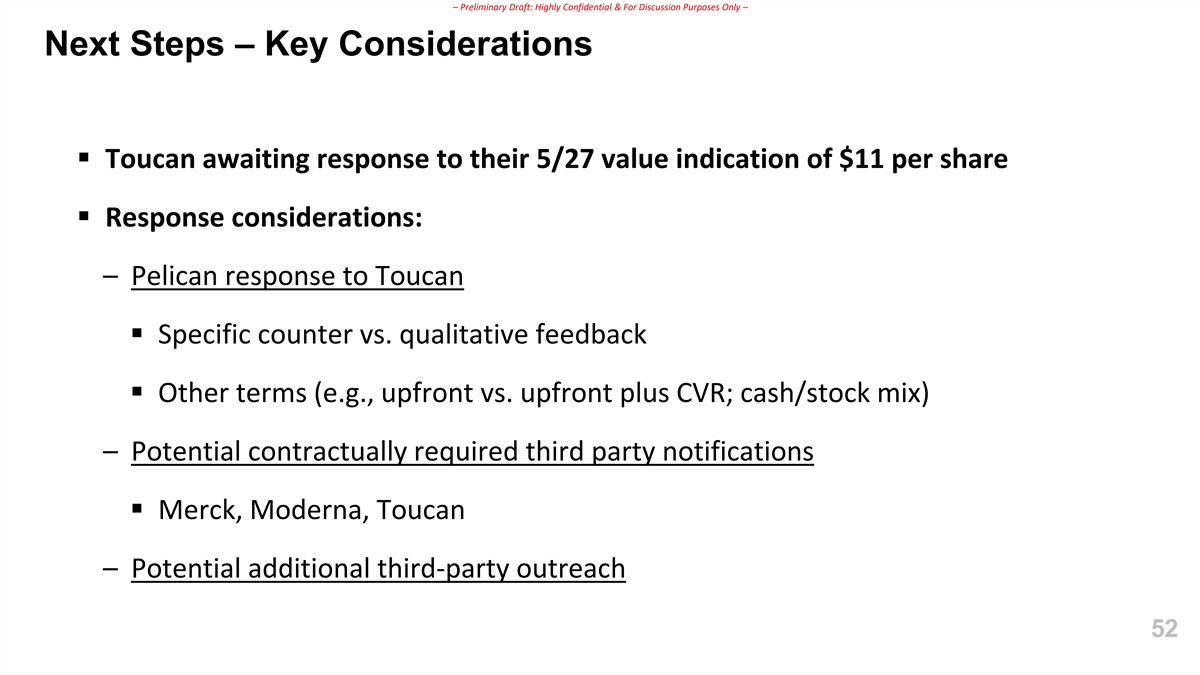
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Next Steps – Key Considerations ▪ Toucan awaiting response to their 5/27 value indication of $11 per share ▪ Response considerations: – Pelican response to Toucan ▪ Specific counter vs. qualitative feedback ▪ Other terms (e.g., upfront vs. upfront plus CVR; cash/stock mix) – Potential contractually required third party notifications ▪ Merck, Moderna, Toucan – Potential additional third-party outreach 52
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Appendix 53
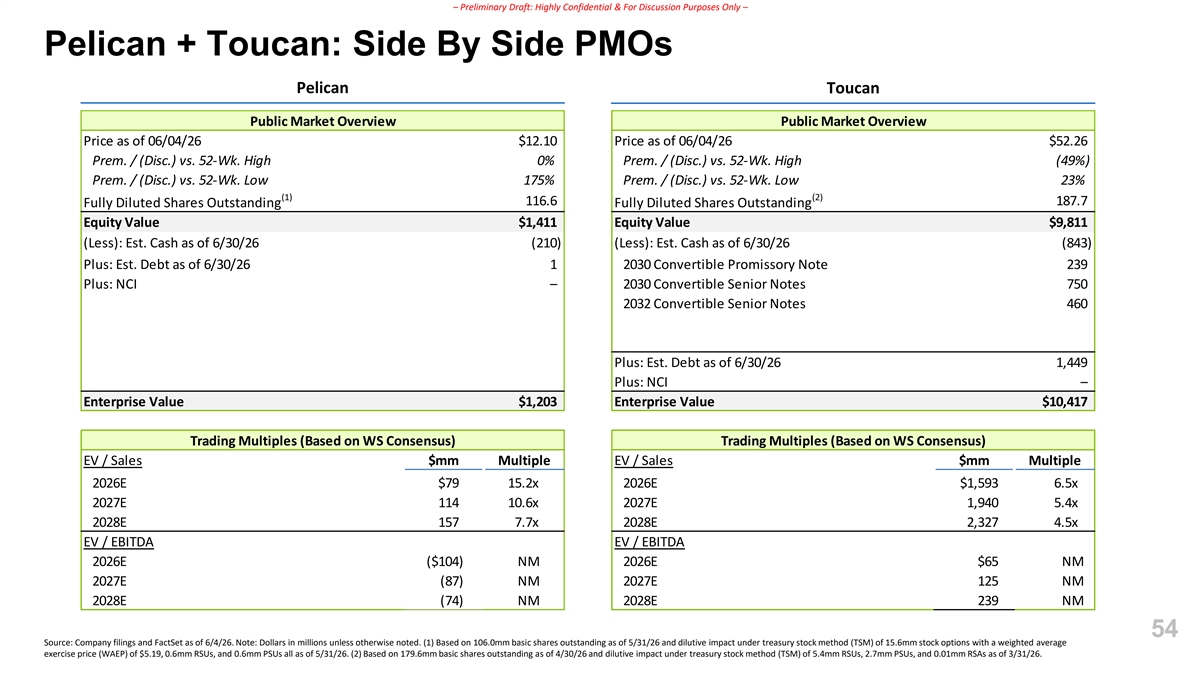
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican + Toucan: Side By Side PMOs Pelican Toucan Public Market Overview Public Market Overview Public Market Overview Price as of 06/04/26 $12.10 Price as of 06/04/26 $52.26 Prem. / (Disc.) vs. 52-Wk. High 0% Prem. / (Disc.) vs. 52-Wk. High (49%) Prem. / (Disc.) vs. 52-Wk. Low 175% Prem. / (Disc.) vs. 52-Wk. Low 23% (1) (2) 116.6 187.7 Fully Diluted Shares Outstanding Fully Diluted Shares Outstanding Equity Value $1,411 Equity Value $9,811 (Less): Est. Cash as of 6/30/26 (210) (Less): Est. Cash as of 6/30/26 (843) Plus: Est. Debt as of 6/30/26 1 2030 Convertible Promissory Note 239 Plus: NCI – 2030 Convertible Senior Notes 750 2032 Convertible Senior Notes 460 Plus: Est. Debt as of 6/30/26 1,449 Plus: NCI – Enterprise Value $1,203 Enterprise Value $10,417 Trading Multiples (Based on WS Consensus) Trading Multiples (Based on WS Consensus) Trading Multiples (Based on WS Consensus) EV / Sales $mm Multiple EV / Sales $mm Multiple 2026E $79 15.2x 2026E $1,593 6.5x 2027E 114 10.6x 2027E 1,940 5.4x 2028E 157 7.7x 2028E 2,327 4.5x EV / EBITDA EV / EBITDA 2026E ($104) NM 2026E $65 NM 2027E (87) NM 2027E 125 NM 2028E (74) NM 2028E 239 NM 54 Source: Company filings and FactSet as of 6/4/26. Note: Dollars in millions unless otherwise noted. (1) Based on 106.0mm basic shares outstanding as of 5/31/26 and dilutive impact under treasury stock method (TSM) of 15.6mm stock options with a weighted average exercise price (WAEP) of $5.19, 0.6mm RSUs, and 0.6mm PSUs all as of 5/31/26. (2) Based on 179.6mm basic shares outstanding as of 4/30/26 and dilutive impact under treasury stock method (TSM) of 5.4mm RSUs, 2.7mm PSUs, and 0.01mm RSAs as of 3/31/26.
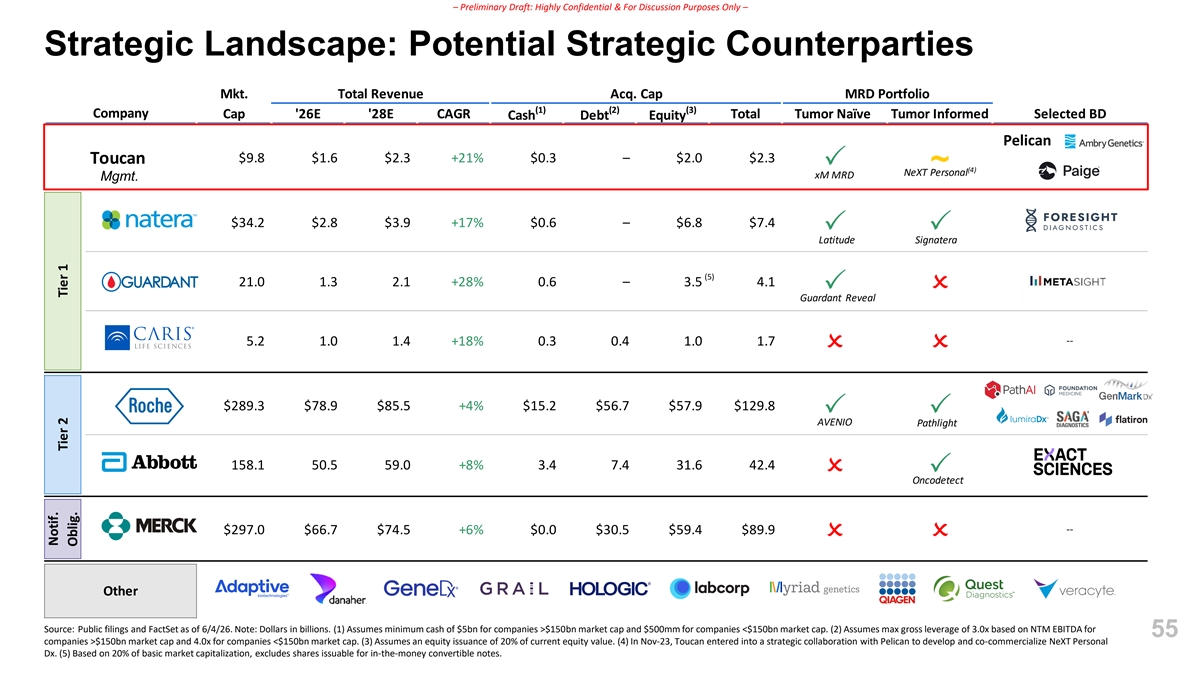
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Strategic Landscape: Potential Strategic Counterparties Mkt. Total Revenue Acq. Cap MRD Portfolio (1) (2) (3) Company Cap '26E '28E CAGR Total Tumor Naïve Tumor Informed Selected BD Cash Debt Equity Pelican $9.8 $1.6 $2.3 +21% $0.3 – $2.0 $2.3 Toucan ~ P (4) NeXT Personal xM MRD Mgmt. $34.2 $2.8 $3.9 +17% $0.6 – $6.8 $7.4 PP Latitude Signatera (5) -- 21.0 1.3 2.1 +28% 0.6 – 3.5 4.1 PO Guardant Reveal -- 5.2 1.0 1.4 +18% 0.3 0.4 1.0 1.7 OO $289.3 $78.9 $85.5 +4% $15.2 $56.7 $57.9 $129.8 PP AVENIO Pathlight 158.1 50.5 59.0 +8% 3.4 7.4 31.6 42.4 OP Oncodetect -- $297.0 $66.7 $74.5 +6% $0.0 $30.5 $59.4 $89.9 OO Other Source: Public filings and FactSet as of 6/4/26. Note: Dollars in billions. (1) Assumes minimum cash of $5bn for companies >$150bn market cap and $500mm for companies <$150bn market cap. (2) Assumes max gross leverage of 3.0x based on NTM EBITDA for 55 companies >$150bn market cap and 4.0x for companies <$150bn market cap. (3) Assumes an equity issuance of 20% of current equity value. (4) In Nov-23, Toucan entered into a strategic collaboration with Pelican to develop and co-commercialize NeXT Personal Dx. (5) Based on 20% of basic market capitalization, excludes shares issuable for in-the-money convertible notes. Notif. Tier 2 Tier 1 Oblig.
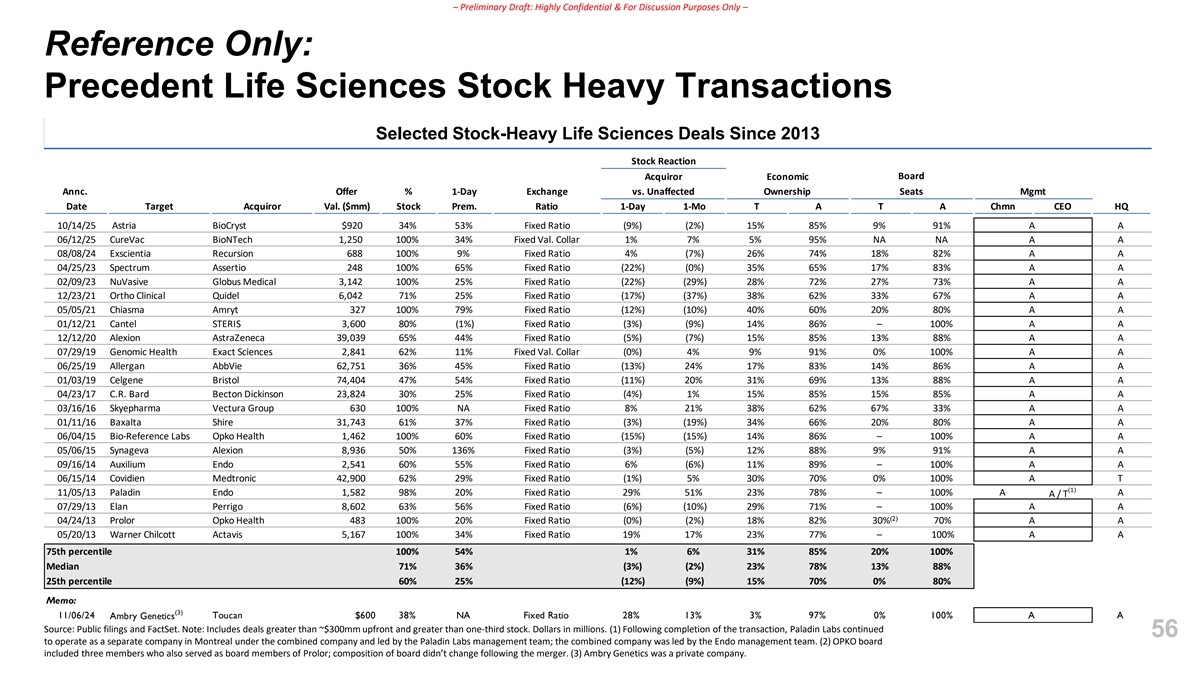
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Reference Only: Precedent Life Sciences Stock Heavy Transactions Selected Stock-Heavy Life Sciences Deals Since 2013 Stock Reaction Acquiror Economic Board ACQUIROR Annc. Offer % 1-Day Exchange vs. Unaffected Ownership Seats Mgmt Date Target Acquiror Val. ($mm) Stock Prem. Ratio 1-Day 1-Mo T A T A Chmn CEO HQ 10/14/25 Astria BioCryst $920 34% 53% Fixed Ratio (9%) (2%) 15% 85% 9% 91% A A 06/12/25 CureVac BioNTech 1,250 100% 34% Fixed Val. Collar 1% 7% 5% 95% NA NA A A 08/08/24 Exscientia Recursion 688 100% 9% Fixed Ratio 4% (7%) 26% 74% 18% 82% A A 04/25/23 Spectrum Assertio 248 100% 65% Fixed Ratio (22%) (0%) 35% 65% 17% 83% A A 02/09/23 NuVasive Globus Medical 3,142 100% 25% Fixed Ratio (22%) (29%) 28% 72% 27% 73% A A 12/23/21 Ortho Clinical Quidel 6,042 71% 25% Fixed Ratio (17%) (37%) 38% 62% 33% 67% A A 05/05/21 Chiasma Amryt 327 100% 79% Fixed Ratio (12%) (10%) 40% 60% 20% 80% A A 01/12/21 Cantel STERIS 3,600 80% (1%) Fixed Ratio (3%) (9%) 14% 86% – 100% A A 12/12/20 Alexion AstraZeneca 39,039 65% 44% Fixed Ratio (5%) (7%) 15% 85% 13% 88% A A 07/29/19 Genomic Health Exact Sciences 2,841 62% 11% Fixed Val. Collar (0%) 4% 9% 91% 0% 100% A A 06/25/19 Allergan AbbVie 62,751 36% 45% Fixed Ratio (13%) 24% 17% 83% 14% 86% A A 01/03/19 Celgene Bristol 74,404 47% 54% Fixed Ratio (11%) 20% 31% 69% 13% 88% A A 04/23/17 C.R. Bard Becton Dickinson 23,824 30% 25% Fixed Ratio (4%) 1% 15% 85% 15% 85% A A 03/16/16 Skyepharma Vectura Group 630 100% NA Fixed Ratio 8% 21% 38% 62% 67% 33% A A 01/11/16 Baxalta Shire 31,743 61% 37% Fixed Ratio (3%) (19%) 34% 66% 20% 80% A A 06/04/15 Bio-Reference Labs Opko Health 1,462 100% 60% Fixed Ratio (15%) (15%) 14% 86% – 100% A A 05/06/15 Synageva Alexion 8,936 50% 136% Fixed Ratio (3%) (5%) 12% 88% 9% 91% A A 09/16/14 Auxilium Endo 2,541 60% 55% Fixed Ratio 6% (6%) 11% 89% – 100% A A 06/15/14 Covidien Medtronic 42,900 62% 29% Fixed Ratio (1%) 5% 30% 70% 0% 100% A T (1) 11/05/13 Paladin Endo 1,582 98% 20% Fixed Ratio 29% 51% 23% 78% – 100% A A A / T 07/29/13 Elan Perrigo 8,602 63% 56% Fixed Ratio (6%) (10%) 29% 71% – 100% A A (2) 04/24/13 Prolor Opko Health 483 100% 20% Fixed Ratio (0%) (2%) 18% 82% 30% 70% A A 05/20/13 Warner Chilcott Actavis 5,167 100% 34% Fixed Ratio 19% 17% 23% 77% – 100% A A 75th percentile 100% 54% 1% 6% 31% 85% 20% 100% Median 71% 36% (3%) (2%) 23% 78% 13% 88% 25th percentile 60% 25% (12%) (9%) 15% 70% 0% 80% Memo: (3) 11/06/24 Ambry Genetics Toucan $600 38% NA Fixed Ratio 28% 13% 3% 97% 0% 100% A A Source: Public filings and FactSet. Note: Includes deals greater than ~$300mm upfront and greater than one-third stock. Dollars in millions. (1) Following completion of the transaction, Paladin Labs continued 56 to operate as a separate company in Montreal under the combined company and led by the Paladin Labs management team; the combined company was led by the Endo management team. (2) OPKO board included three members who also served as board members of Prolor; composition of board didn’t change following the merger. (3) Ambry Genetics was a private company.
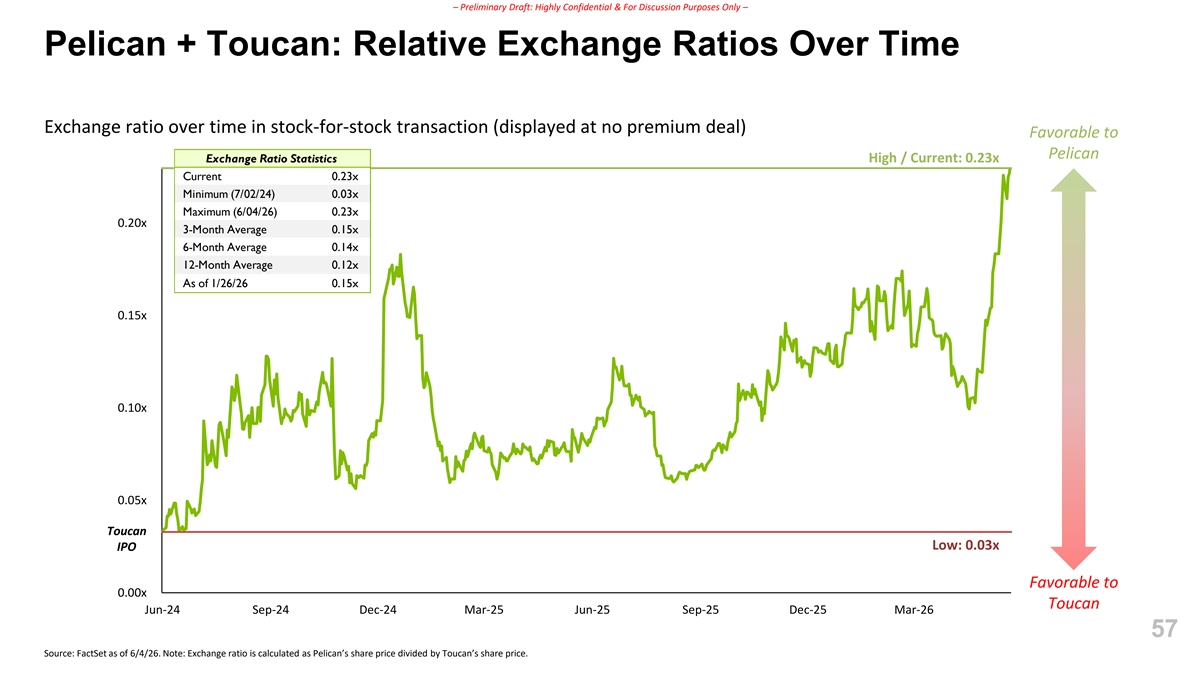
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican + Toucan: Relative Exchange Ratios Over Time Exchange ratio over time in stock-for-stock transaction (displayed at no premium deal) Favorable to Pelican Exchange Ratio Statistics High / Current: 0.23x Current 0.23x Minimum (7/02/24) 0.03x Maximum (6/04/26) 0.23x 0.20x 3-Month Average 0.15x 6-Month Average 0.14x 12-Month Average 0.12x As of 1/26/26 0.15x 0.15x 0.10x 0.05x Toucan Low: 0.03x IPO Favorable to 0.00x Toucan Jun-24 Sep-24 Dec-24 Mar-25 Jun-25 Sep-25 Dec-25 Mar-26 57 Source: FactSet as of 6/4/26. Note: Exchange ratio is calculated as Pelican’s share price divided by Toucan’s share price.
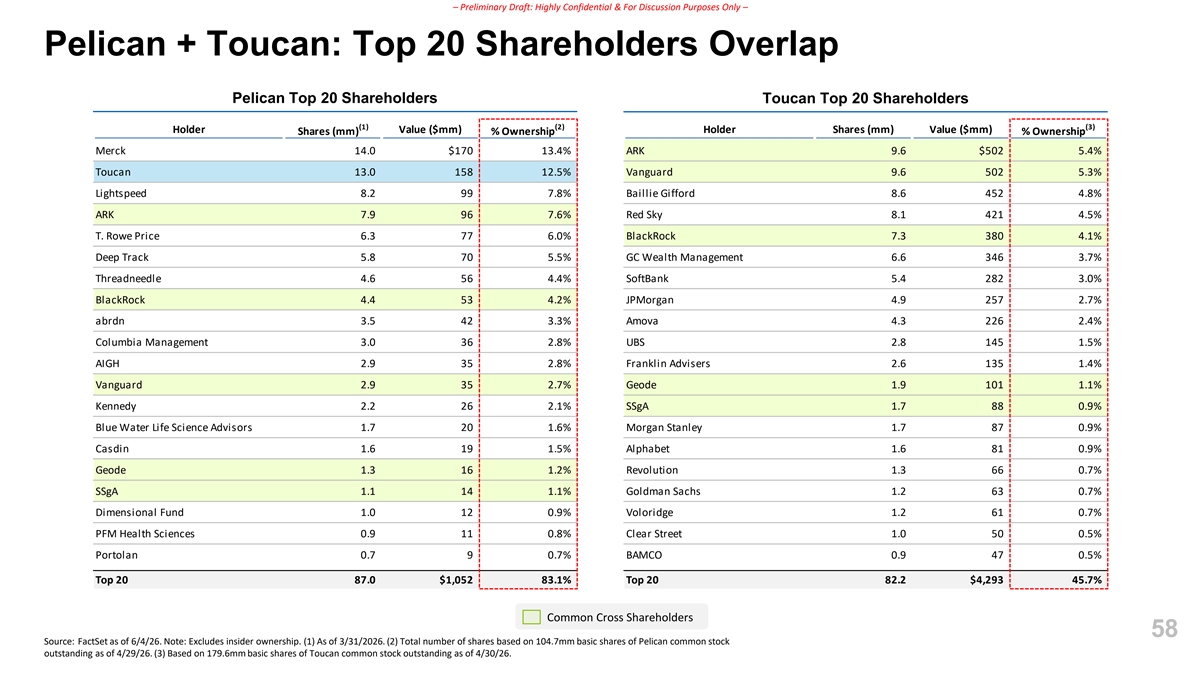
– Preliminary Draft: Highly Confidential & For Discussion Purposes Only – Pelican + Toucan: Top 20 Shareholders Overlap Pelican Top 20 Shareholders Toucan Top 20 Shareholders (1) (2) (3) Holder Value ($mm) Holder Shares (mm) Value ($mm) Shares (mm) % Ownership % Ownership Merck 14.0 $170 13.4% ARK 9.6 $502 5.4% Toucan 13.0 158 12.5% Vanguard 9.6 502 5.3% Lightspeed 8.2 99 7.8% Baillie Gifford 8.6 452 4.8% ARK 7.9 96 7.6% Red Sky 8.1 421 4.5% T. Rowe Price 6.3 77 6.0% BlackRock 7.3 380 4.1% Deep Track 5.8 70 5.5% GC Wealth Management 6.6 346 3.7% Threadneedle 4.6 56 4.4% SoftBank 5.4 282 3.0% BlackRock 4.4 53 4.2% JPMorgan 4.9 257 2.7% abrdn 3.5 42 3.3% Amova 4.3 226 2.4% Columbia Management 3.0 36 2.8% UBS 2.8 145 1.5% AIGH 2.9 35 2.8% Franklin Advisers 2.6 135 1.4% Vanguard 2.9 35 2.7% Geode 1.9 101 1.1% Kennedy 2.2 26 2.1% SSgA 1.7 88 0.9% Blue Water Life Science Advisors 1.7 20 1.6% Morgan Stanley 1.7 87 0.9% Casdin 1.6 19 1.5% Alphabet 1.6 81 0.9% Geode 1.3 16 1.2% Revolution 1.3 66 0.7% SSgA 1.1 14 1.1% Goldman Sachs 1.2 63 0.7% Dimensional Fund 1.0 12 0.9% Voloridge 1.2 61 0.7% PFM Health Sciences 0.9 11 0.8% Clear Street 1.0 50 0.5% Portolan 0.7 9 0.7% BAMCO 0.9 47 0.5% Top 20 87.0 $1,052 83.1% Top 20 82.2 $4,293 45.7% Common Cross Shareholders 58 Source: FactSet as of 6/4/26. Note: Excludes insider ownership. (1) As of 3/31/2026. (2) Total number of shares based on 104.7mm basic shares of Pelican common stock outstanding as of 4/29/26. (3) Based on 179.6mm basic shares of Toucan common stock outstanding as of 4/30/26.
Exhibit (c)(9)
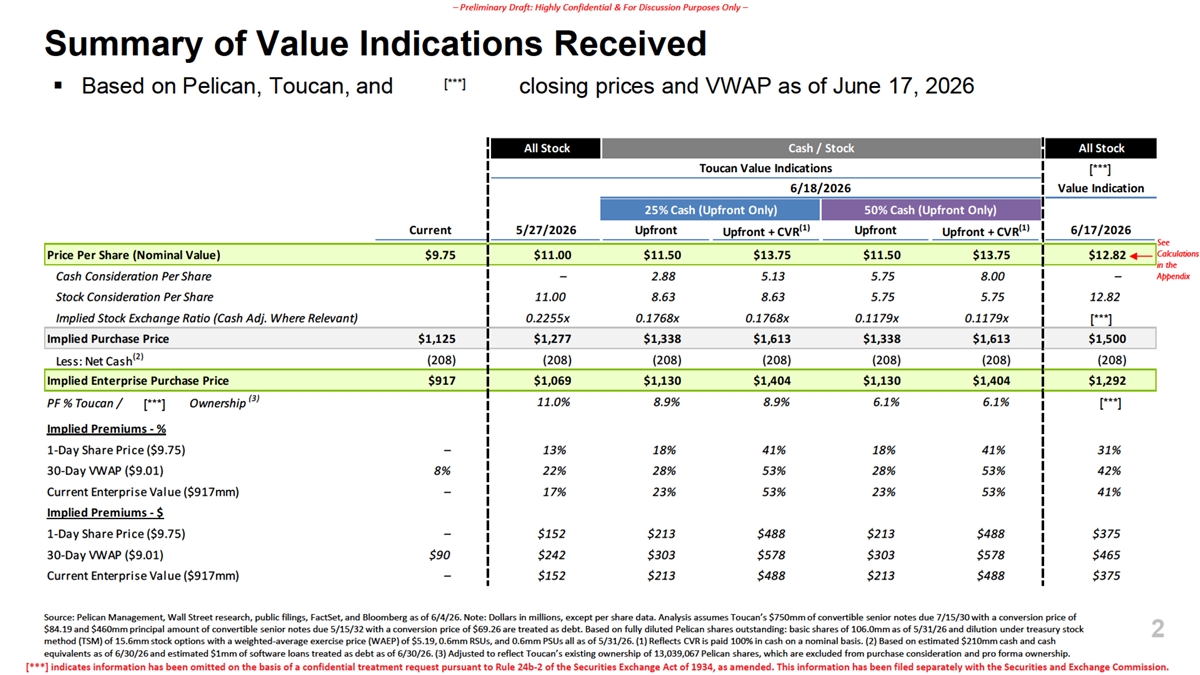
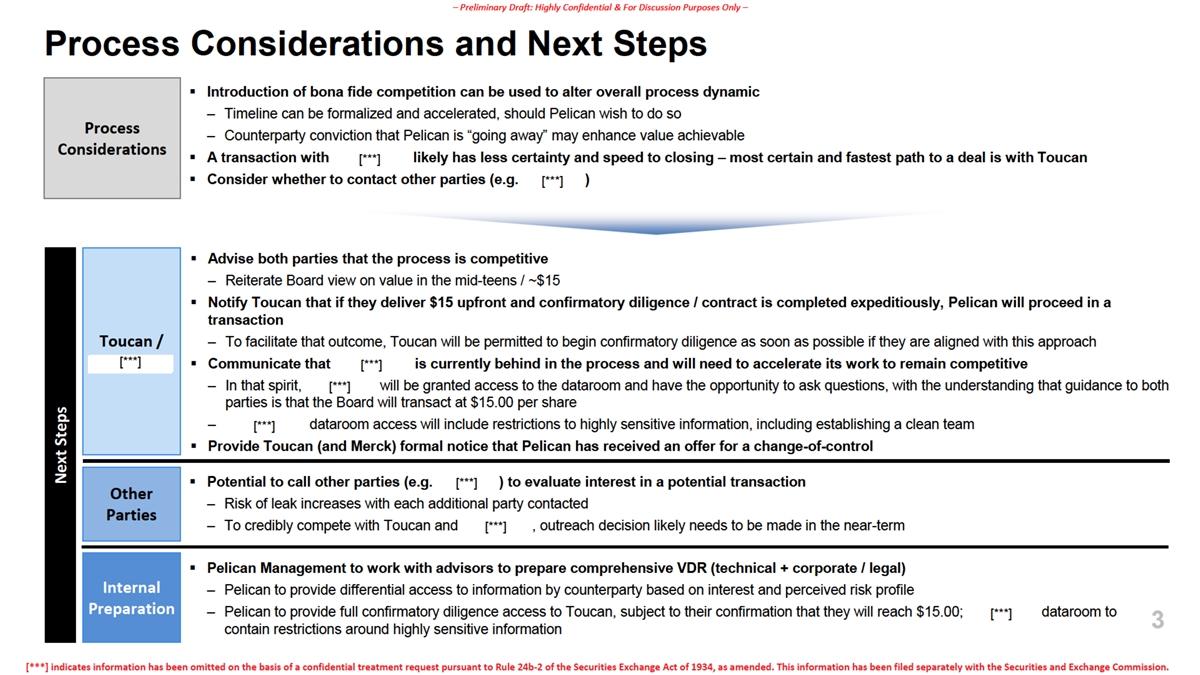
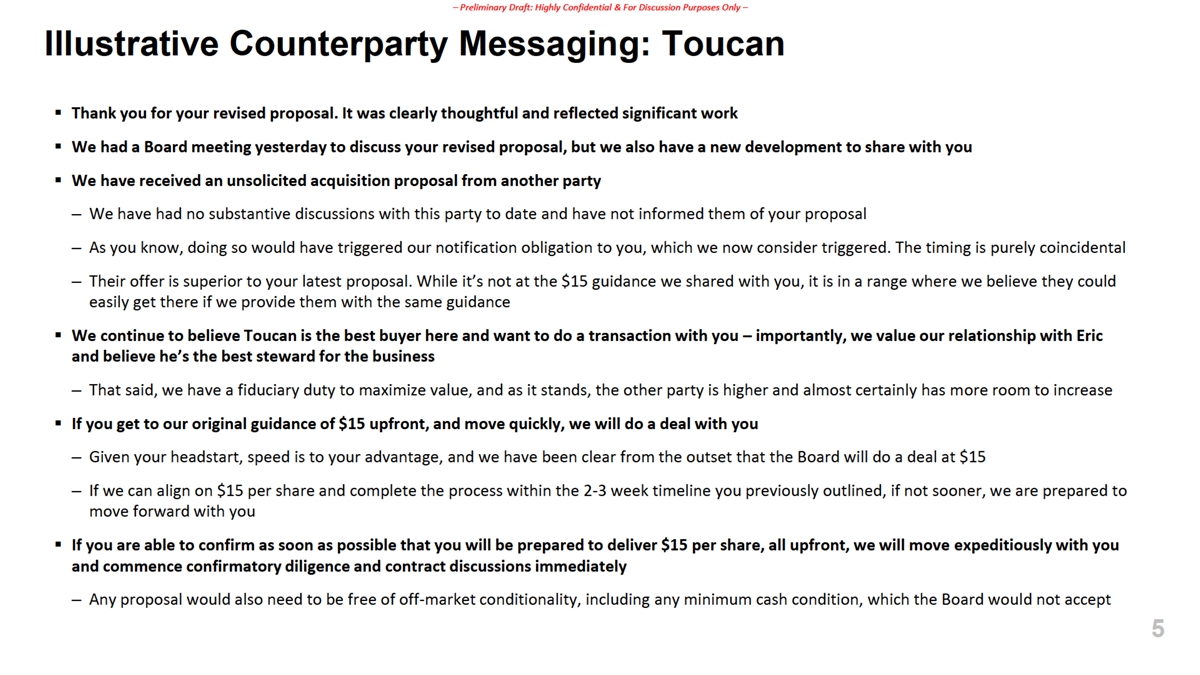
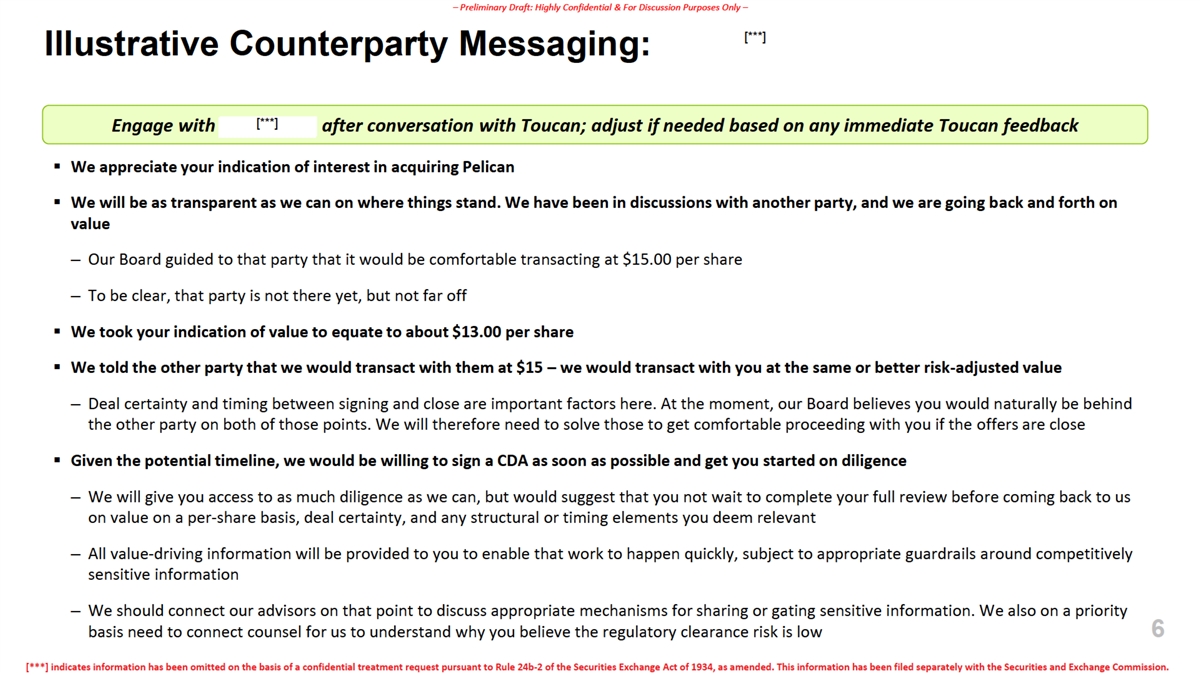
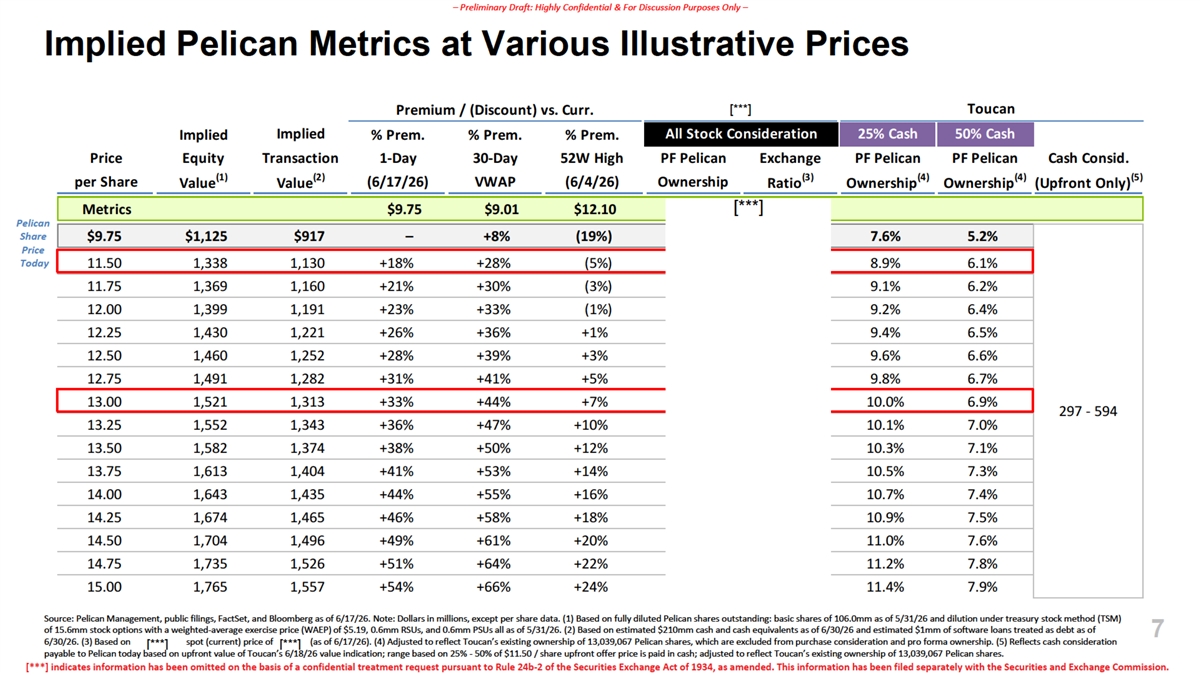
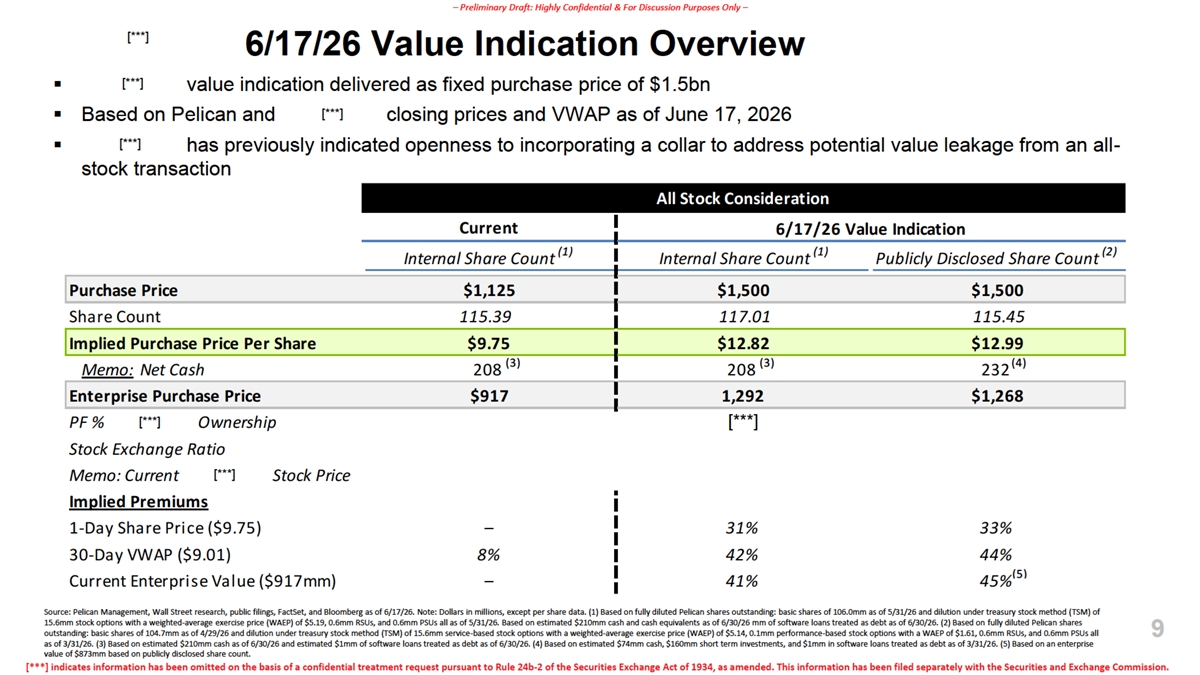
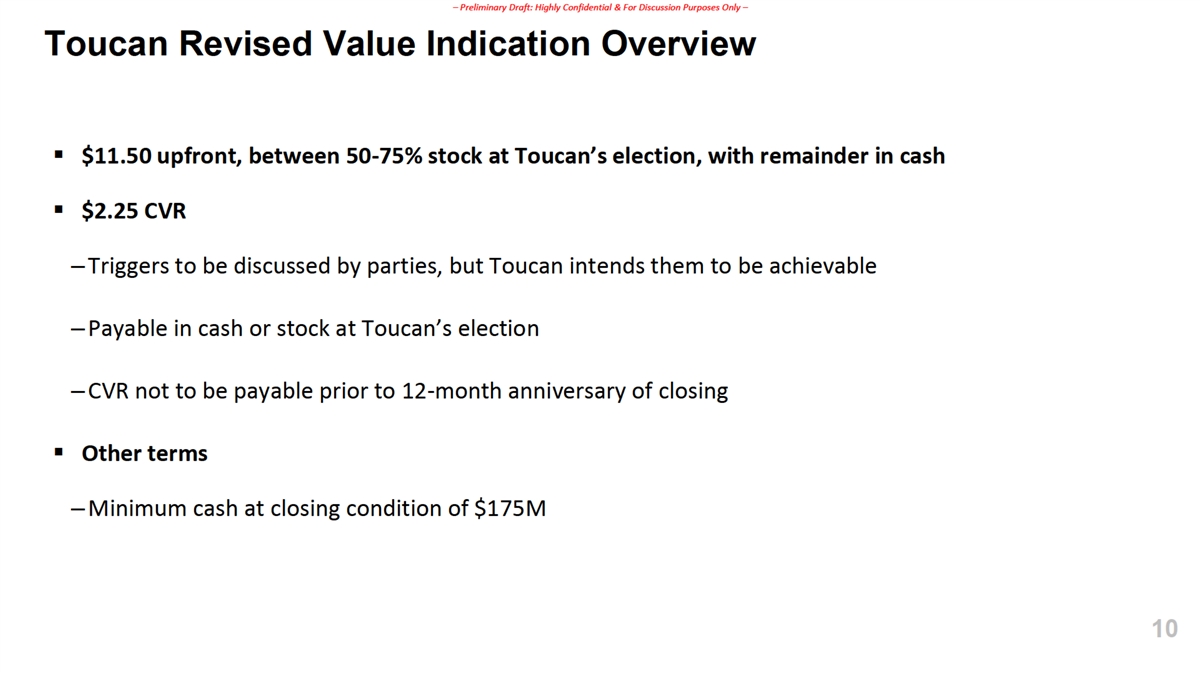
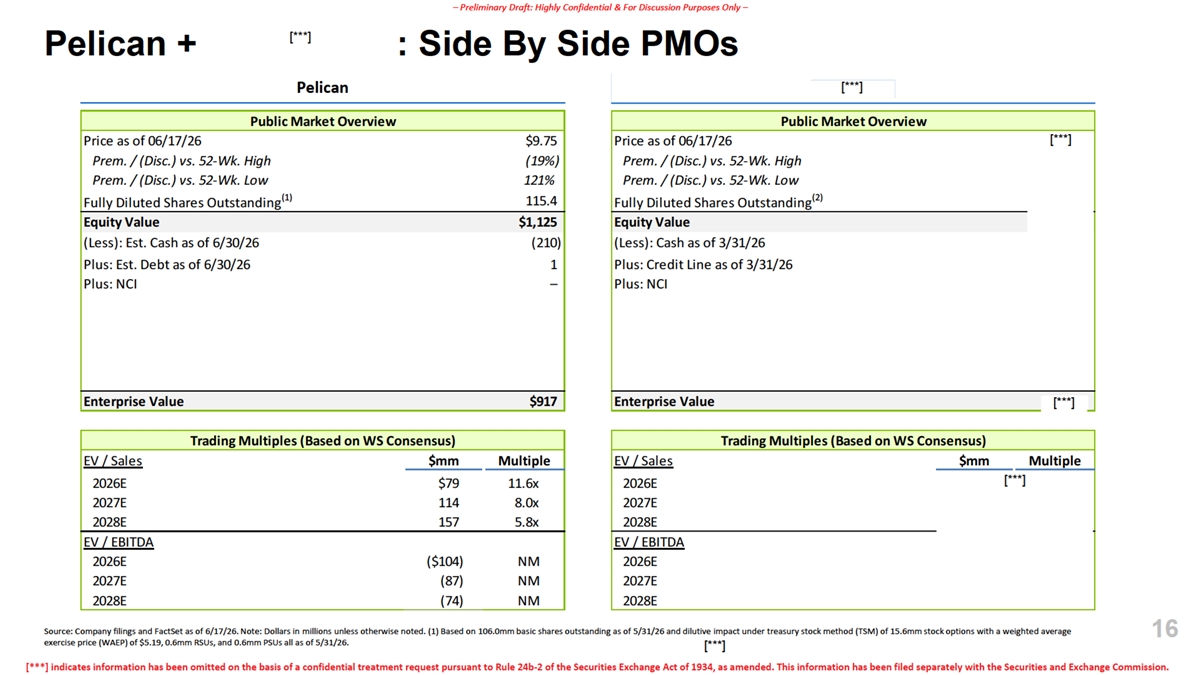
Exhibit (c)(10)
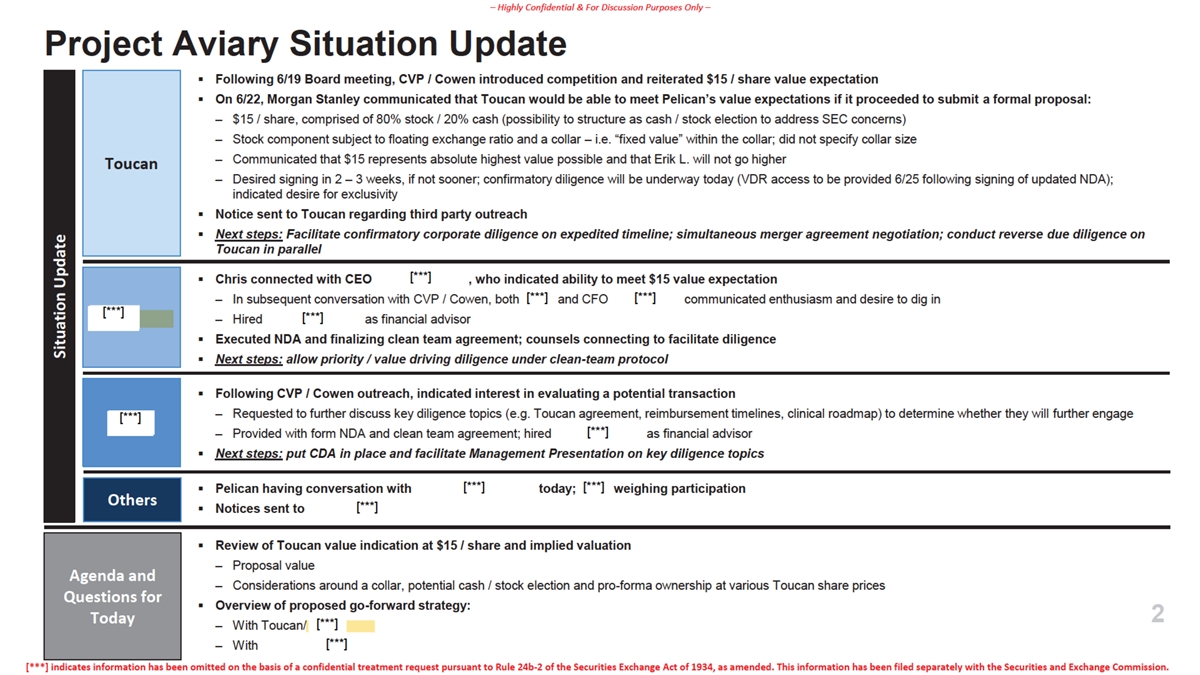
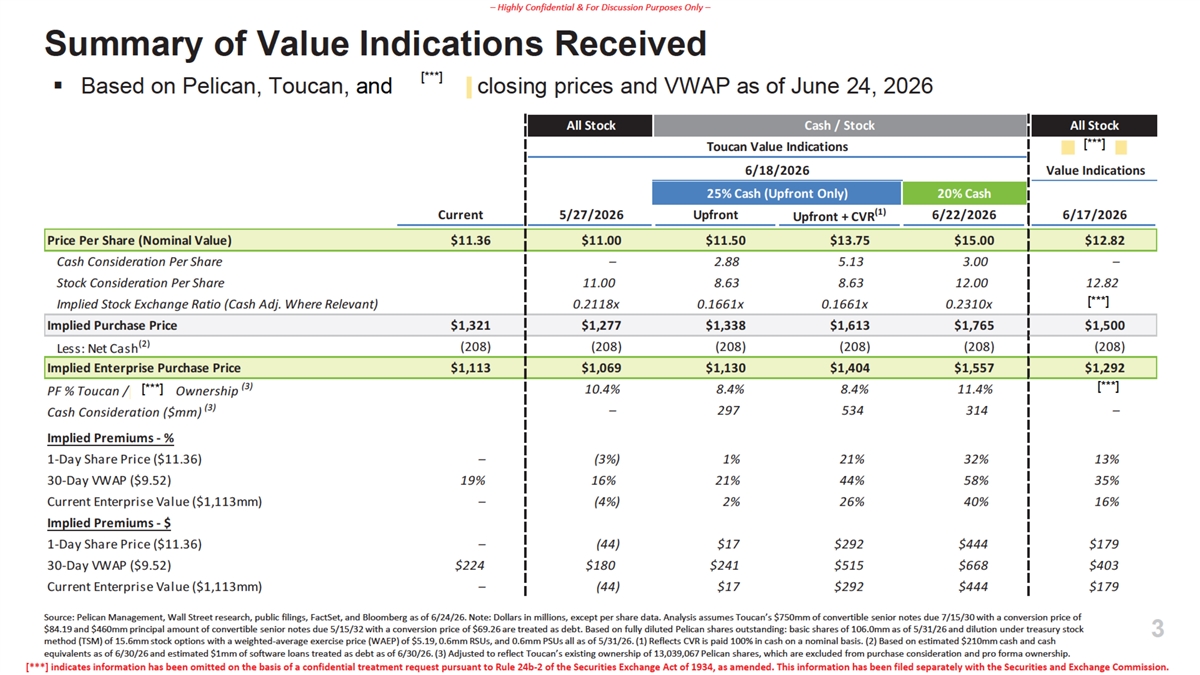
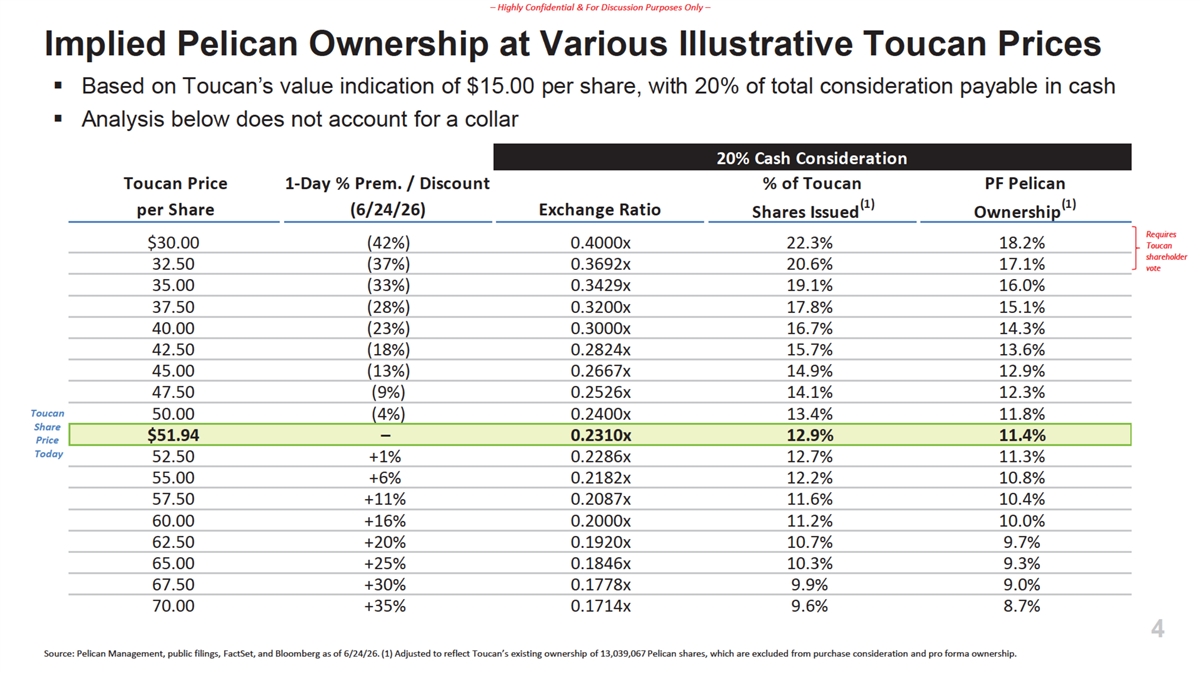
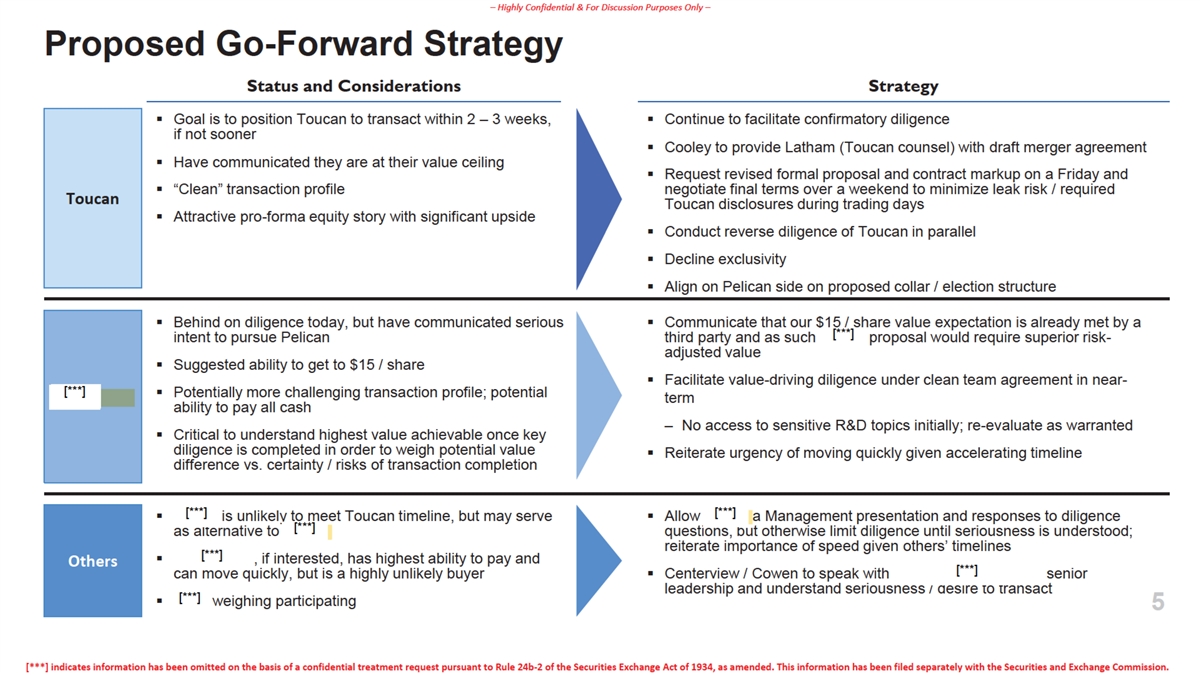
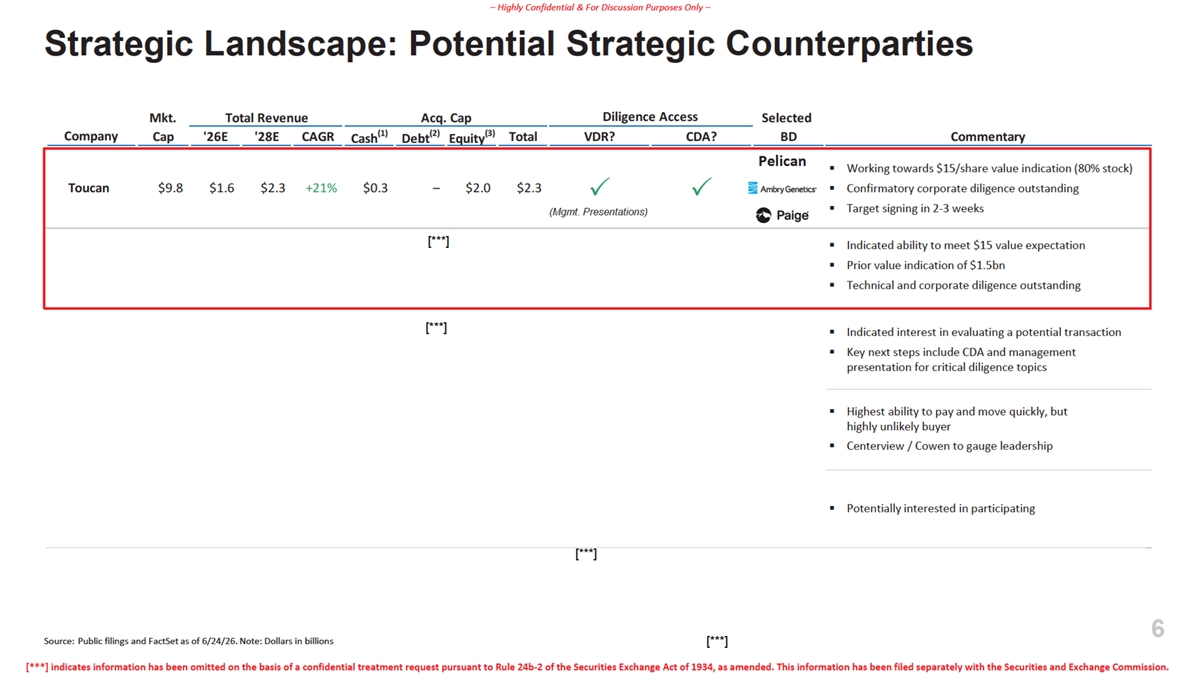
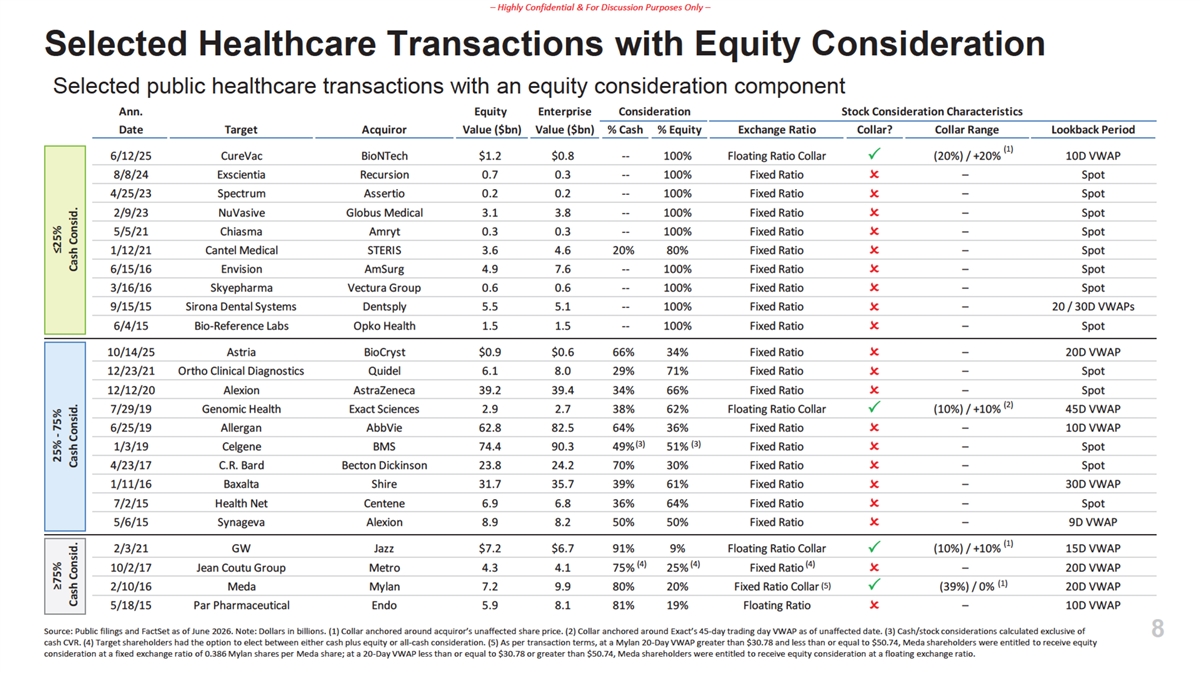
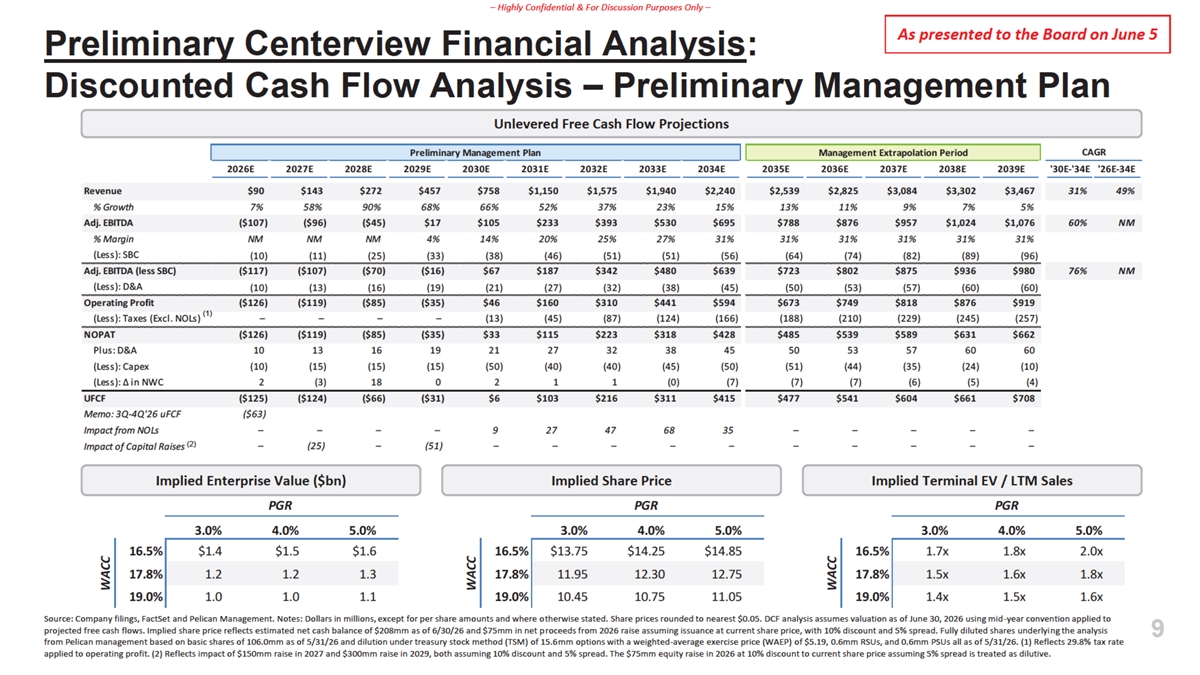
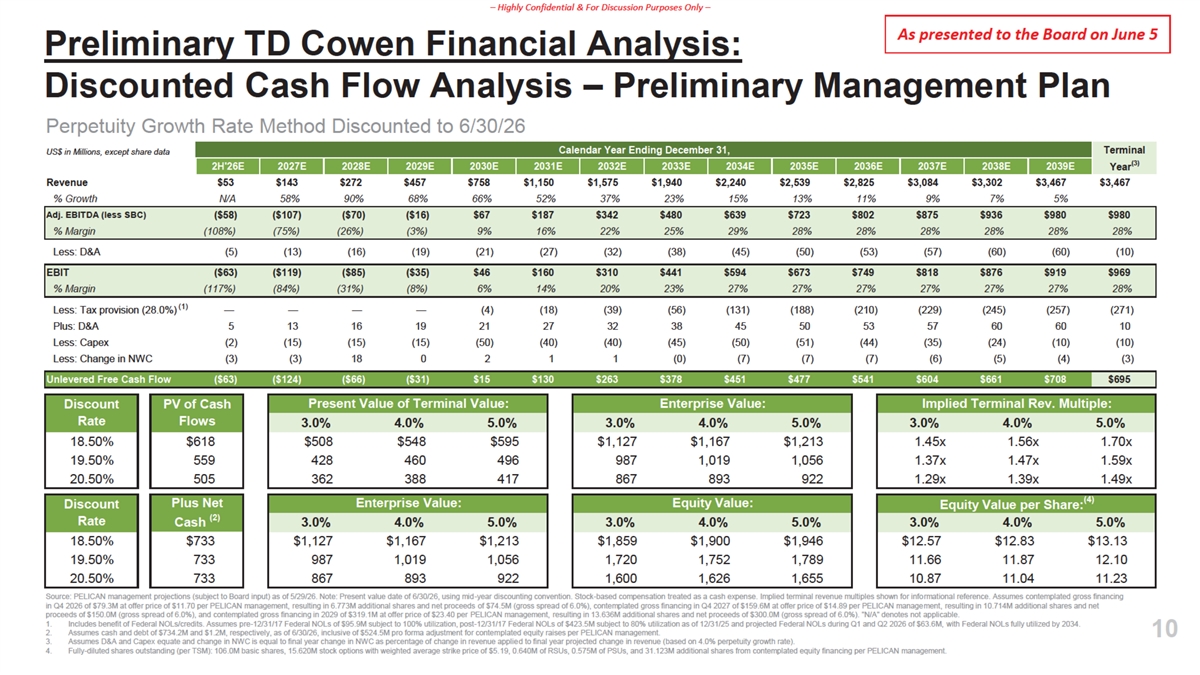
Exhibit (c)(11)
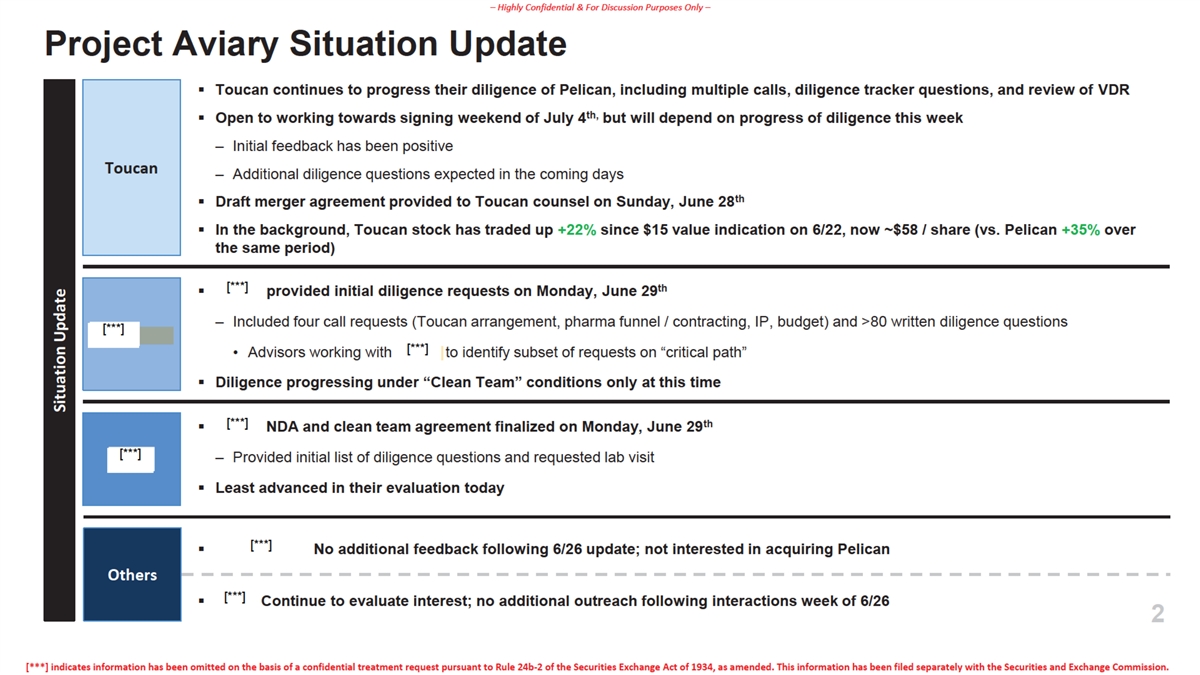
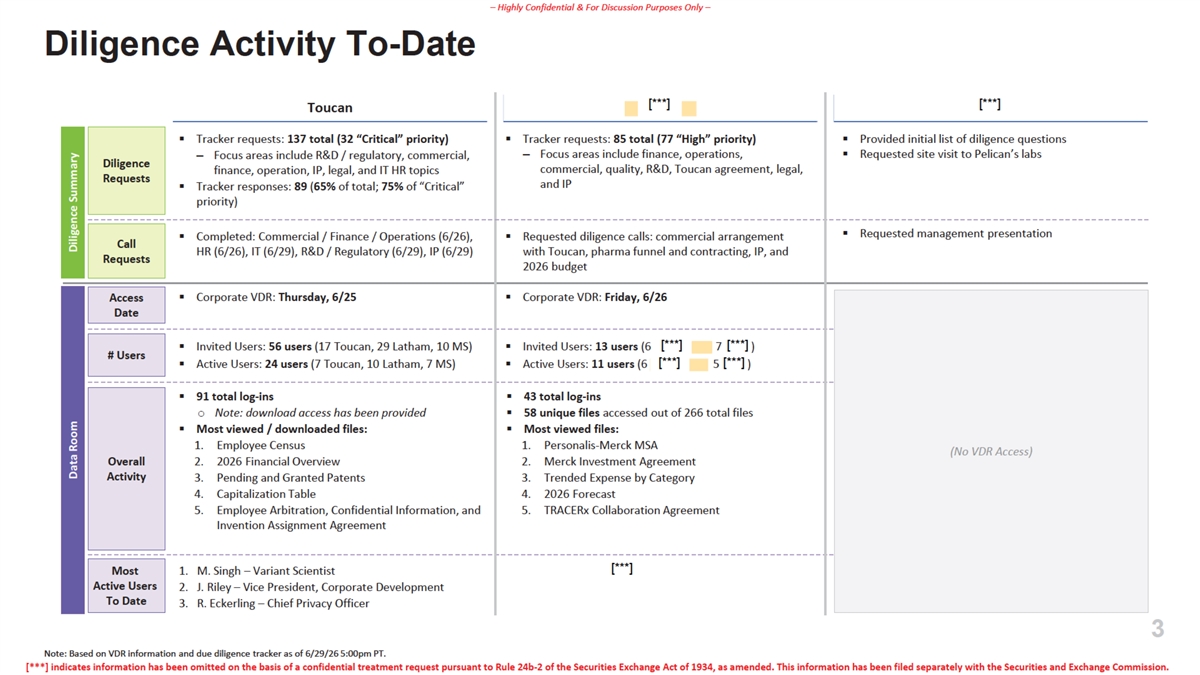
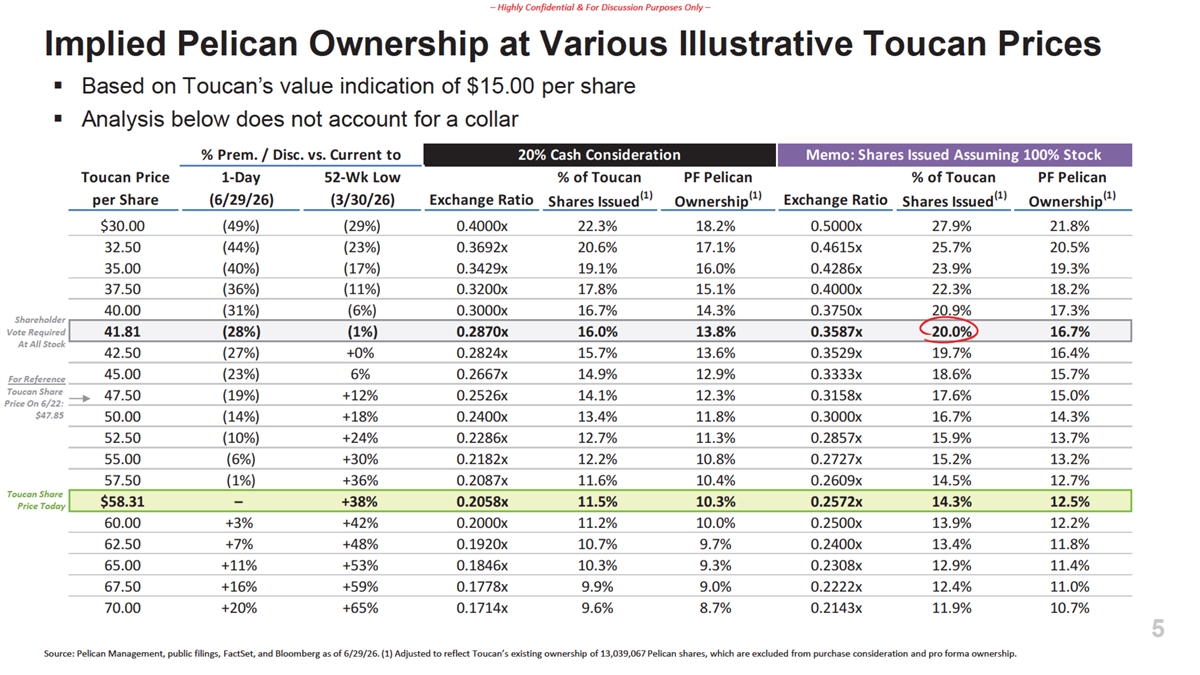
Exhibit (c)(12) Project Aviary Presentation to the Board of Directors July 2, 2026
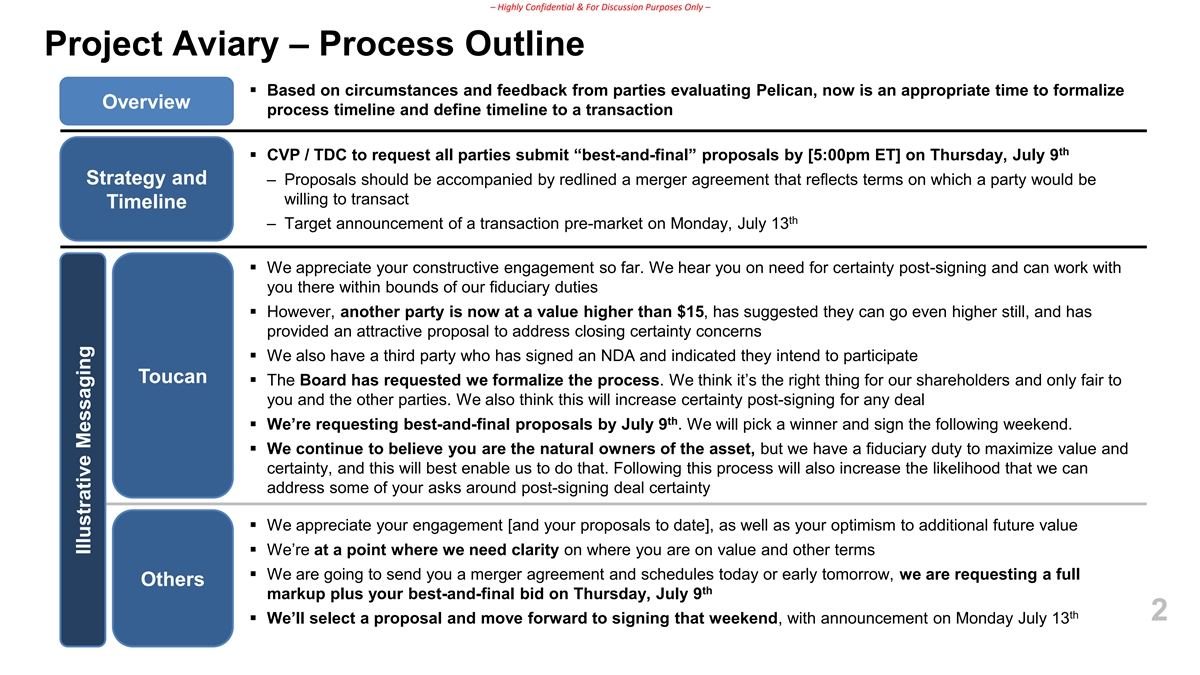
– Highly Confidential & For Discussion Purposes Only – Project Aviary – Process Outline ▪ Based on circumstances and feedback from parties evaluating Pelican, now is an appropriate time to formalize Overview process timeline and define timeline to a transaction th ▪ CVP / TDC to request all parties submit “best-and-final” proposals by [5:00pm ET] on Thursday, July 9 Strategy and – Proposals should be accompanied by redlined a merger agreement that reflects terms on which a party would be willing to transact Timeline th – Target announcement of a transaction pre-market on Monday, July 13 ▪ We appreciate your constructive engagement so far. We hear you on need for certainty post-signing and can work with you there within bounds of our fiduciary duties ▪ However, another party is now at a value higher than $15, has suggested they can go even higher still, and has provided an attractive proposal to address closing certainty concerns ▪ We also have a third party who has signed an NDA and indicated they intend to participate Toucan ▪ The Board has requested we formalize the process. We think it’s the right thing for our shareholders and only fair to you and the other parties. We also think this will increase certainty post-signing for any deal th ▪ We’re requesting best-and-final proposals by July 9 . We will pick a winner and sign the following weekend. ▪ We continue to believe you are the natural owners of the asset, but we have a fiduciary duty to maximize value and certainty, and this will best enable us to do that. Following this process will also increase the likelihood that we can address some of your asks around post-signing deal certainty ▪ We appreciate your engagement [and your proposals to date], as well as your optimism to additional future value ▪ We’re at a point where we need clarity on where you are on value and other terms ▪ We are going to send you a merger agreement and schedules today or early tomorrow, we are requesting a full Others th markup plus your best-and-final bid on Thursday, July 9 th 2 ▪ We’ll select a proposal and move forward to signing that weekend, with announcement on Monday July 13 Illustrative Messaging
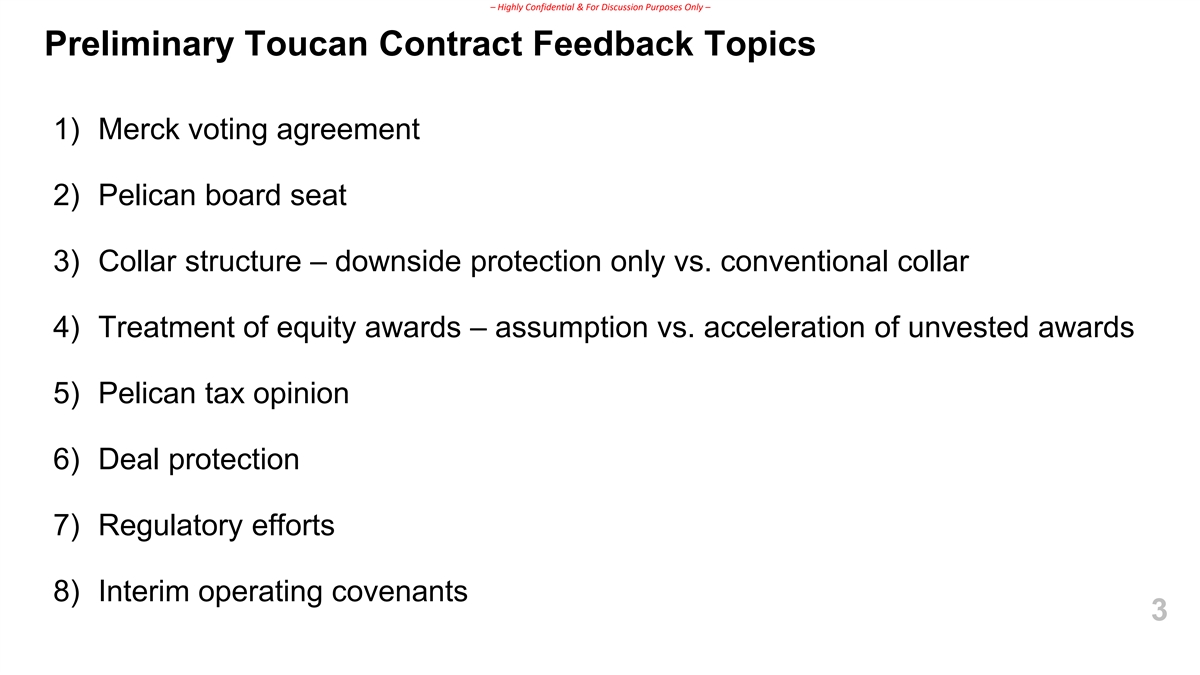
– Highly Confidential & For Discussion Purposes Only – Preliminary Toucan Contract Feedback Topics 1) Merck voting agreement 2) Pelican board seat 3) Collar structure – downside protection only vs. conventional collar 4) Treatment of equity awards – assumption vs. acceleration of unvested awards 5) Pelican tax opinion 6) Deal protection 7) Regulatory efforts 8) Interim operating covenants 3
Exhibit (c)(13)
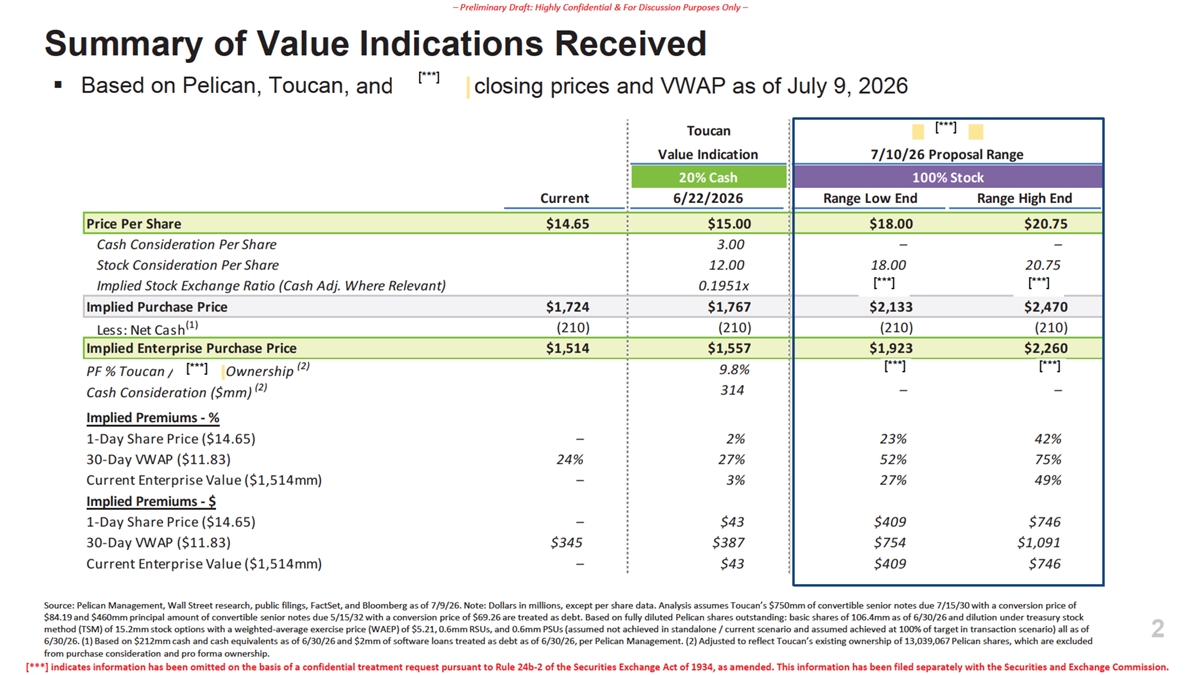
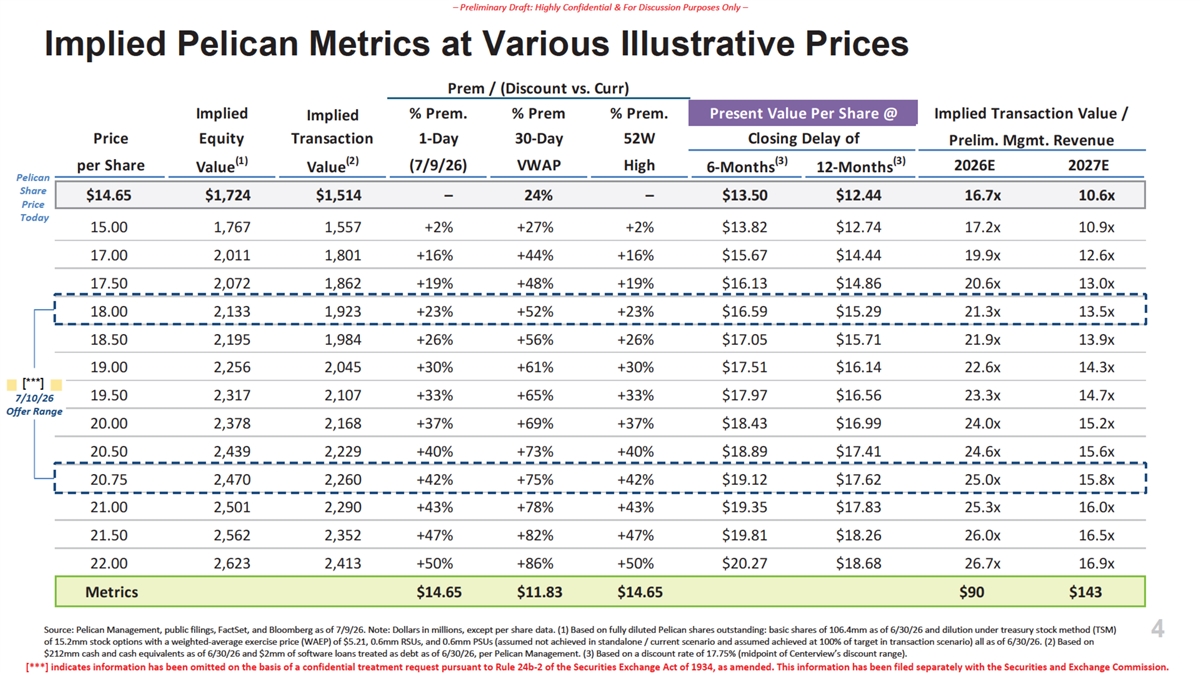
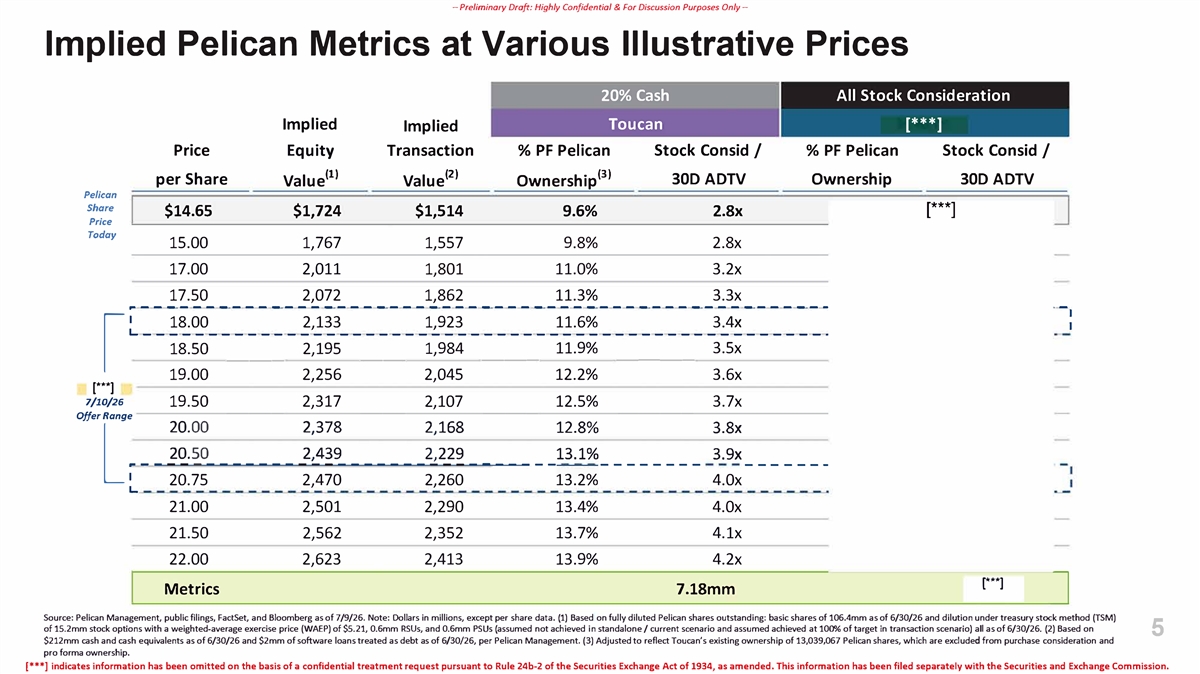
- Preliminary Draft: Highly Confidential & For Discussion Purposes Only - Implied Pelican Metrics at Various Illustrative Prices 20% Cash All Stock Consideration Implied Toucan [***] Implied Price Transaction % PF Pelican Stock Consid / % PF Pelican Stock Consid / Equity 1 2 3 < l < < per Share 30D ADTV Ownership 30D ADTV Value Value l Ownership l Pelican Share $14.65 $1,724 $1,514 9.6% 2.8x [***] Price Today 15.00 1,767 1,557 9.8% 2.8x 17.00 2,011 1,801 11.0% 3.2x 17.50 2,072 1,862 11.3% 3.3x .--.--��-���-���-���-���-���-���-���-���-���-���-���-���-- -. 1 1 18.00 2,133 1,923 11.6% 3.4X I .___ �- �- �- �- �- �- �- �- �- �- �- �- �- �- �- �- �- �- �- �- �- �- �- �- �- �- 3.5x 18.50 2,195 1,984 11.9% ___ __ ___ ____ 19.00 2,256 2,045 12.2% 3.6x [***] 1/10/26 19.50 2,317 2,107 12.5% 3.7x _ _ _ Offer Range __ __ __ ___ L -- _ ;� �� - - - - - - _ ;�!;:_ ------���;; ___ ----�!:�� -------- :::: ------ 20.75 2,470 2,260 13.2% 4.0x � 21.00 2,501 2,290 13.4% 4.0x 21.50 2,562 2,352 13.7% 4.lx 22.00 2,623 2,413 13.9% 4.2x [***] Metrics 7.18mm 7 Source: Pelican Management, public filings, FactSet, and Bloomberg as of 7 /9/26. Note: Dollars in millions, except per share data. (1) Based on fully diluted Pelican shares outstanding: basic shares of 106.4mm as of 6/30/26 and dilution under treasury stock method (TSM) of 15.2mm stock options with a weighted-average exercise price (WAEP) of $5.21, 0.6mm RSUs, and 0.6mm PSUs (assumed not achieved in standalone/ current soenario and assumed achieved at 1000/4 of target in transaction scenario) all as of 6/30/26. (2) Based on 5 $212mm cash and cash equivalents as of 6/30/26 and $2mm of software loans treated as debt as of 6/30/26, per Pelican Management. (3) Adjusted to reflect Toucan's existing ownership of 13,039,067 Pelican shares, which are excluded from purchase consideration and pro forma ownership. (***) indicates information has been omitted on the basis of a confidential treatment request pursuant to Rule 24b-2 of the Securities Exchange Act of 1934, as amended. This information has been filed separately with the Securities and Exchange Commission.
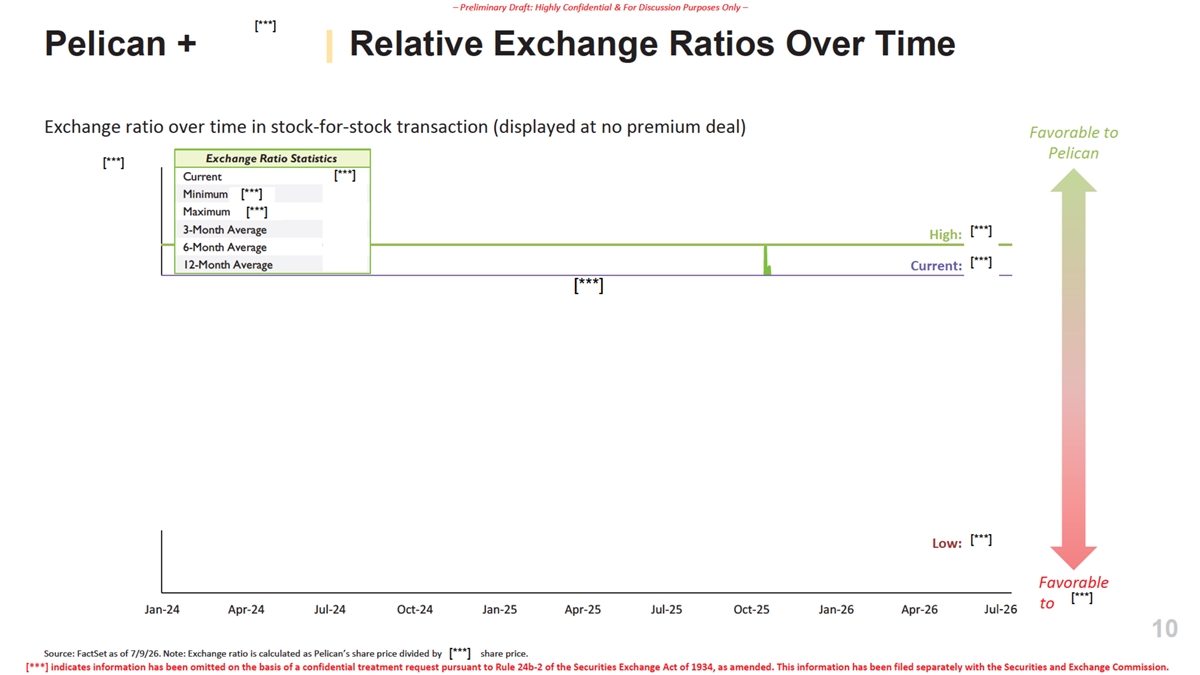
Exhibit (c)(14)
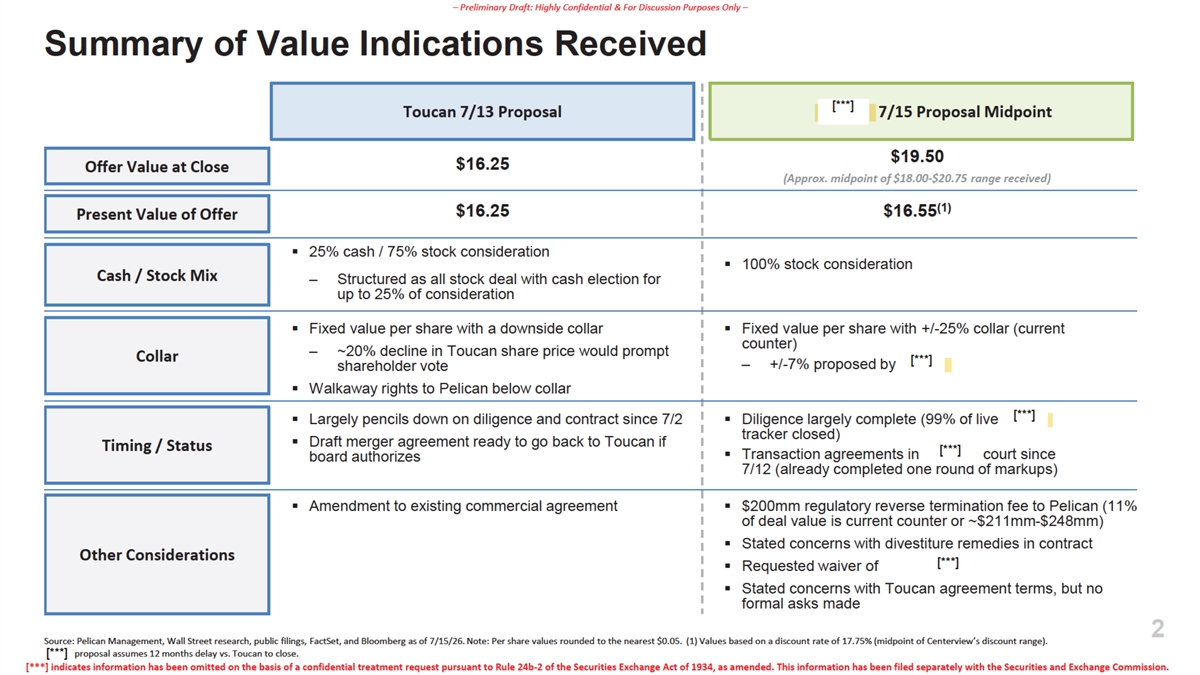
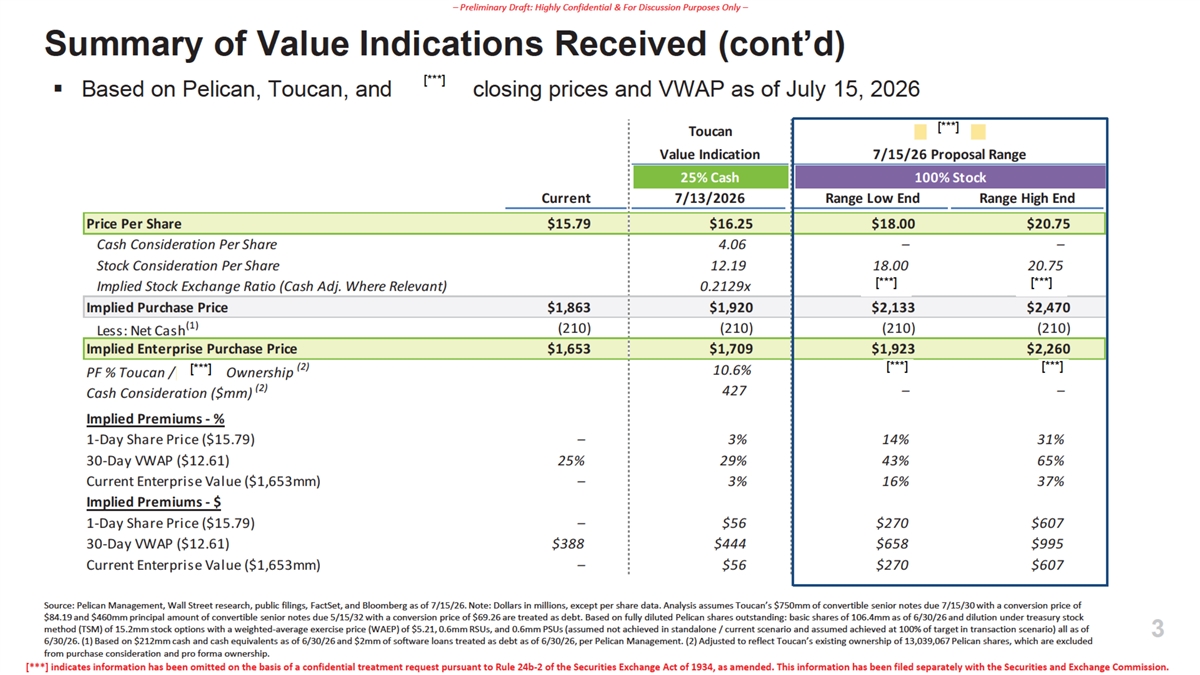
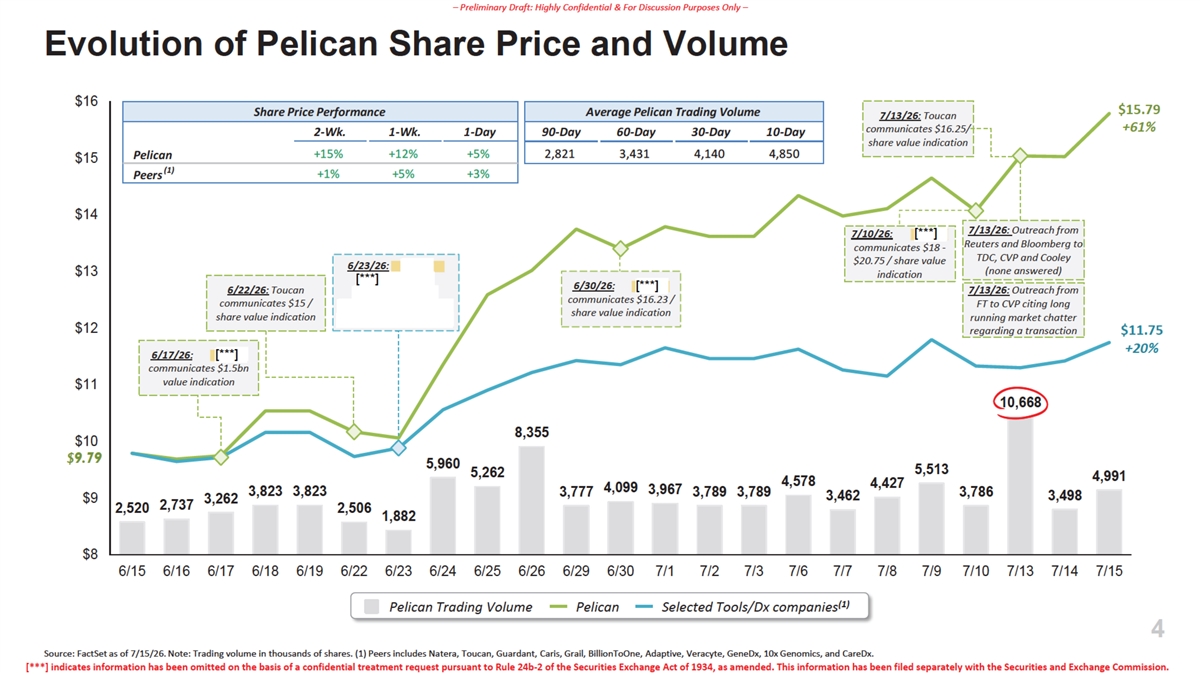
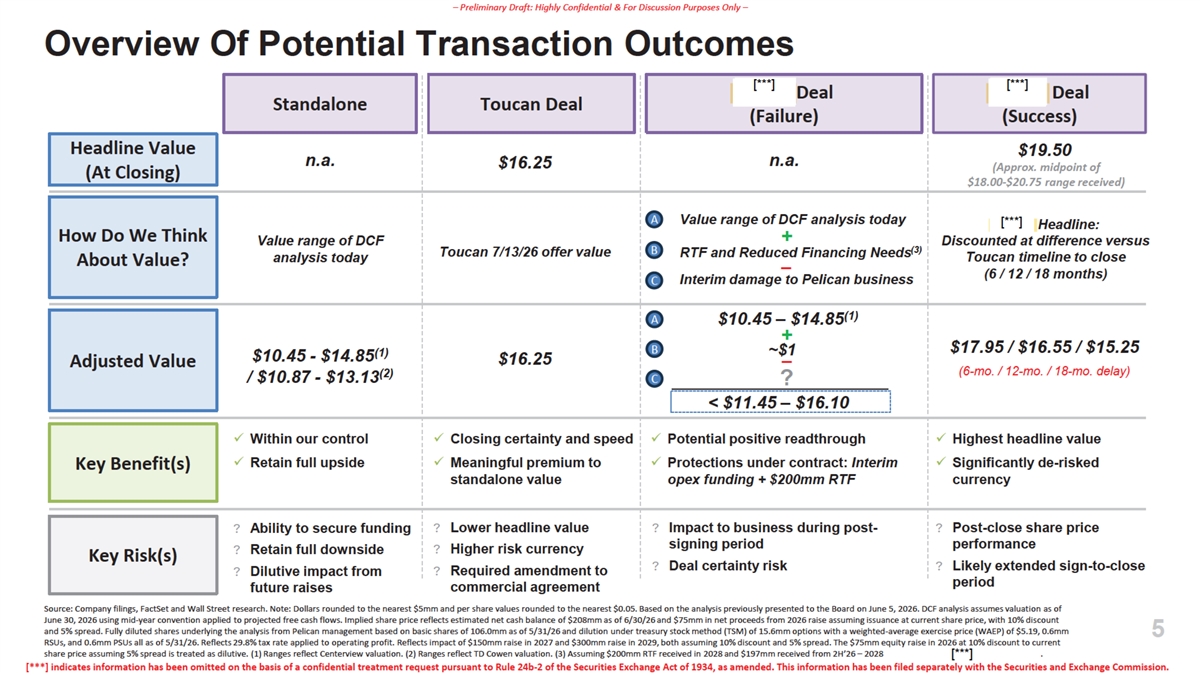
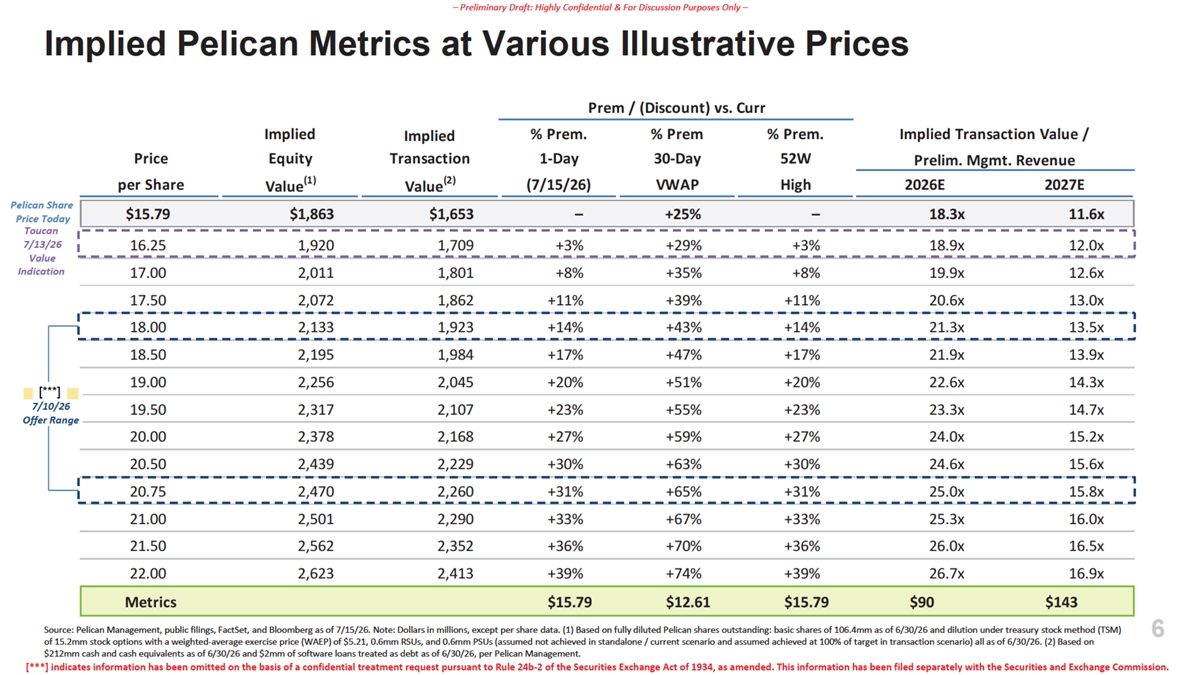
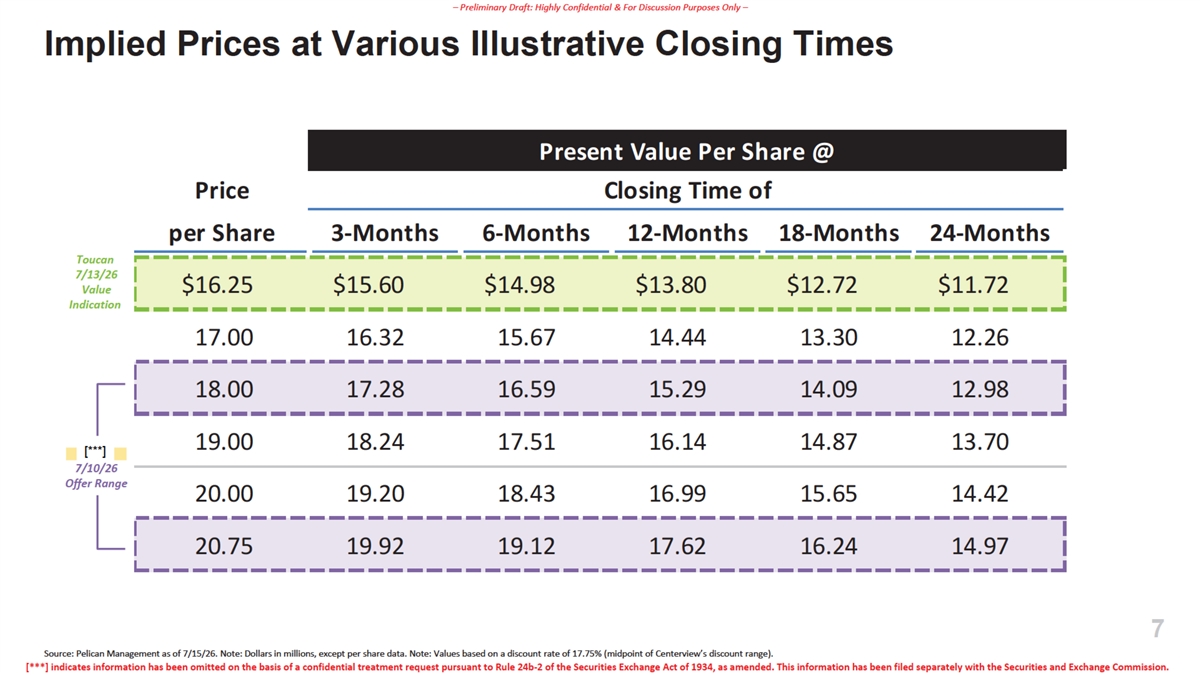
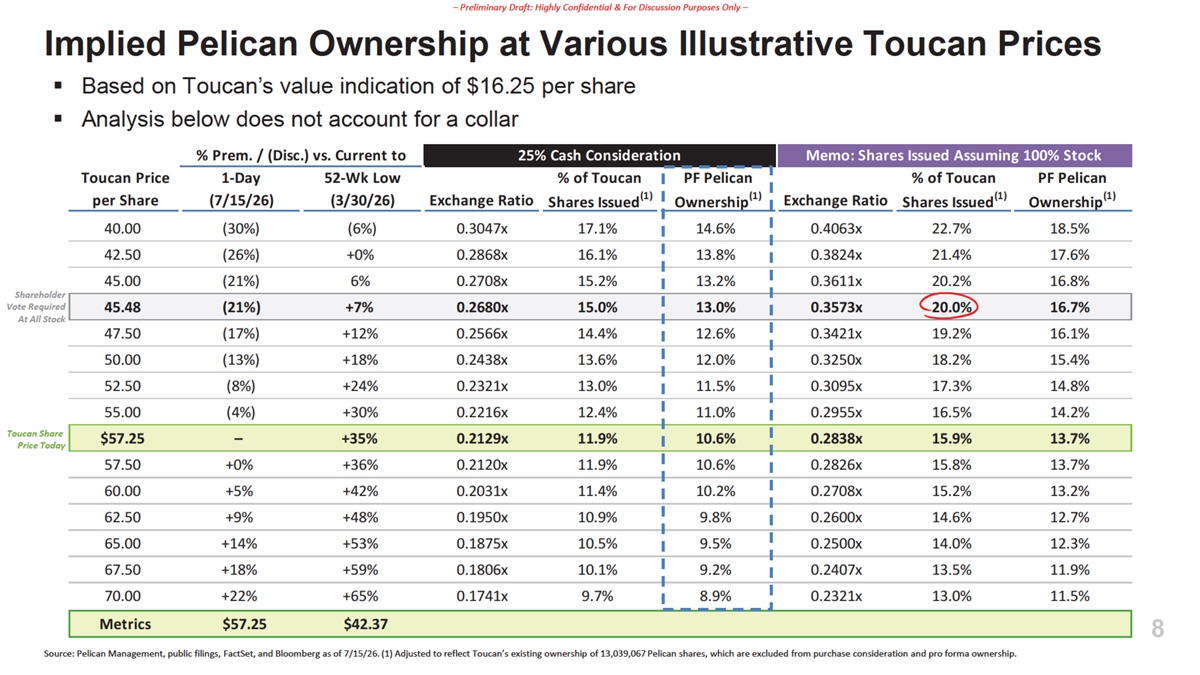
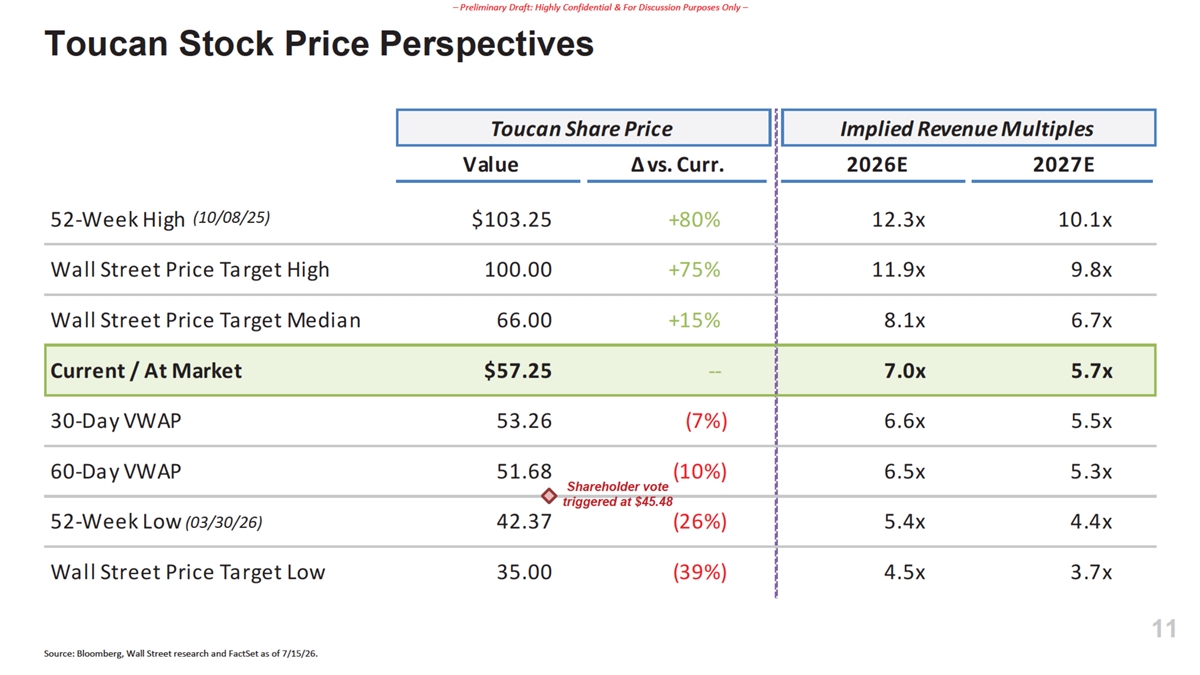
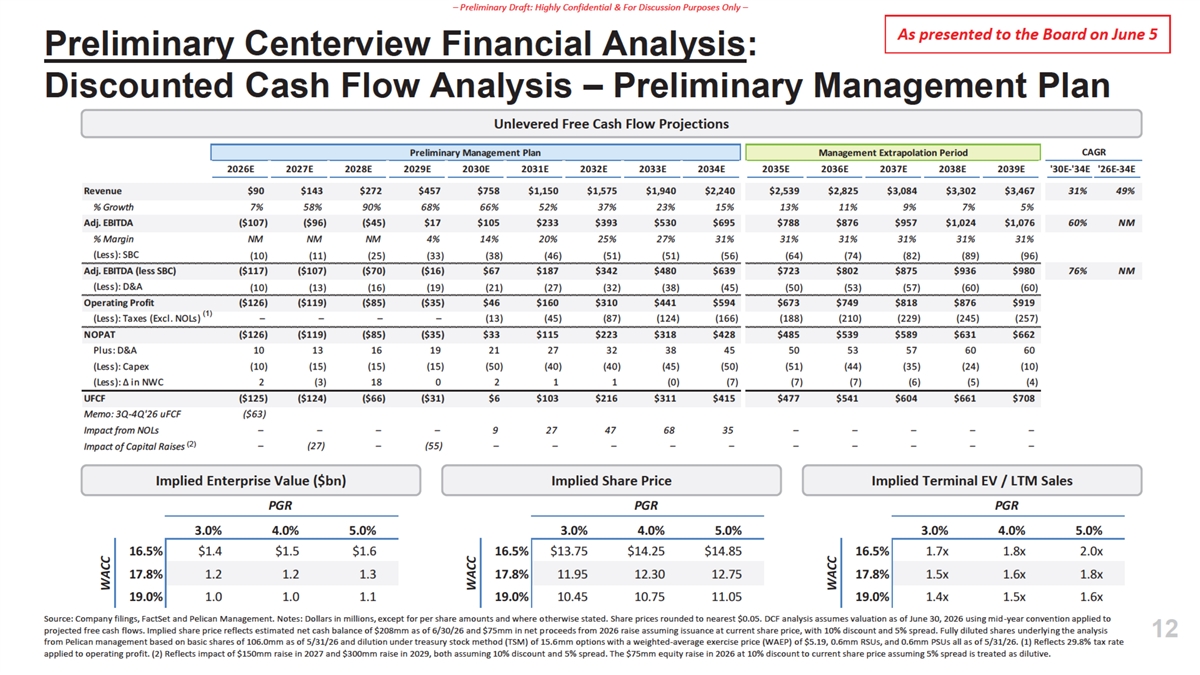
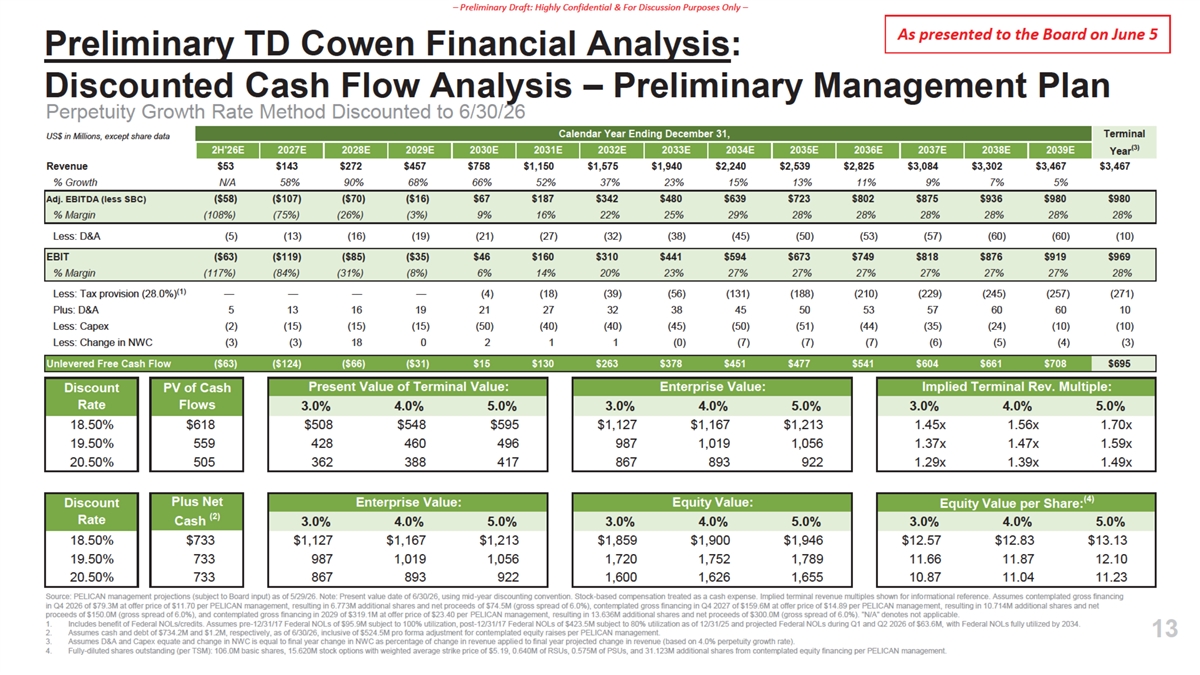
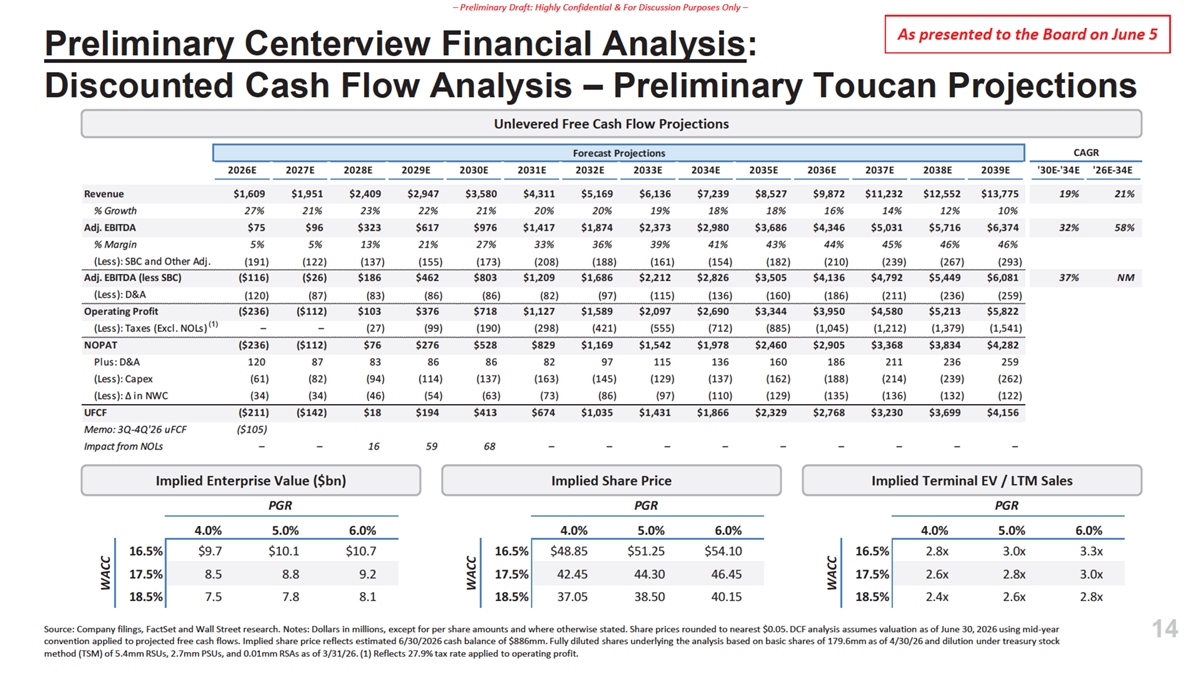
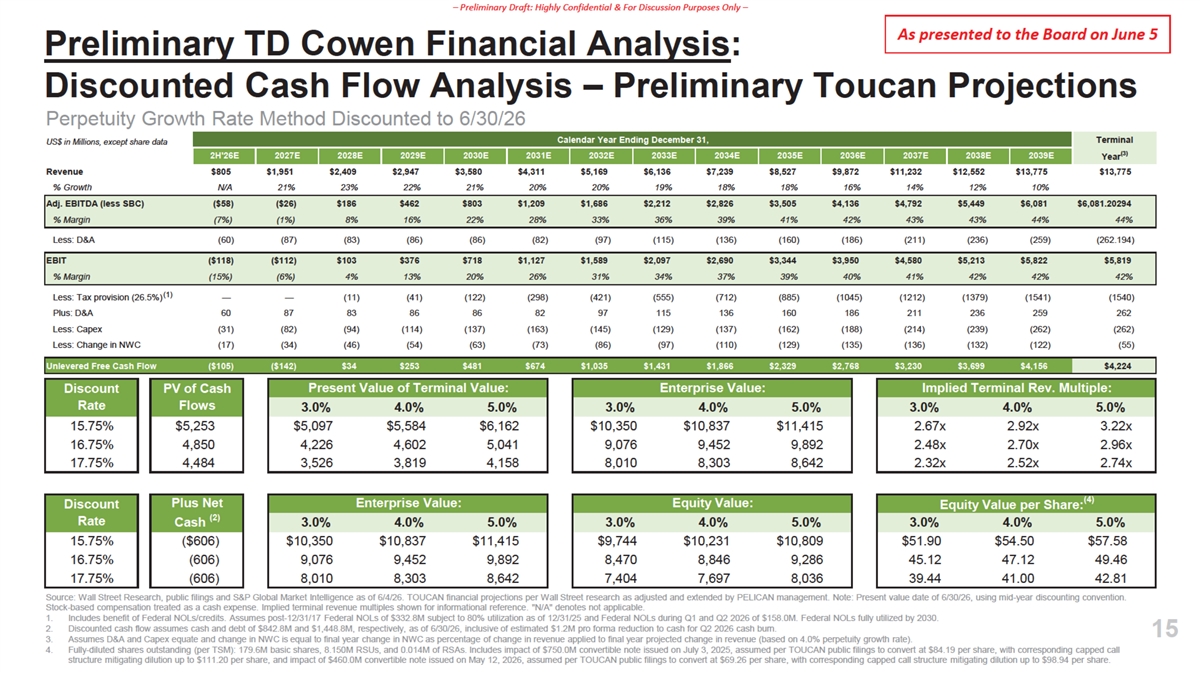
Exhibit (c)(15)
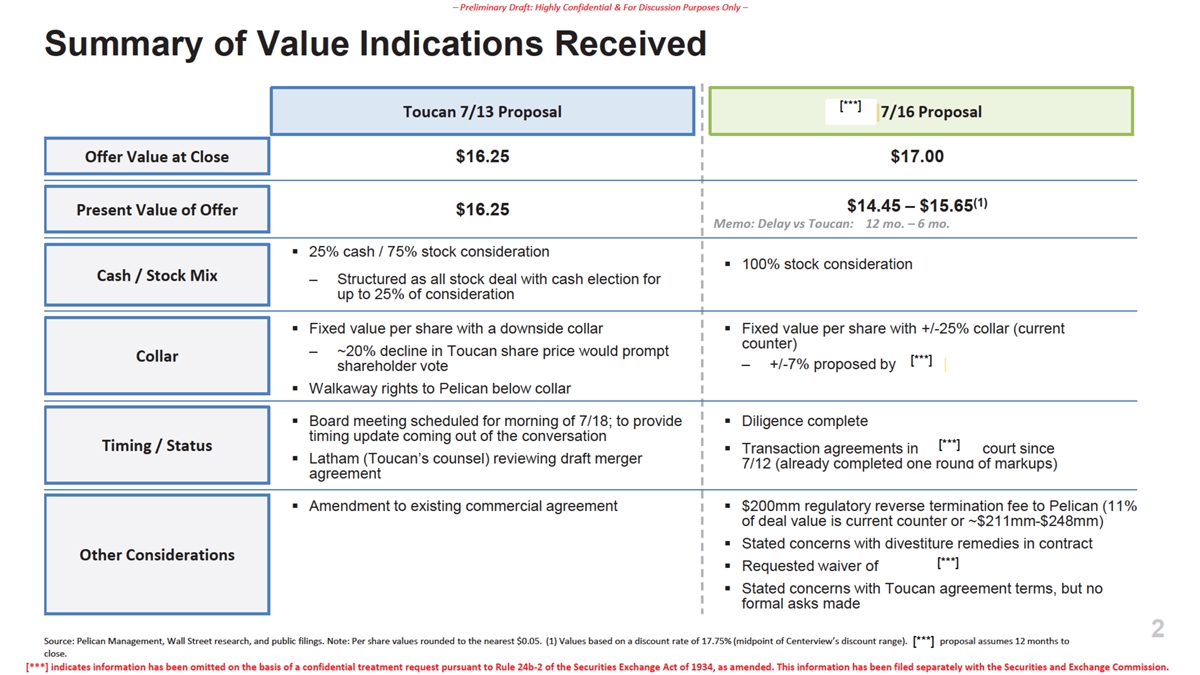
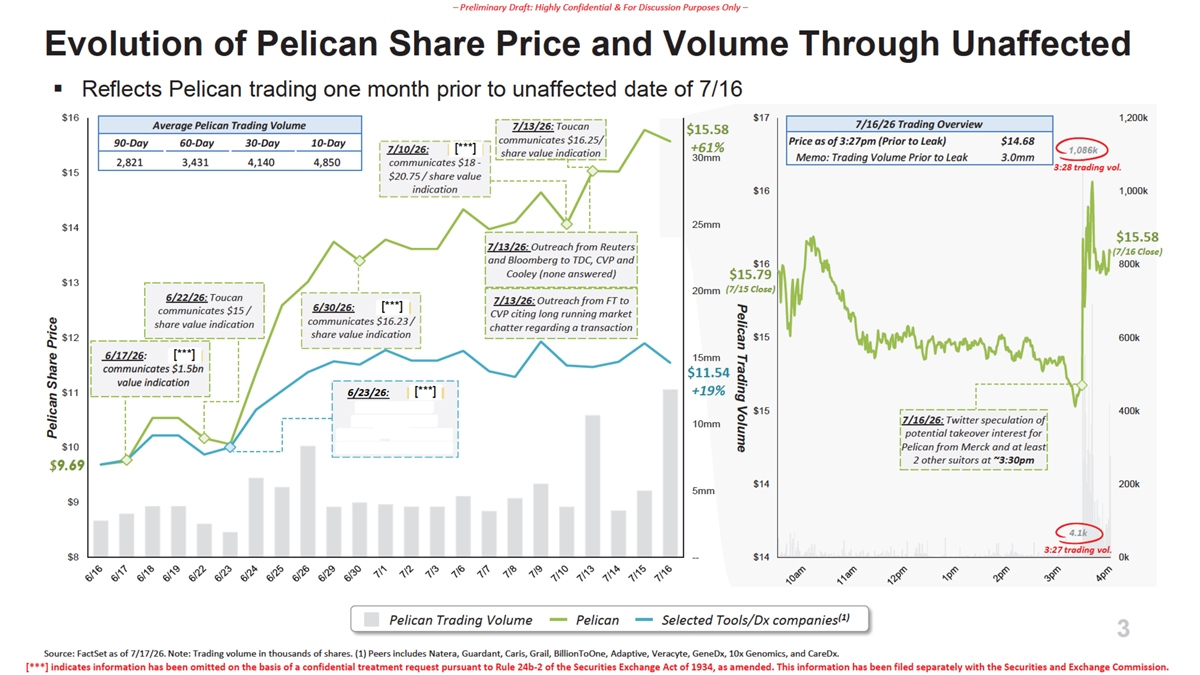
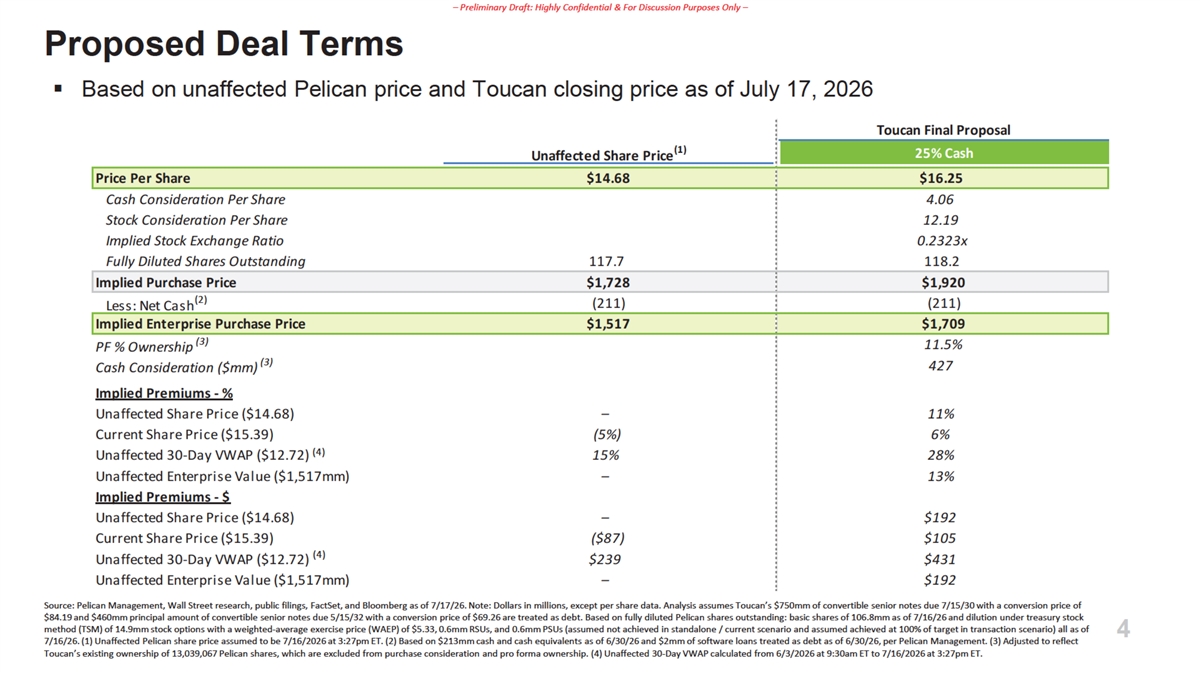
Exhibit (c)(16)
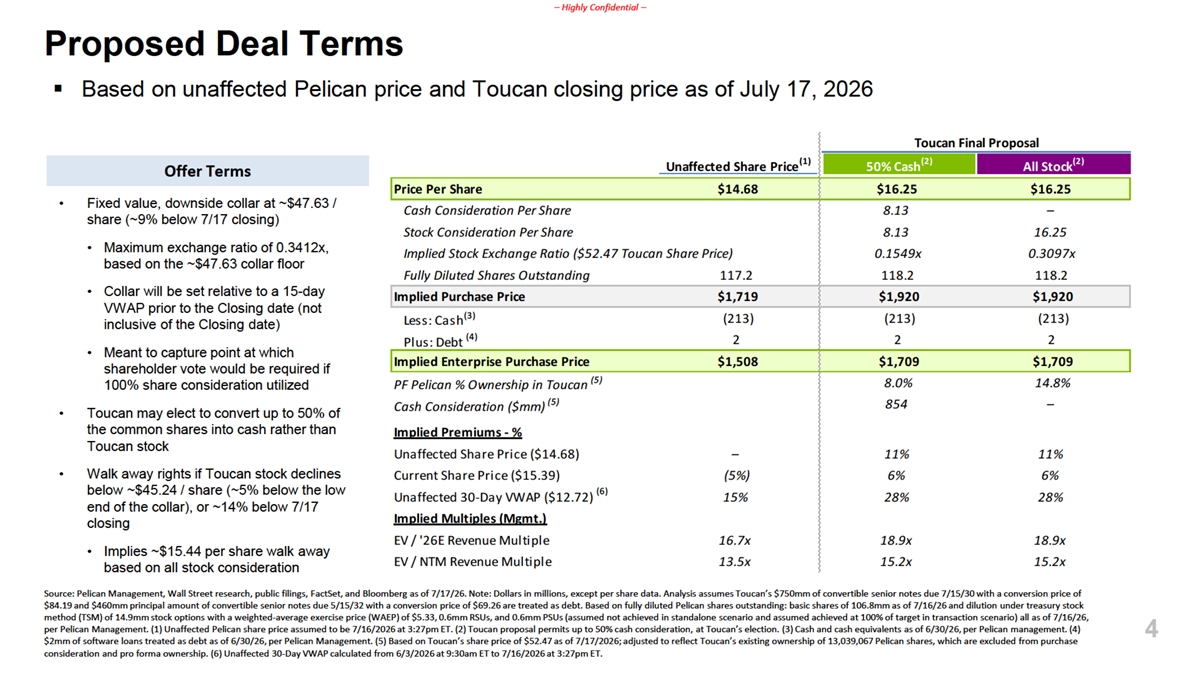
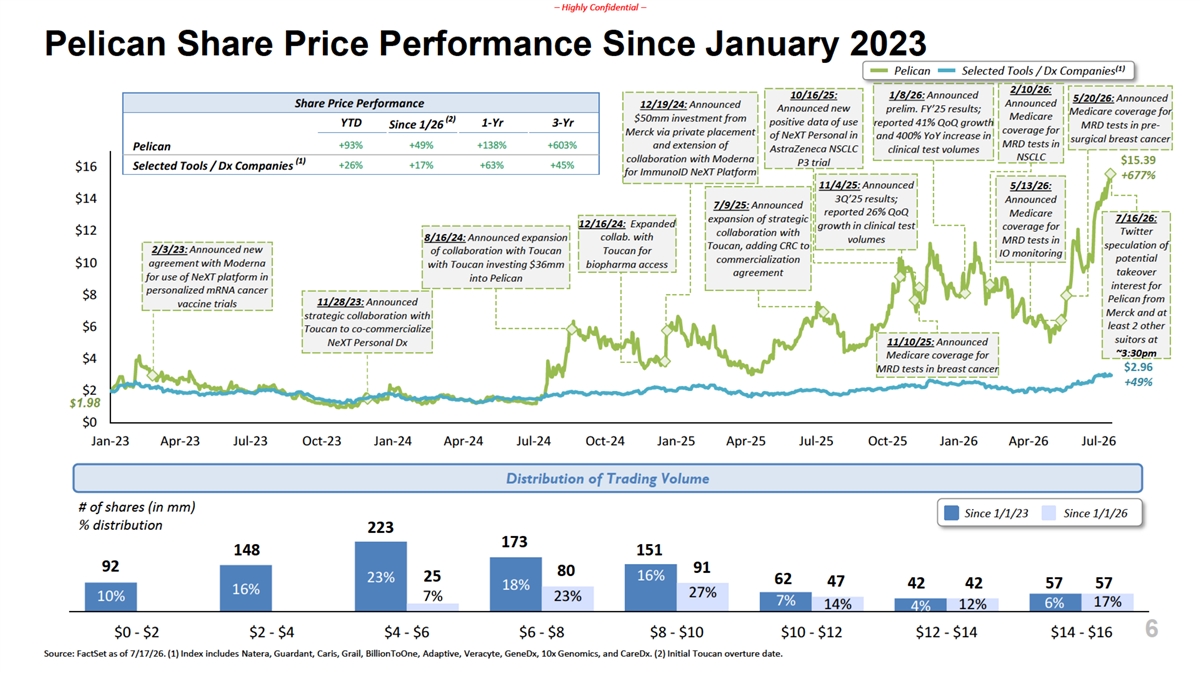
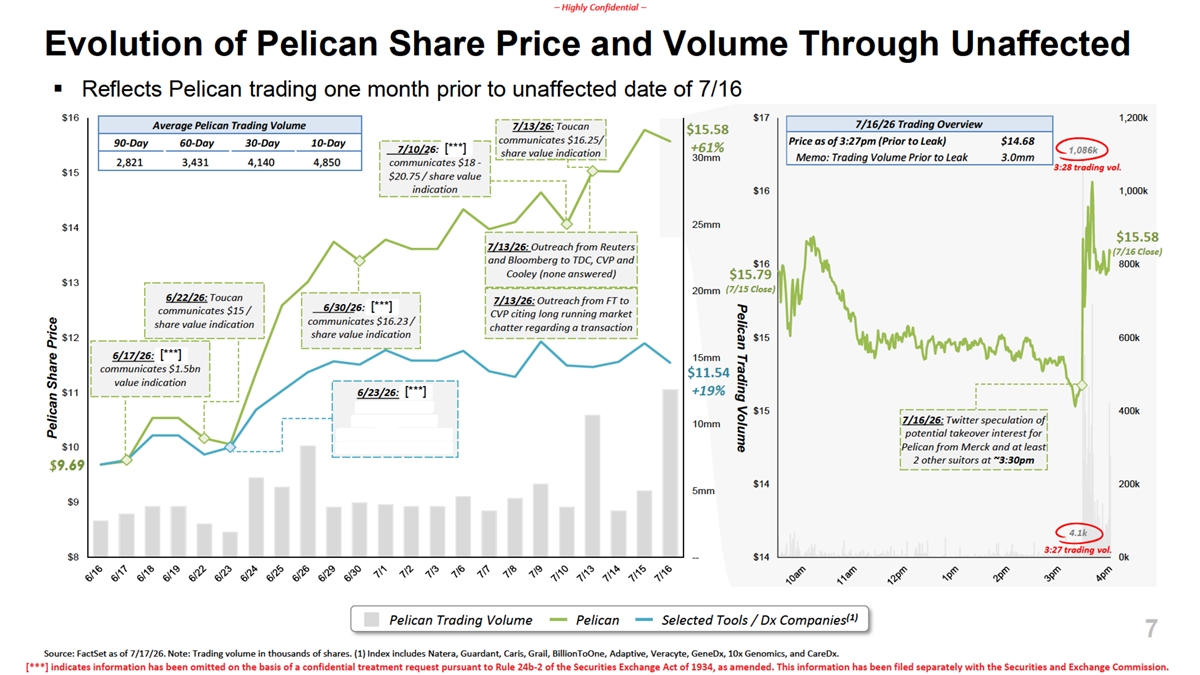
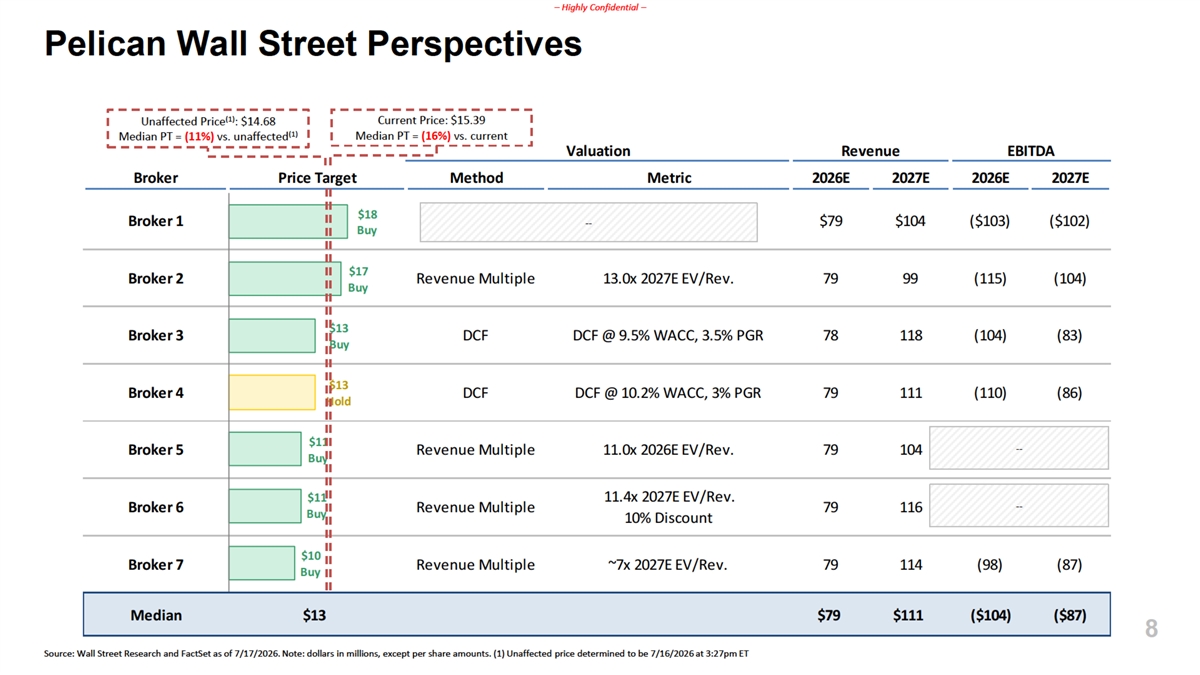
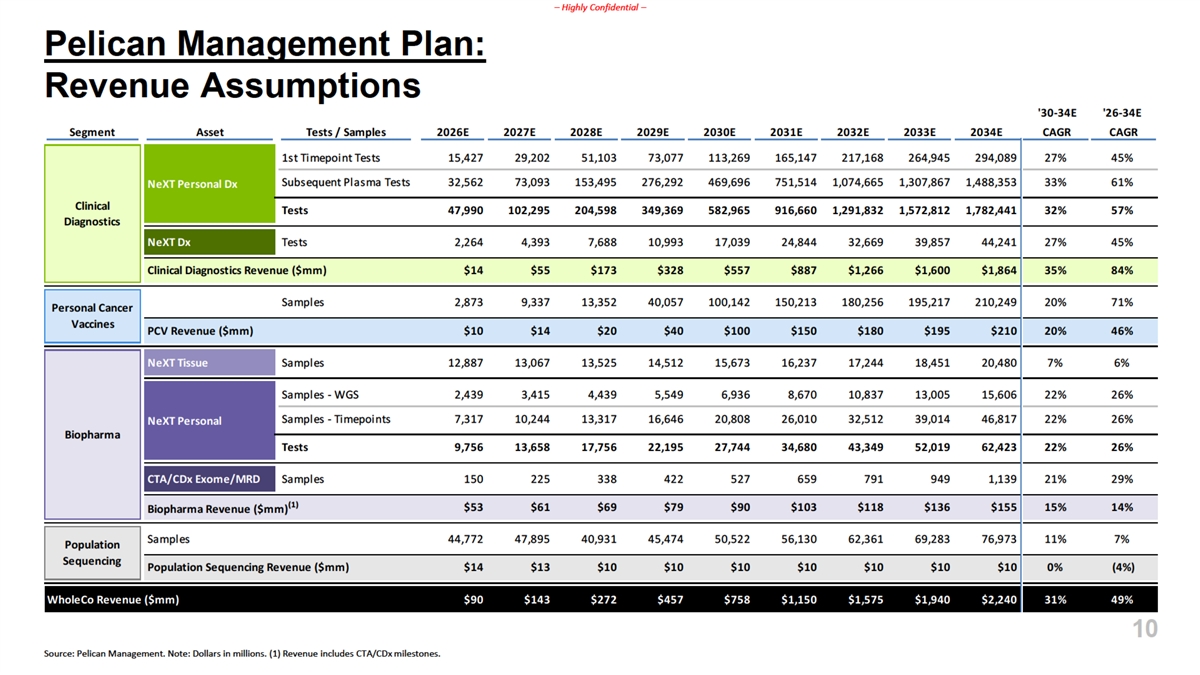
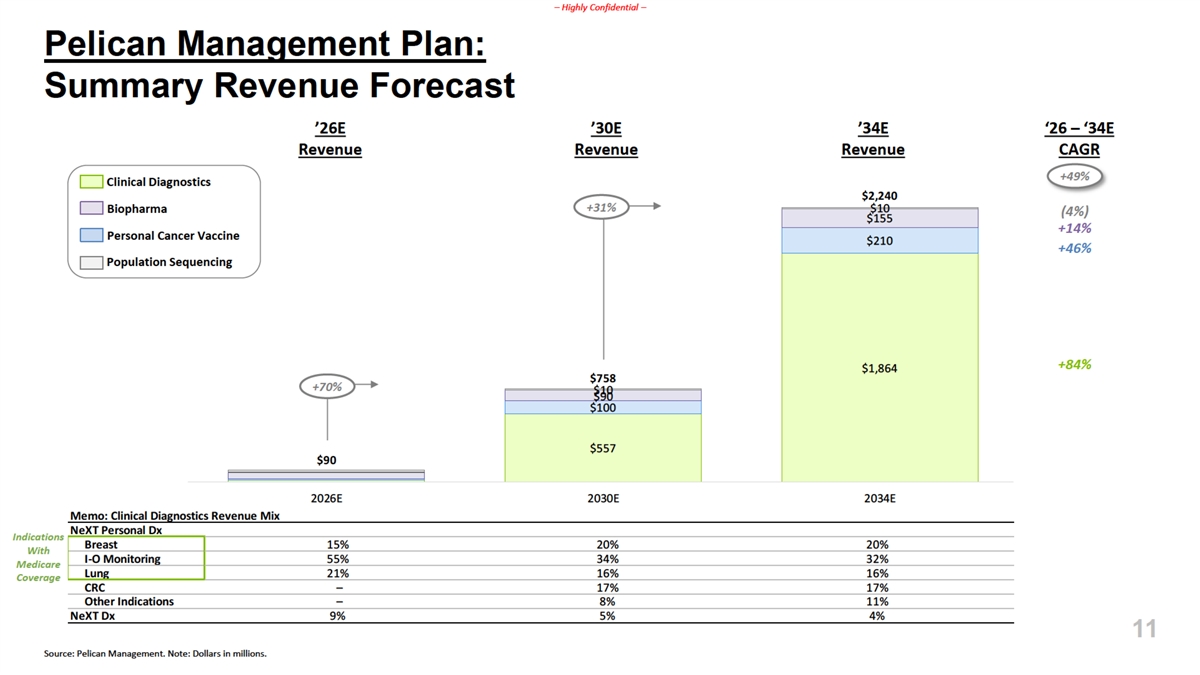
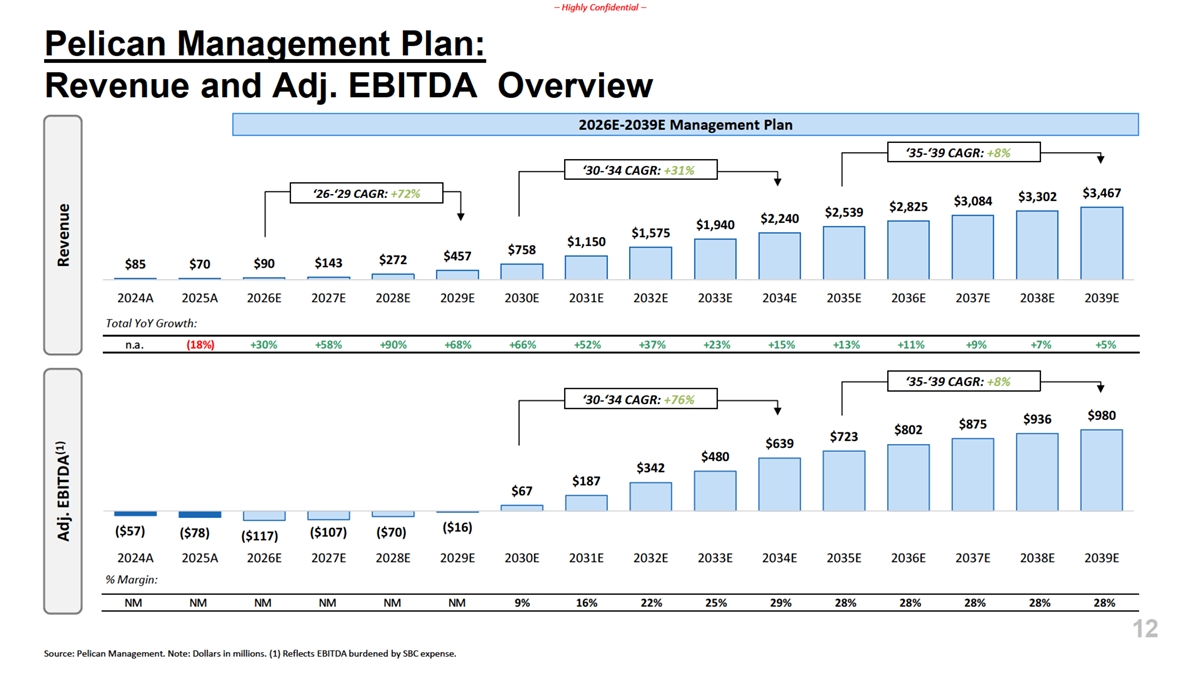
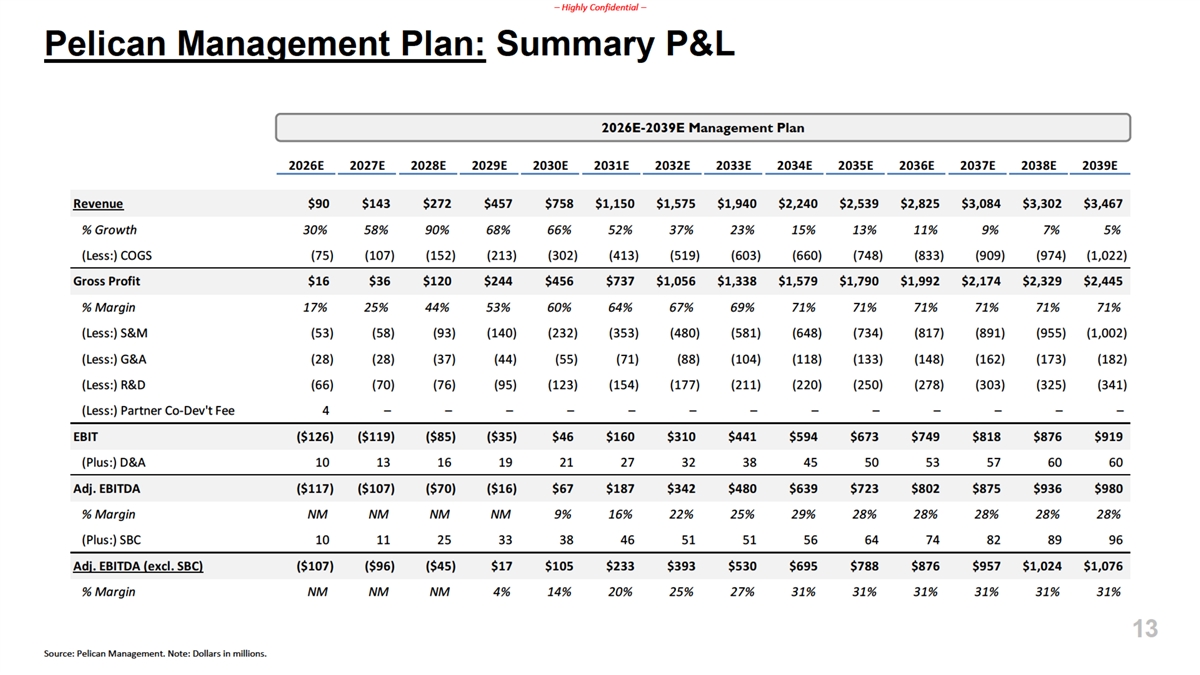
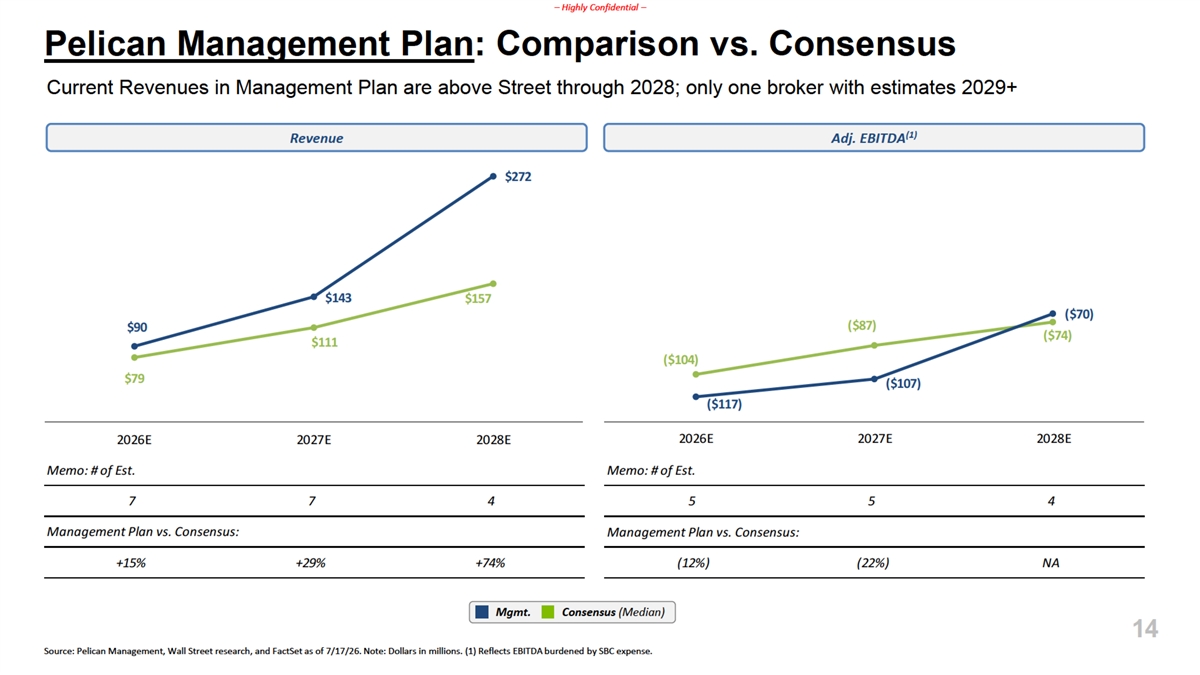
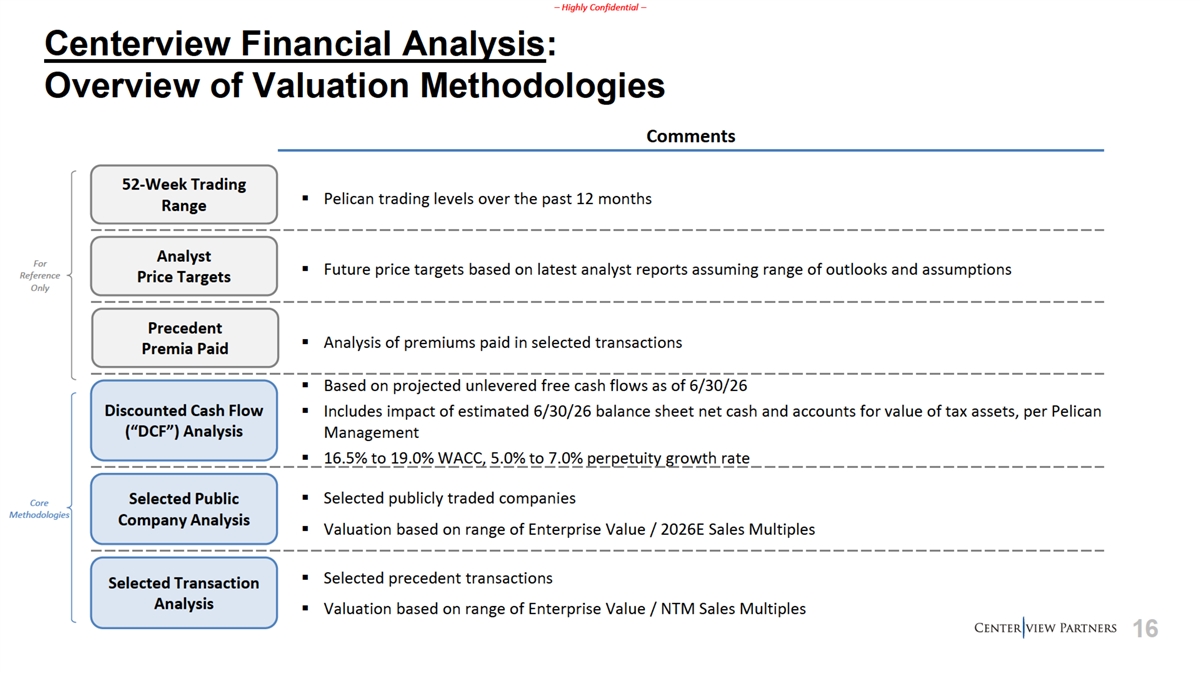
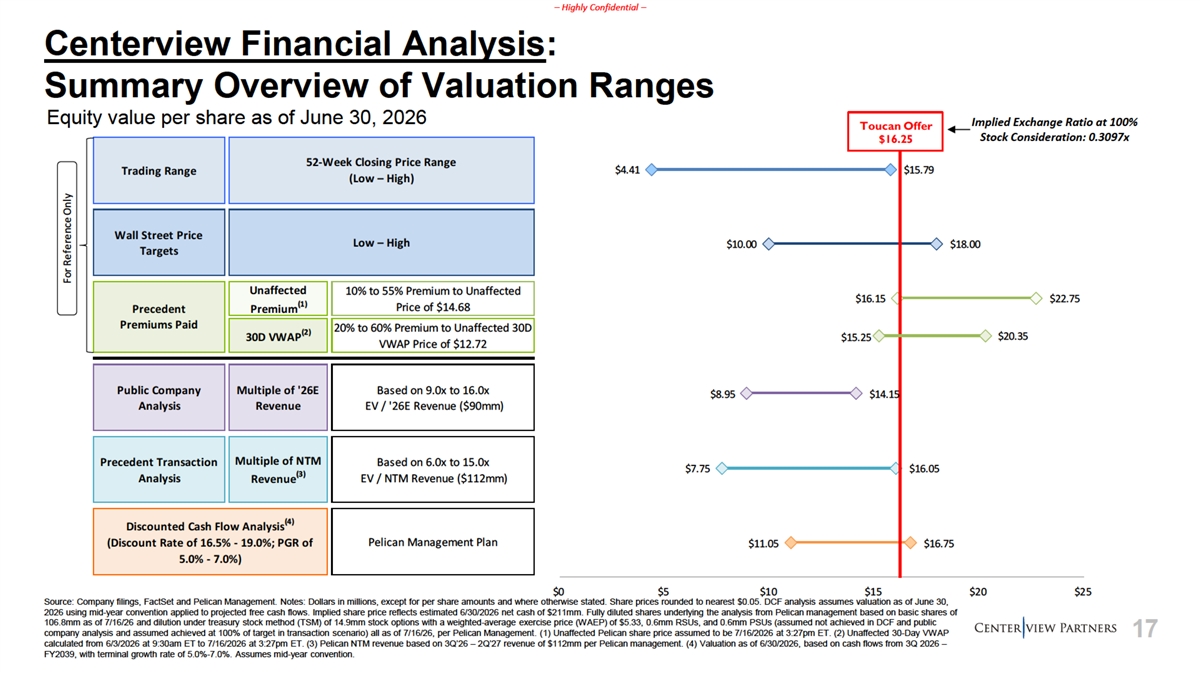
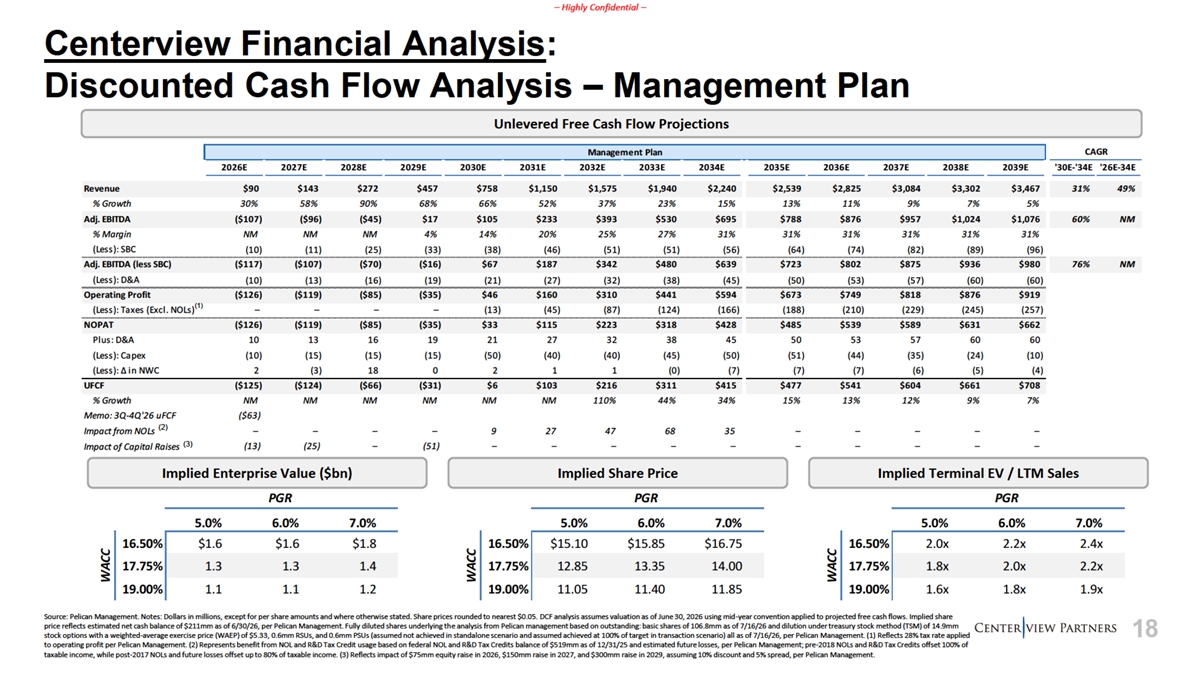
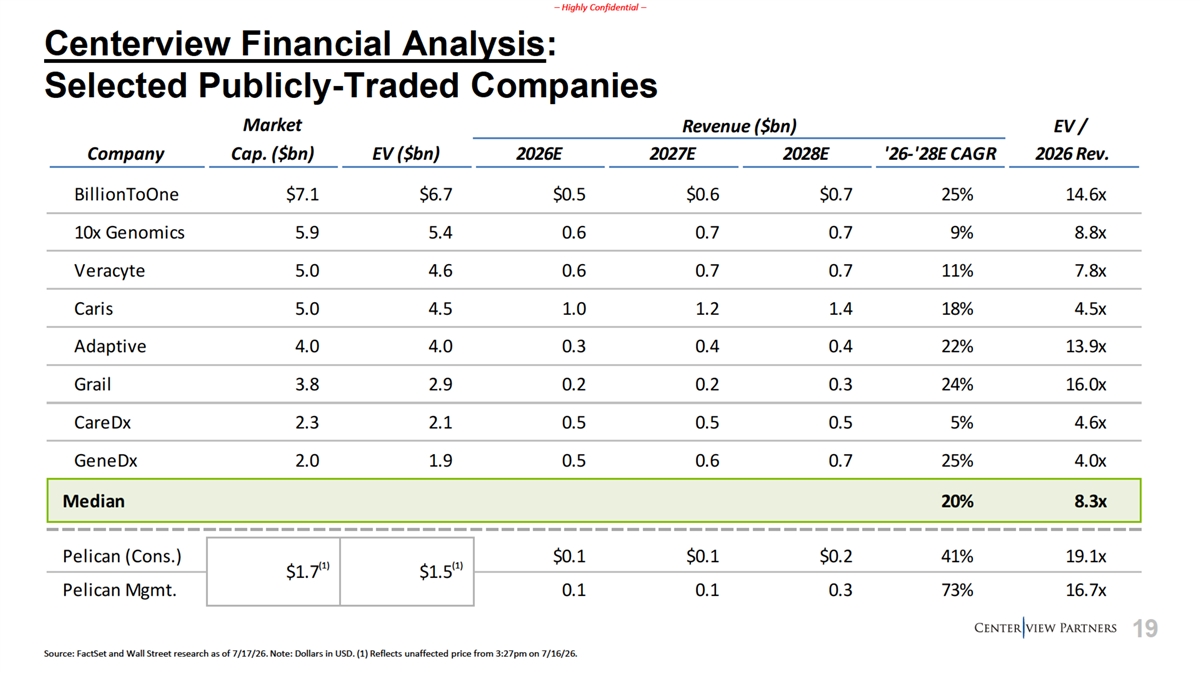
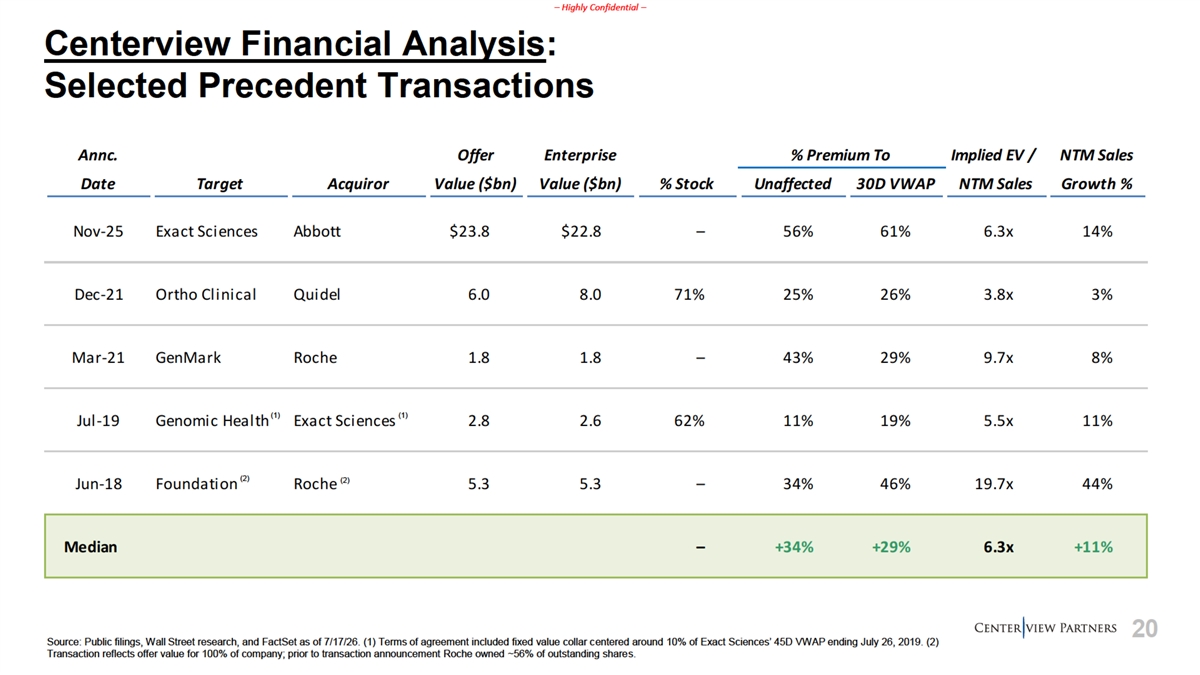
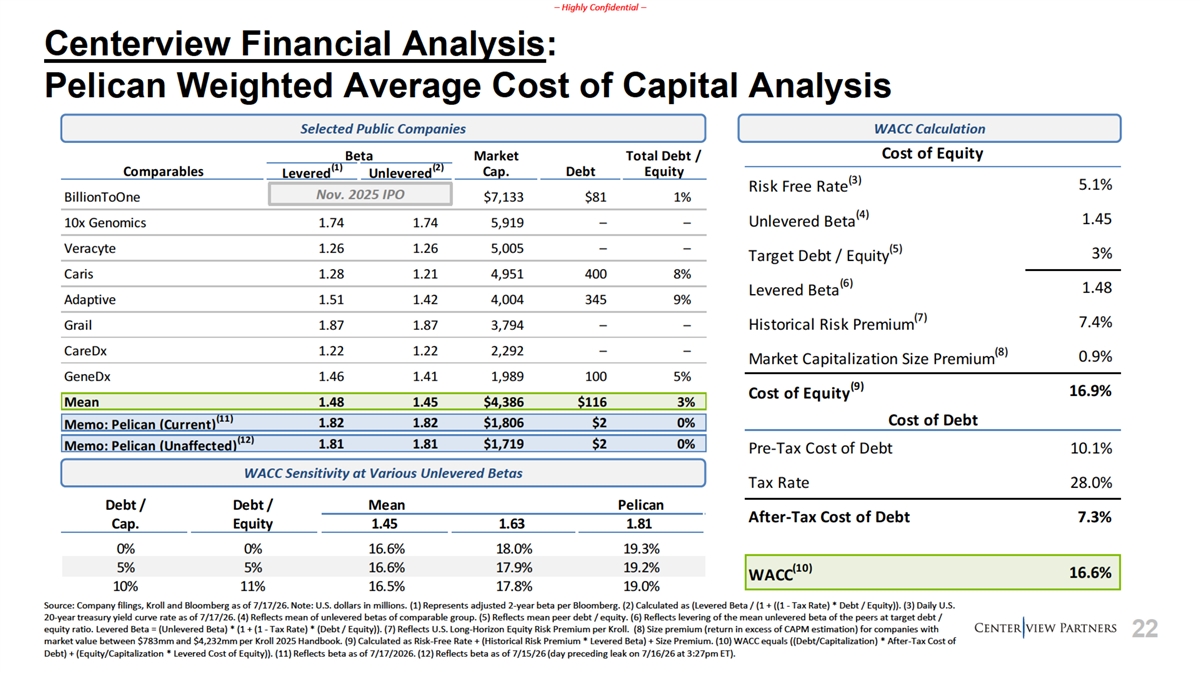
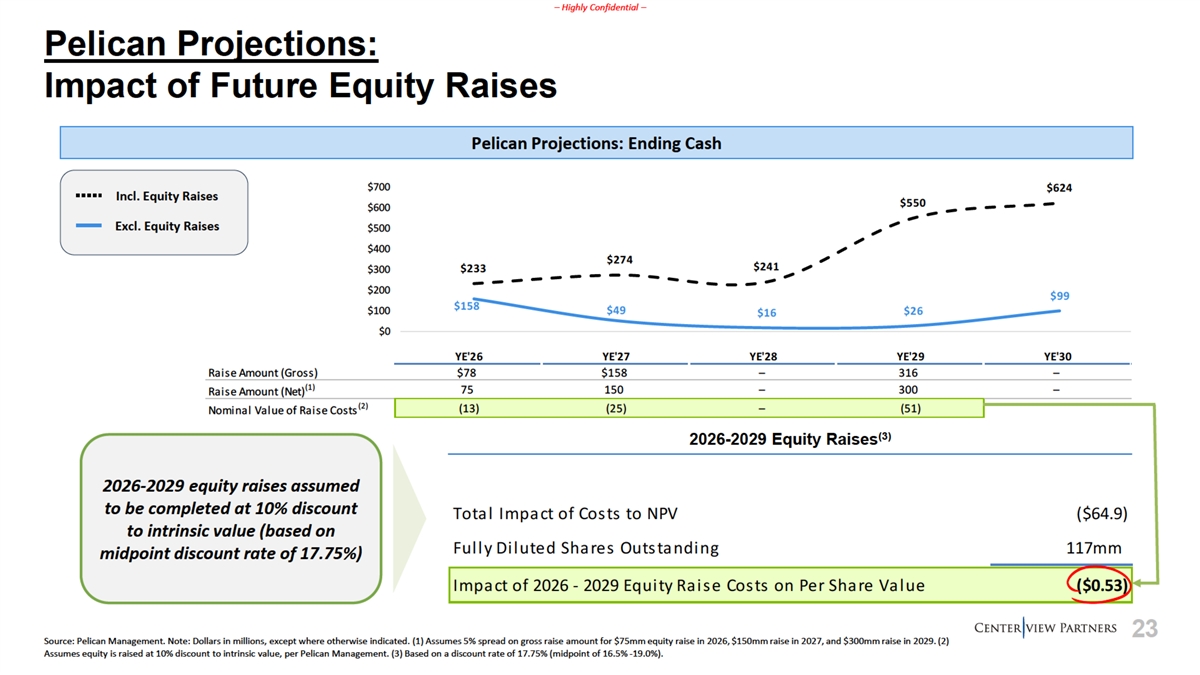
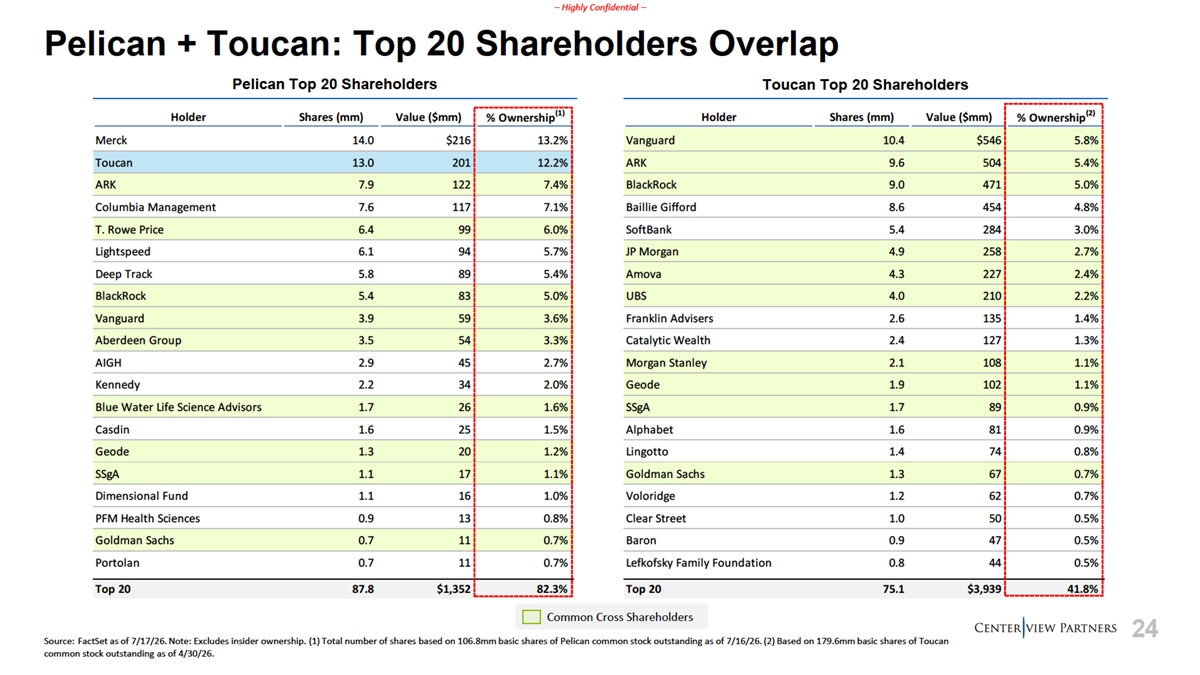
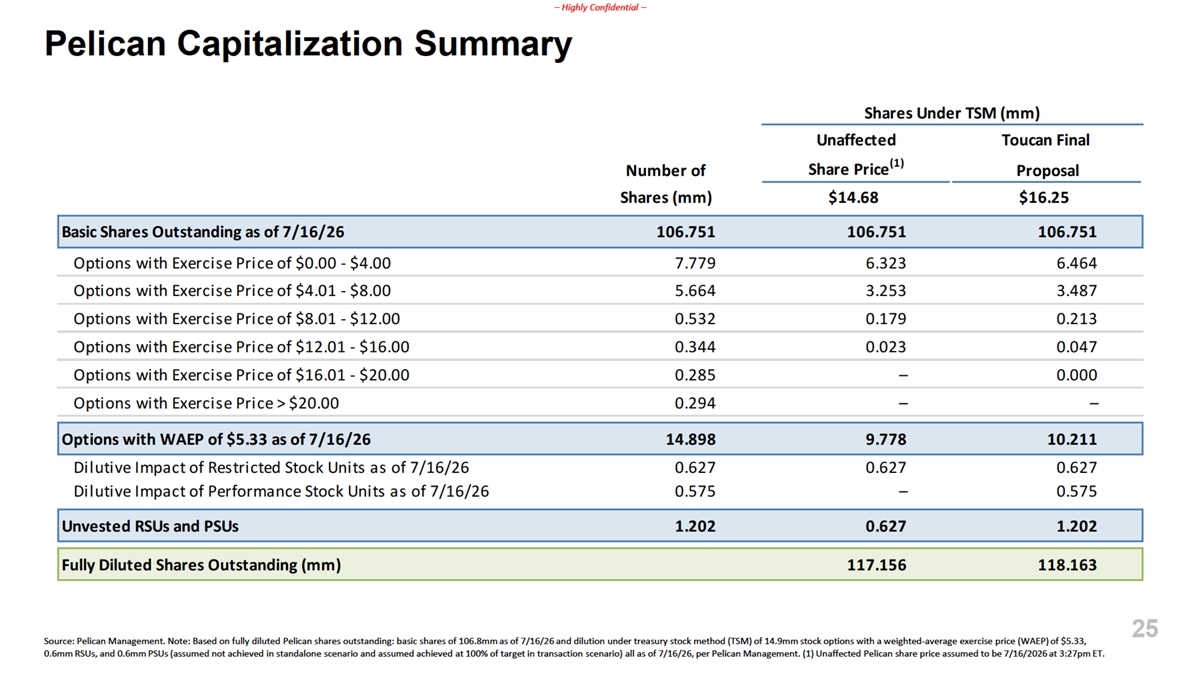
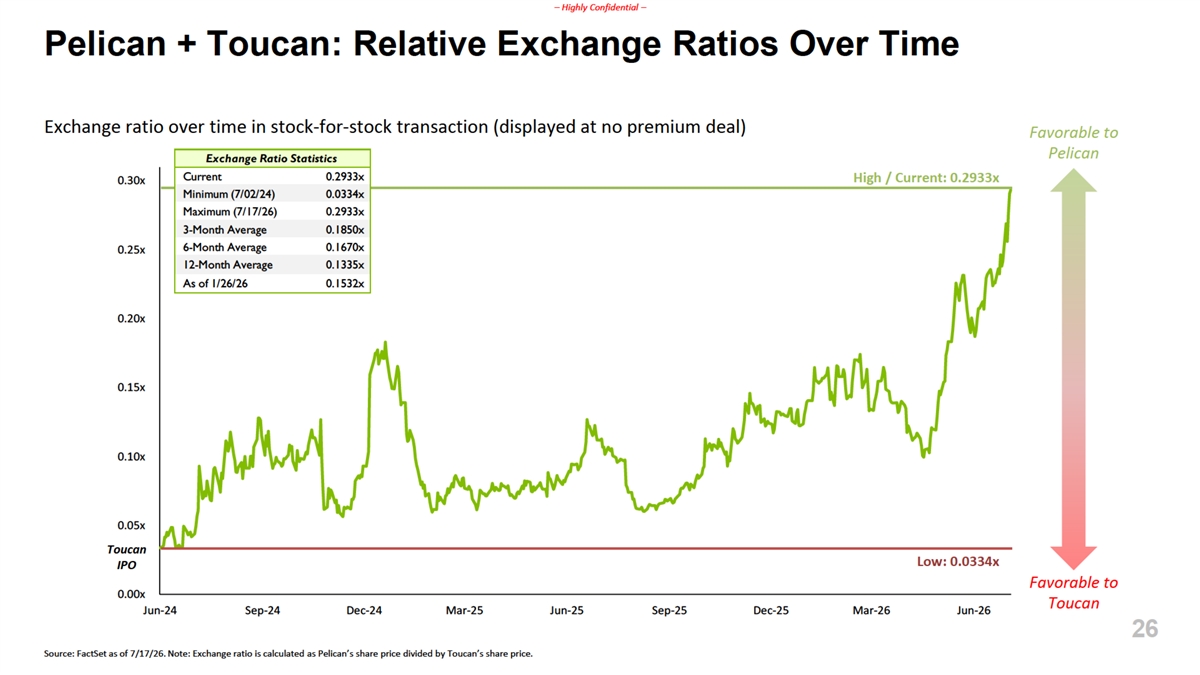
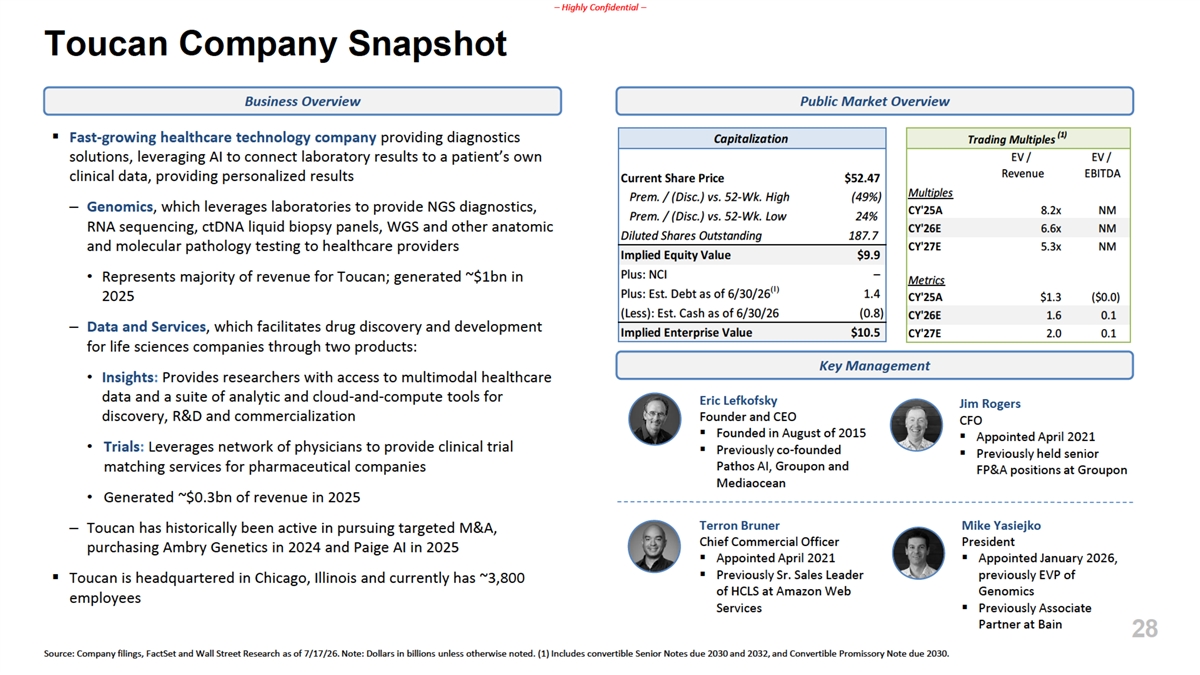
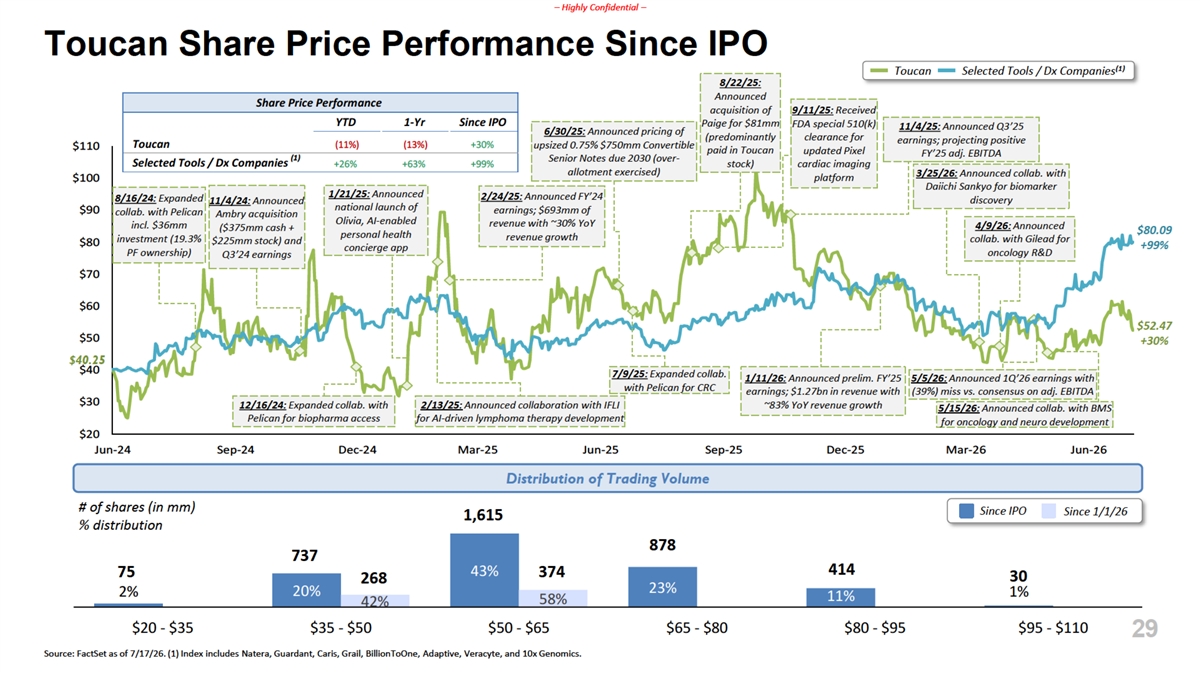
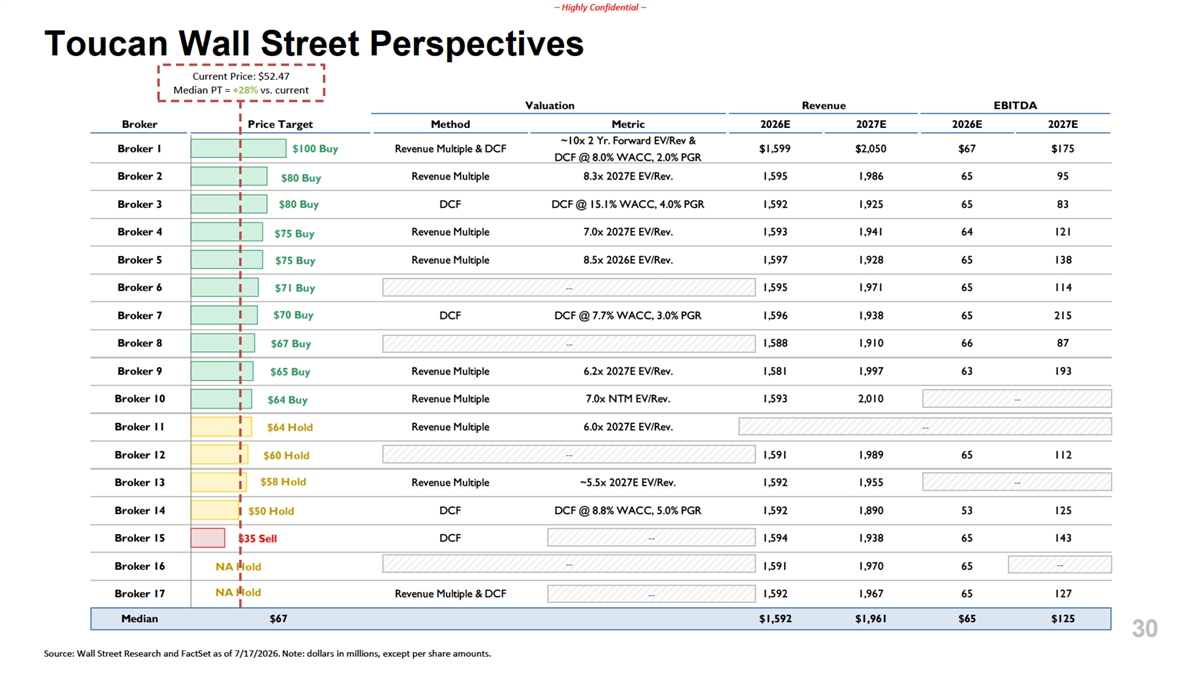
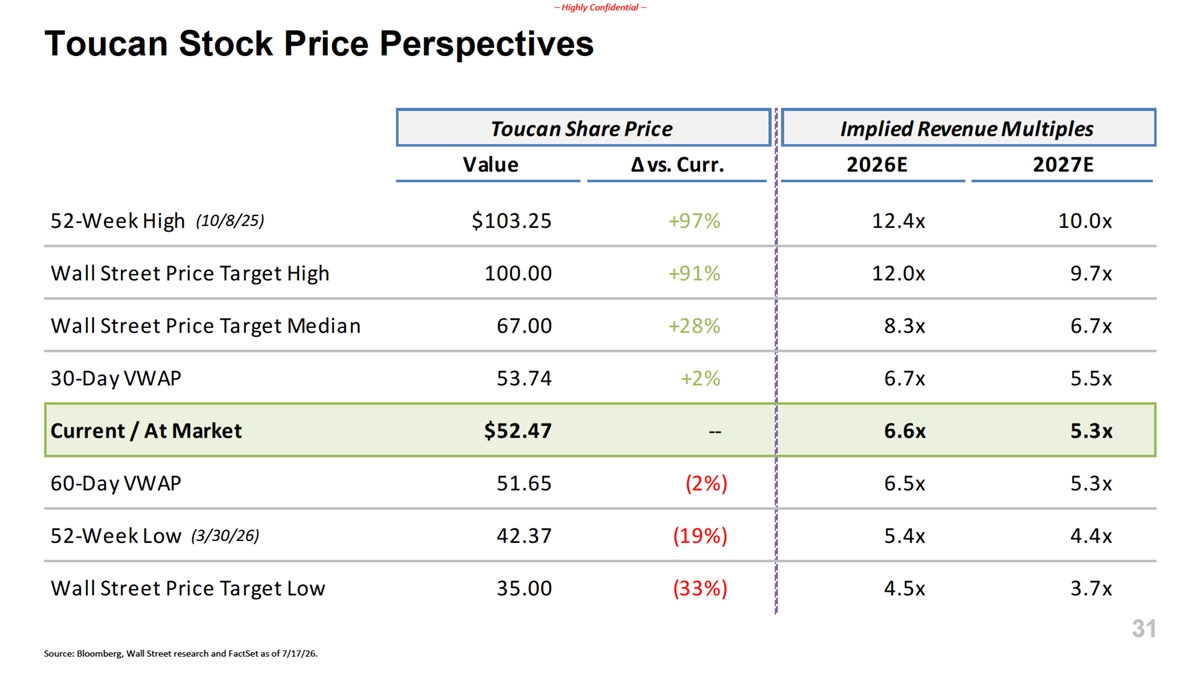
Exhibit (c)(17) Project AVIARY Presentation to the Board of Directors July 19, 2026
Disclaimer These materials were prepared solely for the information and benefit of Personalis, Inc. (“PELICAN”) in connection with a proposed transaction with Tempus AI, Inc. ( TOUCAN ) (the Transaction ). These materials are for discussion purposes only and are incomplete without reference to, and should be viewed in conjunction with, the oral presentation provided by TD Securities (USA) LLC ( TD Cowen ) to the Board and TD Cowen's written opinion letter, dated the date hereof, to be delivered to the Board. TD Cowen expresses no view as to PELICAN’s underlying business decision to effect the proposed Transaction, the relative merits of the proposed Transaction as compared to other business strategies or transactions that might be available to PELICAN or to any other aspect or implication of the proposed Transaction or any other agreement, arrangement or understanding entered into in connection with the proposed Transaction or otherwise. In preparing these materials, TD Cowen has, with PELICAN’s consent, relied upon information provided to TD Cowen by PELICAN management, or publicly available information or information otherwise reviewed by TD Cowen. TD Cowen has not independently verified any such information and has relied on it being complete and accurate in all material respects. To the extent such information includes estimates and forecasts of future financial performance prepared by PELICAN management or obtained from public sources, TD Cowen has utilized such estimates and forecasts at PELICAN’s direction and has assumed that such estimates and forecasts have been reasonably prepared on bases reflecting the best currently available estimates and judgments of PELICAN management or, with respect to estimates and forecasts obtained from public sources, represent reasonable estimates and forecasts. Please note that these materials are based on the business and operations of PELICAN as represented to TD Cowen as of the date hereof and do not purport to take into consideration any information or events arising subsequent to such date. TD Cowen makes no representation or warranty that there has been no material change in the information provided or reviewed by TD Cowen in connection herewith. TD Cowen has no obligation to update these materials. The information contained herein is highly confidential and has been prepared exclusively for the benefit and use of PELICAN in its consideration of the proposed Transaction, and may not be used for any other purpose or disclosed, copied, reproduced, disseminated, quoted or referred to at any time, in any manner or for any purpose without TD Cowen’s prior written consent, except as specifically set forth in the engagement letter between TD Cowen and PELICAN. These materials are not for the benefit of, and do not convey any rights or remedies to, any holder of securities of PELICAN or any other person. These materials are subject to various assumptions, qualifications and limitations set forth in TD Cowen's written opinion letter, dated the date hereof, to be delivered to the Board, and does not constitute a recommendation by TD Cowen to PELICAN or any other person on how to act with respect to any such proposed Transaction. TD Cowen does not address any legal, regulatory, tax or accounting effects of the proposed Transaction and nothing contained herein should be construed as legal, regulatory, tax or accounting advice. TD Securities” is a trademark of The Toronto-Dominion Bank (“TD”) and represents certain investment banking, capital markets and wholesale banking activities conducted through certain subsidiaries and branches of TD. “TD Cowen” is a division of TD Securities and represents a marketing name of certain businesses within TD Securities. © Copyright 2026 TD. All rights reserved. ® The TD logo and other TD trademarks are the property of TD or its subsidiaries. TD Securities Inc. is regulated by the Canadian Investment Regulatory Organization of Canada. TD Securities Inc. is a member of the Canadian Investor Protection Fund and a member of Canadian Marketplaces. TD Securities (USA) LLC, TD Prime Services LLC, TD Financial Products LLC, TD Arranged Services LLC and Westminster Research Associates LLC are registered with the U.S. Securities and Exchange Commission and are members of the Financial Industry Regulatory Authority (FINRA) and of the Securities Investor Protection Corporation (SIPC). 2
4 1 Overview of Proposal Table of 6 2 Public Market Perspectives Contents 11 3 PELICAN Financial Analysis 17 4 Appendix 3
1. Overview of Proposal
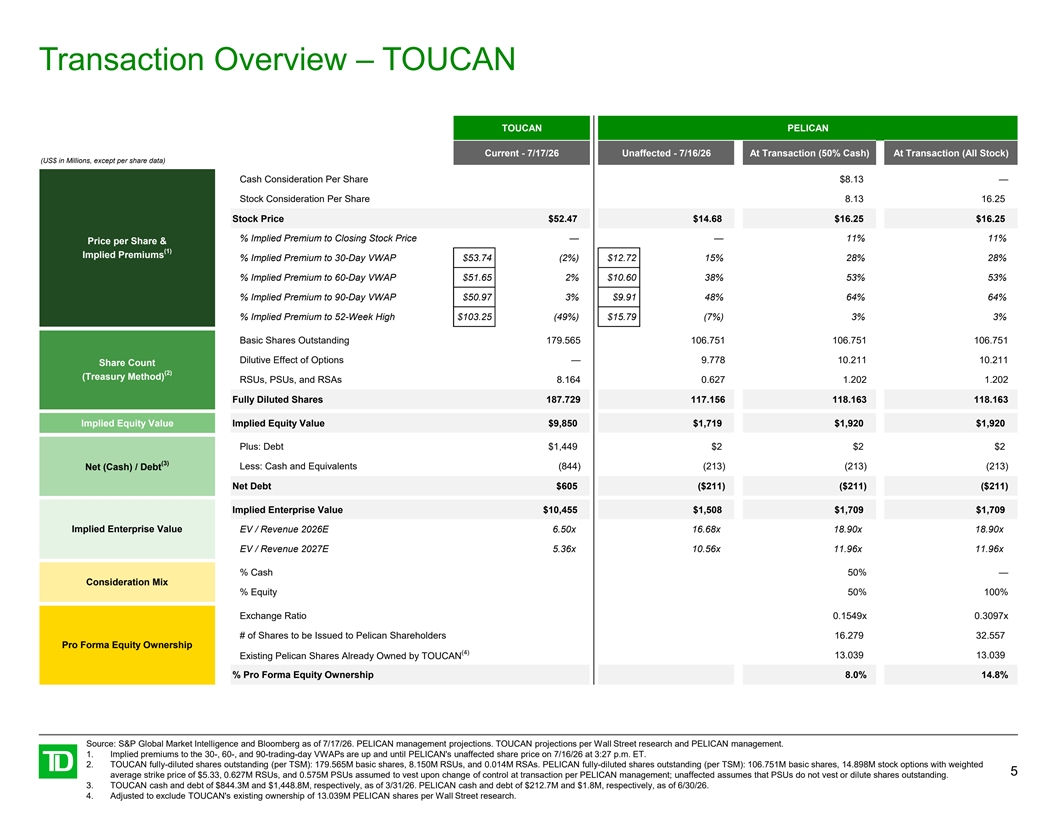
Transaction Overview – TOUCAN TOUCAN PELICAN Current - 7/17/26 Unaffected - 7/16/26 At Transaction (50% Cash) At Transaction (All Stock) (US$ in Millions, except per share data) Cash Consideration Per Share $8.13 — Stock Consideration Per Share 8.13 16.25 Stock Price $52.47 $14.68 $16.25 $16.25 % Implied Premium to Closing Stock Price — — 11% 11% Price per Share & (1) Implied Premiums % Implied Premium to 30-Day VWAP $53.74 (2%) $12.72 15% 28% 28% % Implied Premium to 60-Day VWAP $51.65 2% $10.60 38% 53% 53% % Implied Premium to 90-Day VWAP $50.97 3% $9.91 48% 64% 64% % Implied Premium to 52-Week High $103.25 (49%) $15.79 (7%) 3% 3% Basic Shares Outstanding 179.565 106.751 106.751 106.751 Dilutive Effect of Options — 9.778 10.211 10.211 Share Count (2) (Treasury Method) RSUs, PSUs, and RSAs 8.164 0.627 1.202 1.202 Fully Diluted Shares 187.729 117.156 118.163 118.163 Implied Equity Value Implied Equity Value $9,850 $1,719 $1,920 $1,920 Plus: Debt $1,449 $2 $2 $2 (3) Less: Cash and Equivalents (844) (213) (213) (213) Net (Cash) / Debt Net Debt $605 ($211) ($211) ($211) Implied Enterprise Value $10,455 $1,508 $1,709 $1,709 Implied Enterprise Value EV / Revenue 2026E 6.50x 16.68x 18.90x 18.90x EV / Revenue 2027E 5.36x 10.56x 11.96x 11.96x % Cash 50% — Consideration Mix % Equity 50% 100% Exchange Ratio 0.1549x 0.3097x # of Shares to be Issued to Pelican Shareholders 16.279 32.557 Pro Forma Equity Ownership (4) 13.039 13.039 Existing Pelican Shares Already Owned by TOUCAN % Pro Forma Equity Ownership 8.0% 14.8% Source: S&P Global Market Intelligence and Bloomberg as of 7/17/26. PELICAN management projections. TOUCAN projections per Wall Street research and PELICAN management. 1. Implied premiums to the 30-, 60-, and 90-trading-day VWAPs are up and until PELICAN's unaffected share price on 7/16/26 at 3:27 p.m. ET. 2. TOUCAN fully-diluted shares outstanding (per TSM): 179.565M basic shares, 8.150M RSUs, and 0.014M RSAs. PELICAN fully-diluted shares outstanding (per TSM): 106.751M basic shares, 14.898M stock options with weighted 5 average strike price of $5.33, 0.627M RSUs, and 0.575M PSUs assumed to vest upon change of control at transaction per PELICAN management; unaffected assumes that PSUs do not vest or dilute shares outstanding. 3. TOUCAN cash and debt of $844.3M and $1,448.8M, respectively, as of 3/31/26. PELICAN cash and debt of $212.7M and $1.8M, respectively, as of 6/30/26. 4. Adjusted to exclude TOUCAN's existing ownership of 13.039M PELICAN shares per Wall Street research.
2. Public Market Perspectives
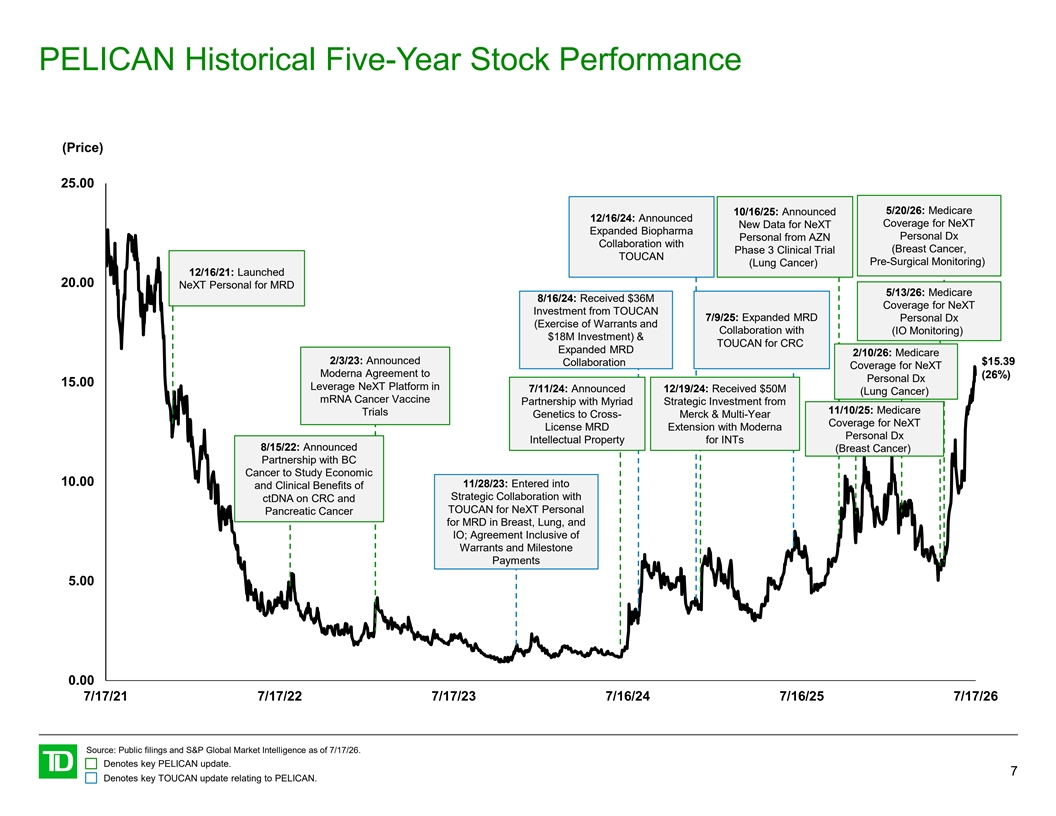
PELICAN Historical Five-Year Stock Performance (Price) 25.00 5/20/26: Medicare 10/16/25: Announced 12/16/24: Announced Coverage for NeXT New Data for NeXT Expanded Biopharma Personal Dx Personal from AZN Collaboration with Phase 3 Clinical Trial (Breast Cancer, TOUCAN Pre-Surgical Monitoring) (Lung Cancer) 12/16/21: Launched 20.00 NeXT Personal for MRD 5/13/26: Medicare 8/16/24: Received $36M Coverage for NeXT Investment from TOUCAN 7/9/25: Expanded MRD Personal Dx (Exercise of Warrants and Collaboration with (IO Monitoring) $18M Investment) & TOUCAN for CRC Expanded MRD 2/10/26: Medicare 2/3/23: Announced $15.39 Collaboration Coverage for NeXT Moderna Agreement to (26%) Personal Dx 15.00 Leverage NeXT Platform in 7/11/24: Announced 12/19/24: Received $50M (Lung Cancer) mRNA Cancer Vaccine Partnership with Myriad Strategic Investment from 11/10/25: Medicare Trials Genetics to Cross- Merck & Multi-Year Coverage for NeXT License MRD Extension with Moderna Personal Dx Intellectual Property for INTs 8/15/22: Announced (Breast Cancer) Partnership with BC Cancer to Study Economic 10.00 11/28/23: Entered into and Clinical Benefits of Strategic Collaboration with ctDNA on CRC and TOUCAN for NeXT Personal Pancreatic Cancer for MRD in Breast, Lung, and IO; Agreement Inclusive of Warrants and Milestone Payments 5.00 0.00 7/17/21 7/17/22 7/17/23 7/16/24 7/16/25 7/17/26 Source: Public filings and S&P Global Market Intelligence as of 7/17/26. Denotes key PELICAN update. 7 Denotes key TOUCAN update relating to PELICAN.
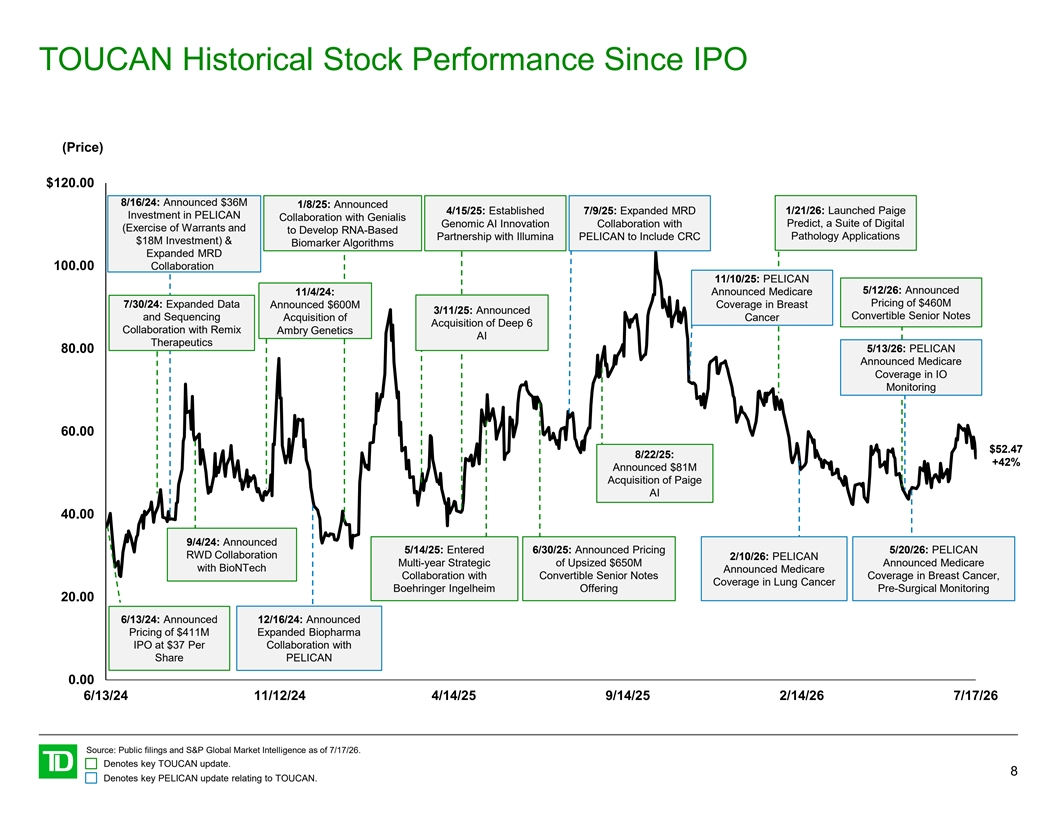
TOUCAN Historical Stock Performance Since IPO (Price) $120.00 8/16/24: Announced $36M 1/8/25: Announced 4/15/25: Established 7/9/25: Expanded MRD 1/21/26: Launched Paige Investment in PELICAN Collaboration with Genialis Predict, a Suite of Digital Genomic AI Innovation Collaboration with (Exercise of Warrants and to Develop RNA-Based Partnership with Illumina PELICAN to Include CRC Pathology Applications $18M Investment) & Biomarker Algorithms Expanded MRD 100.00 Collaboration 11/10/25: PELICAN 5/12/26: Announced 11/4/24: Announced Medicare Pricing of $460M 7/30/24: Expanded Data Announced $600M Coverage in Breast 3/11/25: Announced Convertible Senior Notes and Sequencing Acquisition of Cancer Acquisition of Deep 6 Collaboration with Remix Ambry Genetics AI Therapeutics 5/13/26: PELICAN 80.00 Announced Medicare Coverage in IO Monitoring 60.00 $52.47 8/22/25: +42% Announced $81M Acquisition of Paige AI 40.00 9/4/24: Announced 5/14/25: Entered 6/30/25: Announced Pricing 5/20/26: PELICAN RWD Collaboration 2/10/26: PELICAN Multi-year Strategic of Upsized $650M Announced Medicare with BioNTech Announced Medicare Collaboration with Convertible Senior Notes Coverage in Breast Cancer, Coverage in Lung Cancer Boehringer Ingelheim Offering Pre-Surgical Monitoring 20.00 6/13/24: Announced 12/16/24: Announced Pricing of $411M Expanded Biopharma IPO at $37 Per Collaboration with Share PELICAN 0.00 6/13/24 11/12/24 4/14/25 9/14/25 2/14/26 7/17/26 Source: Public filings and S&P Global Market Intelligence as of 7/17/26. Denotes key TOUCAN update. 8 Denotes key PELICAN update relating to TOUCAN.
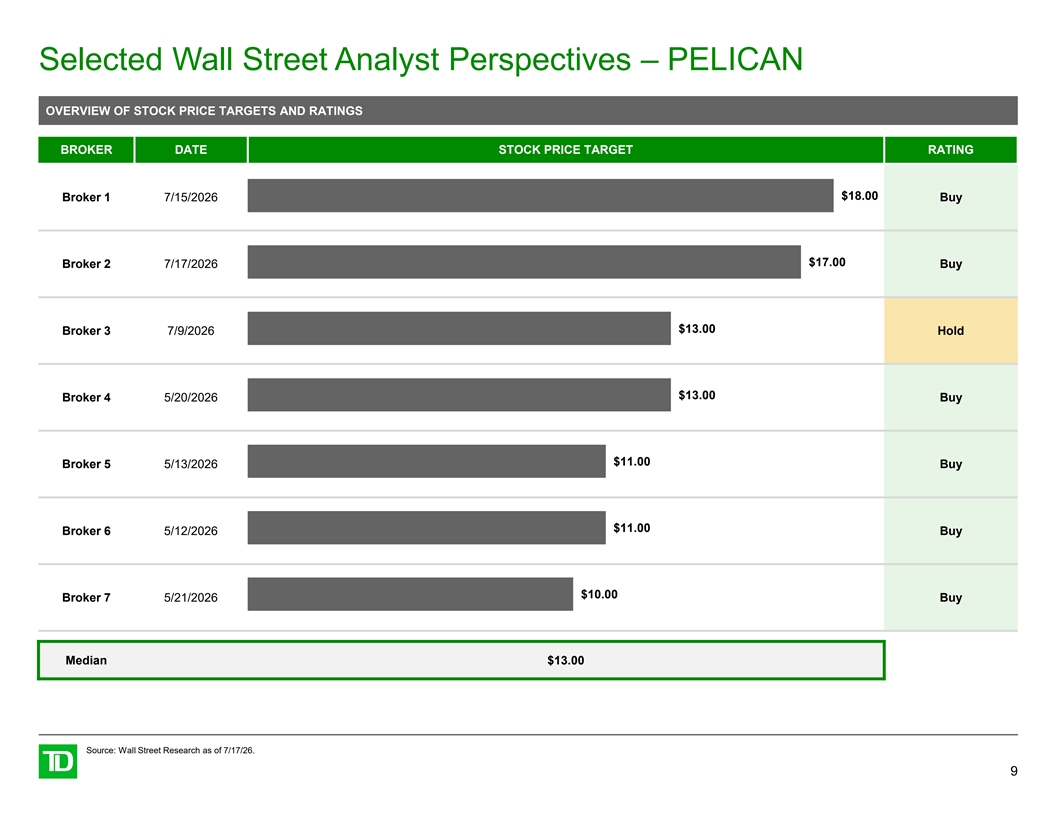
Selected Wall Street Analyst Perspectives – PELICAN OVERVIEW OF STOCK PRICE TARGETS AND RATINGS BROKER DATE STOCK PRICE TARGET RATING $18.00 Broker 1 7/15/2026 Buy $17.00 Broker 2 7/17/2026 Buy $13.00 Broker 3 7/9/2026 Hold $13.00 Broker 4 5/20/2026 Buy $11.00 Broker 5 5/13/2026 Buy $11.00 Broker 6 5/12/2026 Buy $10.00 Broker 7 5/21/2026 Buy Median $13.00 Source: Wall Street Research as of 7/17/26. 9
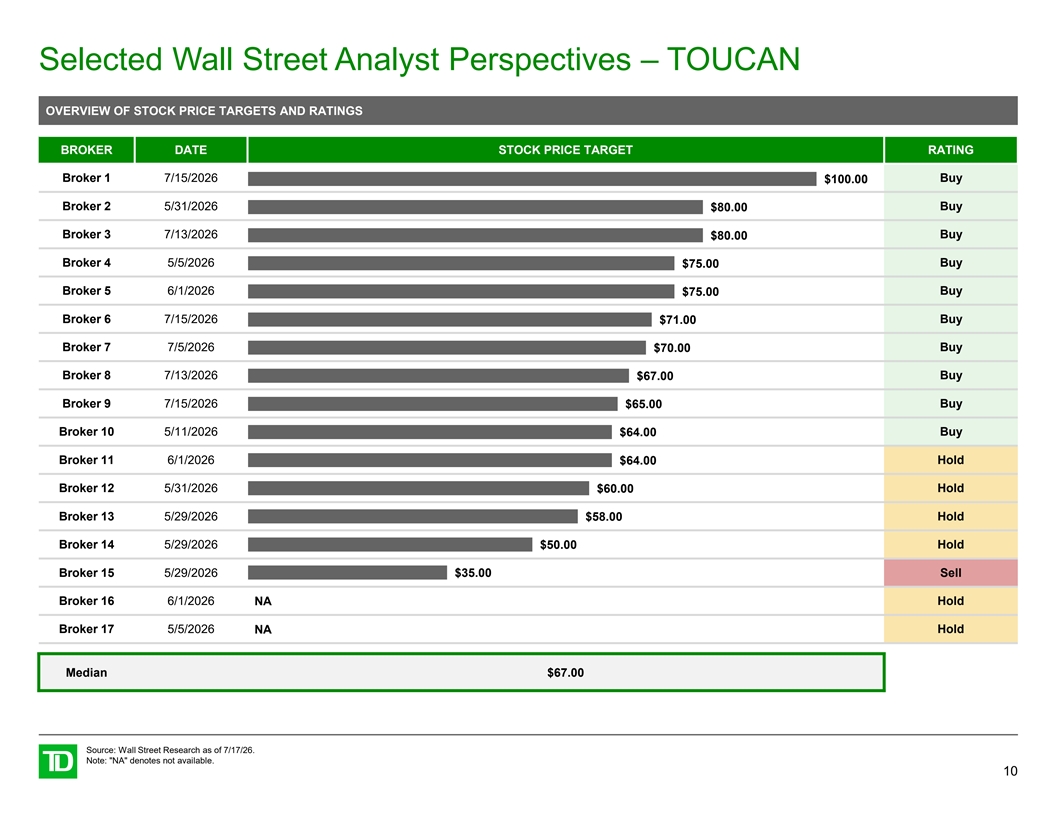
Selected Wall Street Analyst Perspectives – TOUCAN OVERVIEW OF STOCK PRICE TARGETS AND RATINGS BROKER DATE STOCK PRICE TARGET RATING Broker 1 7/15/2026 Buy $100.00 Broker 2 5/31/2026 Buy $80.00 Broker 3 7/13/2026 Buy $80.00 Broker 4 5/5/2026 Buy $75.00 Broker 5 6/1/2026 Buy $75.00 Broker 6 7/15/2026 Buy $71.00 Broker 7 7/5/2026 $70.00 Buy Broker 8 7/13/2026 $67.00 Buy Broker 9 7/15/2026 $65.00 Buy Broker 10 5/11/2026 $64.00 Buy Broker 11 6/1/2026 Hold $64.00 Broker 12 5/31/2026 Hold $60.00 Broker 13 5/29/2026 $58.00 Hold Broker 14 5/29/2026 $50.00 Hold Broker 15 5/29/2026 $35.00 Sell Broker 16 6/1/2026 NA Hold Broker 17 5/5/2026 NA Hold Median $67.00 Source: Wall Street Research as of 7/17/26. Note: NA denotes not available. 10
3. PELICAN Financial Analysis
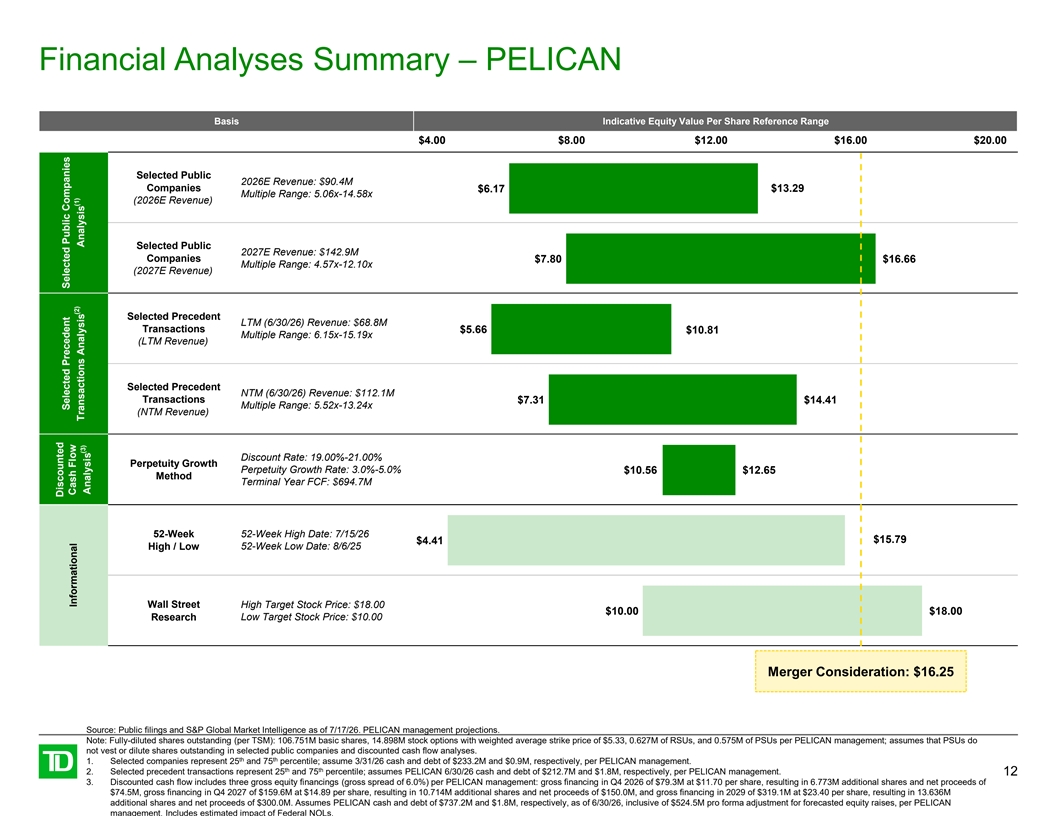
Financial Analyses Summary – PELICAN Basis Indicative Equity Value Per Share Reference Range $4.00 $8.00 $12.00 $16.00 $20.00 Selected Public 2026E Revenue: $90.4M Companies $6.17 $13.29 Multiple Range: 5.06x-14.58x (2026E Revenue) Selected Public 2027E Revenue: $142.9M Companies $7.80 $16.66 Multiple Range: 4.57x-12.10x (2027E Revenue) Selected Precedent LTM (6/30/26) Revenue: $68.8M Transactions $5.66 $10.81 Multiple Range: 6.15x-15.19x (LTM Revenue) Selected Precedent NTM (6/30/26) Revenue: $112.1M Transactions $7.31 $14.41 Multiple Range: 5.52x-13.24x (NTM Revenue) Discount Rate: 19.00%-21.00% Perpetuity Growth Perpetuity Growth Rate: 3.0%-5.0% $10.56 $12.65 Method Terminal Year FCF: $694.7M 52-Week 52-Week High Date: 7/15/26 $15.79 $4.41 52-Week Low Date: 8/6/25 High / Low Wall Street High Target Stock Price: $18.00 $10.00 $18.00 Low Target Stock Price: $10.00 Research Merger Consideration: $16.25 Source: Public filings and S&P Global Market Intelligence as of 7/17/26. PELICAN management projections. Note: Fully-diluted shares outstanding (per TSM): 106.751M basic shares, 14.898M stock options with weighted average strike price of $5.33, 0.627M of RSUs, and 0.575M of PSUs per PELICAN management; assumes that PSUs do not vest or dilute shares outstanding in selected public companies and discounted cash flow analyses. th th 1. Selected companies represent 25 and 75 percentile; assume 3/31/26 cash and debt of $233.2M and $0.9M, respectively, per PELICAN management. th th 2. Selected precedent transactions represent 25 and 75 percentile; assumes PELICAN 6/30/26 cash and debt of $212.7M and $1.8M, respectively, per PELICAN management. 12 3. Discounted cash flow includes three gross equity financings (gross spread of 6.0%) per PELICAN management: gross financing in Q4 2026 of $79.3M at $11.70 per share, resulting in 6.773M additional shares and net proceeds of $74.5M, gross financing in Q4 2027 of $159.6M at $14.89 per share, resulting in 10.714M additional shares and net proceeds of $150.0M, and gross financing in 2029 of $319.1M at $23.40 per share, resulting in 13.636M additional shares and net proceeds of $300.0M. Assumes PELICAN cash and debt of $737.2M and $1.8M, respectively, as of 6/30/26, inclusive of $524.5M pro forma adjustment for forecasted equity raises, per PELICAN management. Includes estimated impact of Federal NOLs. Discounted Selected Precedent Selected Public Companies Cash Flow Informational (2) (1) Transactions Analysis Analysis (3) Analysis
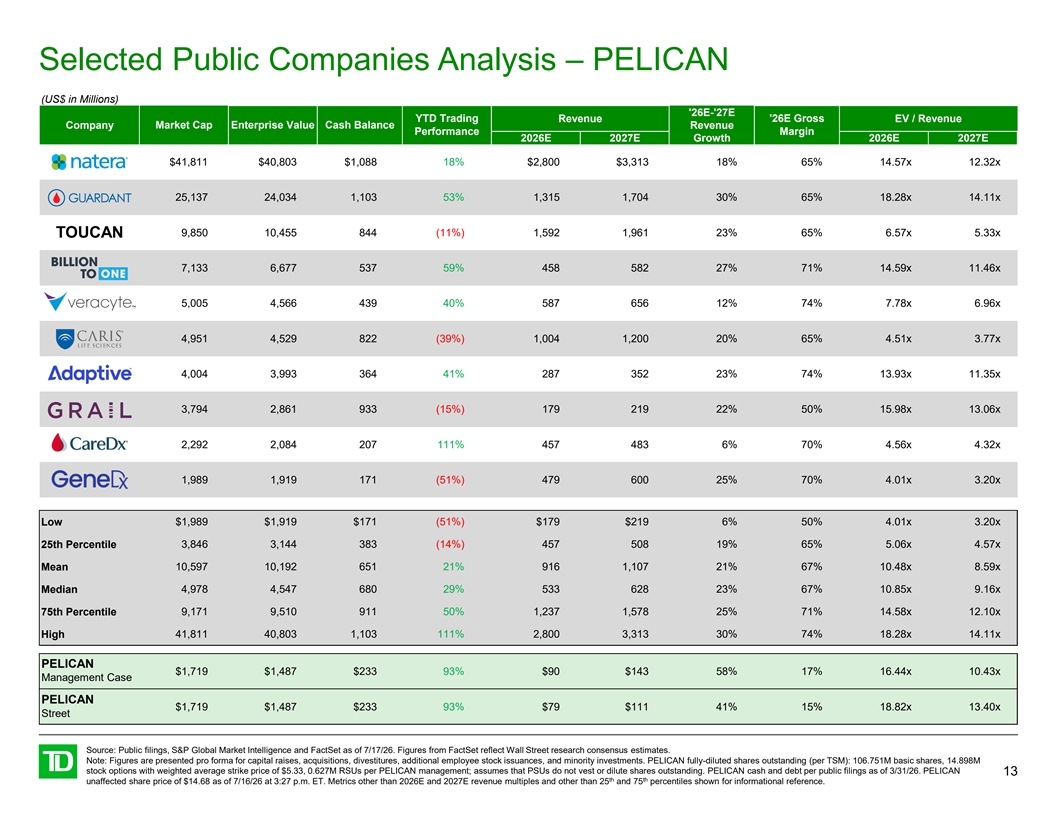
Selected Public Companies Analysis – PELICAN (US$ in Millions) '26E-'27E YTD Trading Revenue '26E Gross EV / Revenue Company Market Cap Enterprise Value Cash Balance Revenue Performance Margin 2026E 2027E Growth 2026E 2027E $41,811 $40,803 $1,088 18% $2,800 $3,313 18% 65% 14.57x 12.32x 25,137 24,034 1,103 53% 1,315 1,704 30% 65% 18.28x 14.11x 9,850 10,455 844 (11%) 1,592 1,961 23% 65% 6.57x 5.33x TOUCAN 7,133 6,677 537 59% 458 582 27% 71% 14.59x 11.46x 5,005 4,566 439 40% 587 656 12% 74% 7.78x 6.96x 4,951 4,529 822 (39%) 1,004 1,200 20% 65% 4.51x 3.77x 4,004 3,993 364 41% 287 352 23% 74% 13.93x 11.35x 3,794 2,861 933 (15%) 179 219 22% 50% 15.98x 13.06x 2,292 2,084 207 111% 457 483 6% 70% 4.56x 4.32x 1,989 1,919 171 (51%) 479 600 25% 70% 4.01x 3.20x Low $1,989 $1,919 $171 (51%) $179 $219 6% 50% 4.01x 3.20x 25th Percentile 3,846 3,144 383 (14%) 457 508 19% 65% 5.06x 4.57x Mean 10,597 10,192 651 21% 916 1,107 21% 67% 10.48x 8.59x Median 4,978 4,547 680 29% 533 628 23% 67% 10.85x 9.16x 75th Percentile 9,171 9,510 911 50% 1,237 1,578 25% 71% 14.58x 12.10x High 41,811 40,803 1,103 111% 2,800 3,313 30% 74% 18.28x 14.11x PELICAN $1,719 $1,487 $233 93% $90 $143 58% 17% 16.44x 10.43x Management Case PELICAN $1,719 $1,487 $233 93% $79 $111 41% 15% 18.82x 13.40x Street Source: Public filings, S&P Global Market Intelligence and FactSet as of 7/17/26. Figures from FactSet reflect Wall Street research consensus estimates. Note: Figures are presented pro forma for capital raises, acquisitions, divestitures, additional employee stock issuances, and minority investments. PELICAN fully-diluted shares outstanding (per TSM): 106.751M basic shares, 14.898M stock options with weighted average strike price of $5.33, 0.627M RSUs per PELICAN management; assumes that PSUs do not vest or dilute shares outstanding. PELICAN cash and debt per public filings as of 3/31/26. PELICAN 13 th th unaffected share price of $14.68 as of 7/16/26 at 3:27 p.m. ET. Metrics other than 2026E and 2027E revenue multiples and other than 25 and 75 percentiles shown for informational reference.
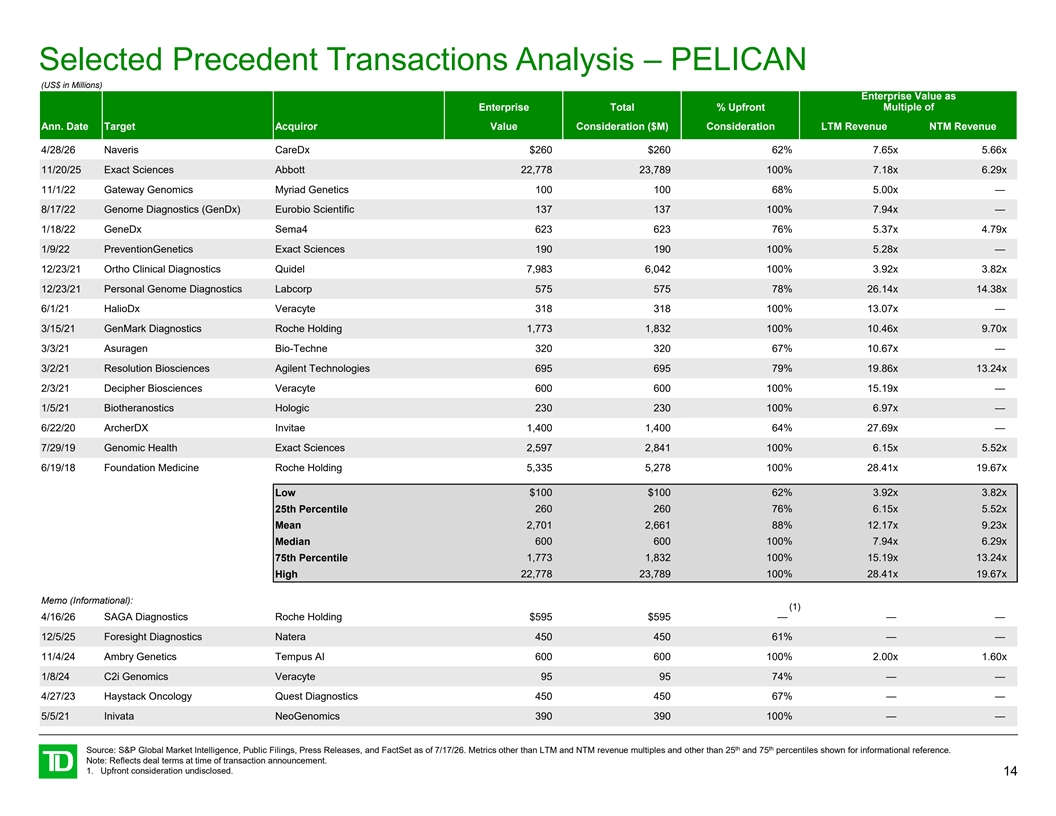
Selected Precedent Transactions Analysis – PELICAN (US$ in Millions) Enterprise Value as Enterprise Total % Upfront Multiple of Ann. Date Target Acquiror Value Consideration ($M) Consideration LTM Revenue NTM Revenue 4/28/26 Naveris CareDx $260 $260 62% 7.65x 5.66x 11/20/25 Exact Sciences Abbott 22,778 23,789 100% 7.18x 6.29x 11/1/22 Gateway Genomics Myriad Genetics 100 100 68% 5.00x — 8/17/22 Genome Diagnostics (GenDx) Eurobio Scientific 137 137 100% 7.94x — 1/18/22 GeneDx Sema4 623 623 76% 5.37x 4.79x 1/9/22 PreventionGenetics Exact Sciences 190 190 100% 5.28x — 12/23/21 Ortho Clinical Diagnostics Quidel 7,983 6,042 100% 3.92x 3.82x 12/23/21 Personal Genome Diagnostics Labcorp 575 575 78% 26.14x 14.38x 6/1/21 HalioDx Veracyte 318 318 100% 13.07x — 3/15/21 GenMark Diagnostics Roche Holding 1,773 1,832 100% 10.46x 9.70x 3/3/21 Asuragen Bio-Techne 320 320 67% 10.67x — 3/2/21 Resolution Biosciences Agilent Technologies 695 695 79% 19.86x 13.24x 2/3/21 Decipher Biosciences Veracyte 600 600 100% 15.19x — 1/5/21 Biotheranostics Hologic 230 230 100% 6.97x — 6/22/20 ArcherDX Invitae 1,400 1,400 64% 27.69x — 7/29/19 Genomic Health Exact Sciences 2,597 2,841 100% 6.15x 5.52x 6/19/18 Foundation Medicine Roche Holding 5,335 5,278 100% 28.41x 19.67x Low $100 $100 62% 3.92x 3.82x 260 260 76% 6.15x 5.52x 25th Percentile Mean 2,701 2,661 88% 12.17x 9.23x Median 600 600 100% 7.94x 6.29x 75th Percentile 1,773 1,832 100% 15.19x 13.24x High 22,778 23,789 100% 28.41x 19.67x Memo (Informational): (1) 4/16/26 SAGA Diagnostics Roche Holding $595 $595 — — — 12/5/25 Foresight Diagnostics Natera 450 450 61% — — 11/4/24 Ambry Genetics Tempus AI 600 600 100% 2.00x 1.60x 1/8/24 C2i Genomics Veracyte 95 95 74% — — 4/27/23 Haystack Oncology Quest Diagnostics 450 450 67% — — 5/5/21 Inivata NeoGenomics 390 390 100% — — th th Source: S&P Global Market Intelligence, Public Filings, Press Releases, and FactSet as of 7/17/26. Metrics other than LTM and NTM revenue multiples and other than 25 and 75 percentiles shown for informational reference. Note: Reflects deal terms at time of transaction announcement. 1. Upfront consideration undisclosed. 14
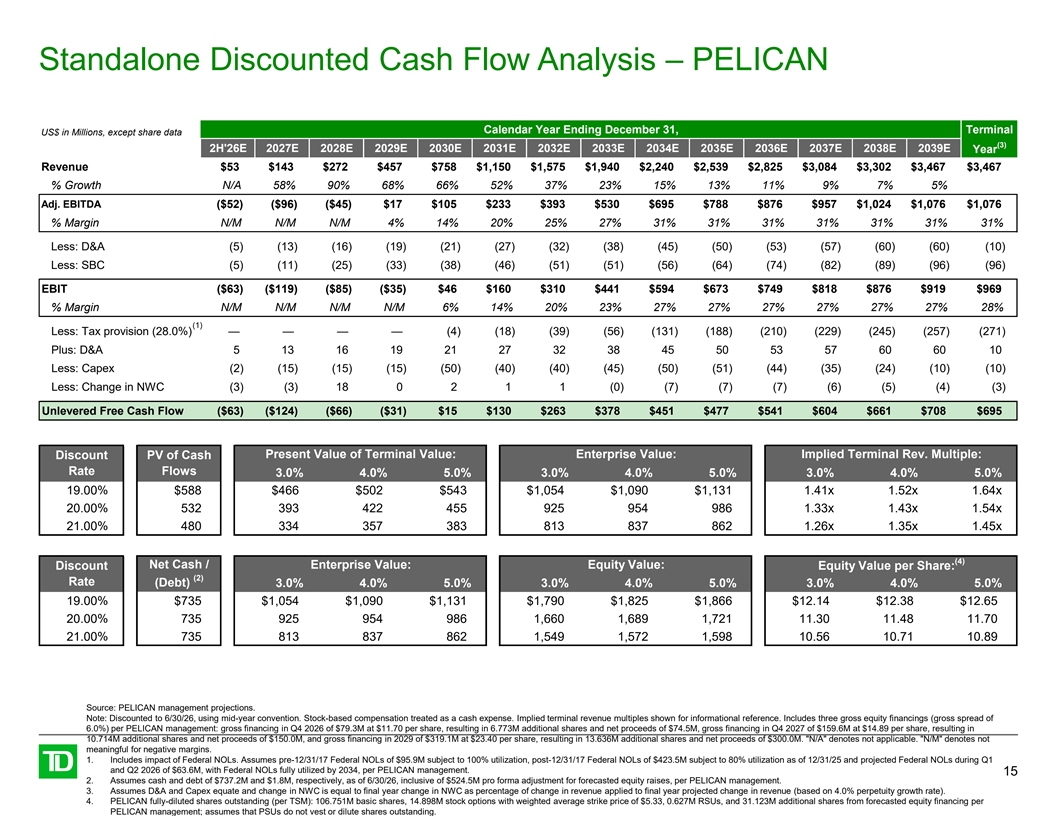
Standalone Discounted Cash Flow Analysis – PELICAN Calendar Year Ending December 31, Terminal US$ in Millions, except share data (3) 2H'26E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E 2036E 2037E 2038E 2039E Year Revenue $53 $143 $272 $457 $758 $1,150 $1,575 $1,940 $2,240 $2,539 $2,825 $3,084 $3,302 $3,467 $3,467 % Growth N/A 58% 90% 68% 66% 52% 37% 23% 15% 13% 11% 9% 7% 5% Adj. EBITDA ($52) ($96) ($45) $17 $105 $233 $393 $530 $695 $788 $876 $957 $1,024 $1,076 $1,076 % Margin N/M N/M N/M 4% 14% 20% 25% 27% 31% 31% 31% 31% 31% 31% 31% Less: D&A (5) (13) (16) (19) (21) (27) (32) (38) (45) (50) (53) (57) (60) (60) (10) Less: SBC (5) (11) (25) (33) (38) (46) (51) (51) (56) (64) (74) (82) (89) (96) (96) EBIT ($63) ($119) ($85) ($35) $46 $160 $310 $441 $594 $673 $749 $818 $876 $919 $969 % Margin N/M N/M N/M N/M 6% 14% 20% 23% 27% 27% 27% 27% 27% 27% 28% (1) Less: Tax provision (28.0%) — — — — (4) (18) (39) (56) (131) (188) (210) (229) (245) (257) (271) Plus: D&A 5 13 16 19 21 27 32 38 45 50 53 57 60 60 10 Less: Capex (2) (15) (15) (15) (50) (40) (40) (45) (50) (51) (44) (35) (24) (10) (10) Less: Change in NWC (3) (3) 18 0 2 1 1 (0) (7) (7) (7) (6) (5) (4) (3) Unlevered Free Cash Flow ($63) ($124) ($66) ($31) $15 $130 $263 $378 $451 $477 $541 $604 $661 $708 $695 Present Value of Terminal Value: Enterprise Value: Implied Terminal Rev. Multiple: Discount PV of Cash Rate Flows 3.0% 4.0% 5.0% 3.0% 4.0% 5.0% 3.0% 4.0% 5.0% 19.00% $588 $466 $502 $543 $1,054 $1,090 $1,131 1.41x 1.52x 1.64x 20.00% 532 393 422 455 925 954 986 1.33x 1.43x 1.54x 21.00% 480 334 357 383 813 837 862 1.26x 1.35x 1.45x (4) Discount Net Cash / Enterprise Value: Equity Value: Equity Value per Share: (2) Rate (Debt) 3.0% 4.0% 5.0% 3.0% 4.0% 5.0% 3.0% 4.0% 5.0% 19.00% $735 $1,054 $1,090 $1,131 $1,790 $1,825 $1,866 $12.14 $12.38 $12.65 20.00% 735 925 954 986 1,660 1,689 1,721 11.30 11.48 11.70 21.00% 735 813 837 862 1,549 1,572 1,598 10.56 10.71 10.89 Source: PELICAN management projections. Note: Discounted to 6/30/26, using mid-year convention. Stock-based compensation treated as a cash expense. Implied terminal revenue multiples shown for informational reference. Includes three gross equity financings (gross spread of 6.0%) per PELICAN management: gross financing in Q4 2026 of $79.3M at $11.70 per share, resulting in 6.773M additional shares and net proceeds of $74.5M, gross financing in Q4 2027 of $159.6M at $14.89 per share, resulting in 10.714M additional shares and net proceeds of $150.0M, and gross financing in 2029 of $319.1M at $23.40 per share, resulting in 13.636M additional shares and net proceeds of $300.0M. N/A denotes not applicable. N/M denotes not meaningful for negative margins. 1. Includes impact of Federal NOLs. Assumes pre-12/31/17 Federal NOLs of $95.9M subject to 100% utilization, post-12/31/17 Federal NOLs of $423.5M subject to 80% utilization as of 12/31/25 and projected Federal NOLs during Q1 and Q2 2026 of $63.6M, with Federal NOLs fully utilized by 2034, per PELICAN management. 15 2. Assumes cash and debt of $737.2M and $1.8M, respectively, as of 6/30/26, inclusive of $524.5M pro forma adjustment for forecasted equity raises, per PELICAN management. 3. Assumes D&A and Capex equate and change in NWC is equal to final year change in NWC as percentage of change in revenue applied to final year projected change in revenue (based on 4.0% perpetuity growth rate). 4. PELICAN fully-diluted shares outstanding (per TSM): 106.751M basic shares, 14.898M stock options with weighted average strike price of $5.33, 0.627M RSUs, and 31.123M additional shares from forecasted equity financing per PELICAN management; assumes that PSUs do not vest or dilute shares outstanding.
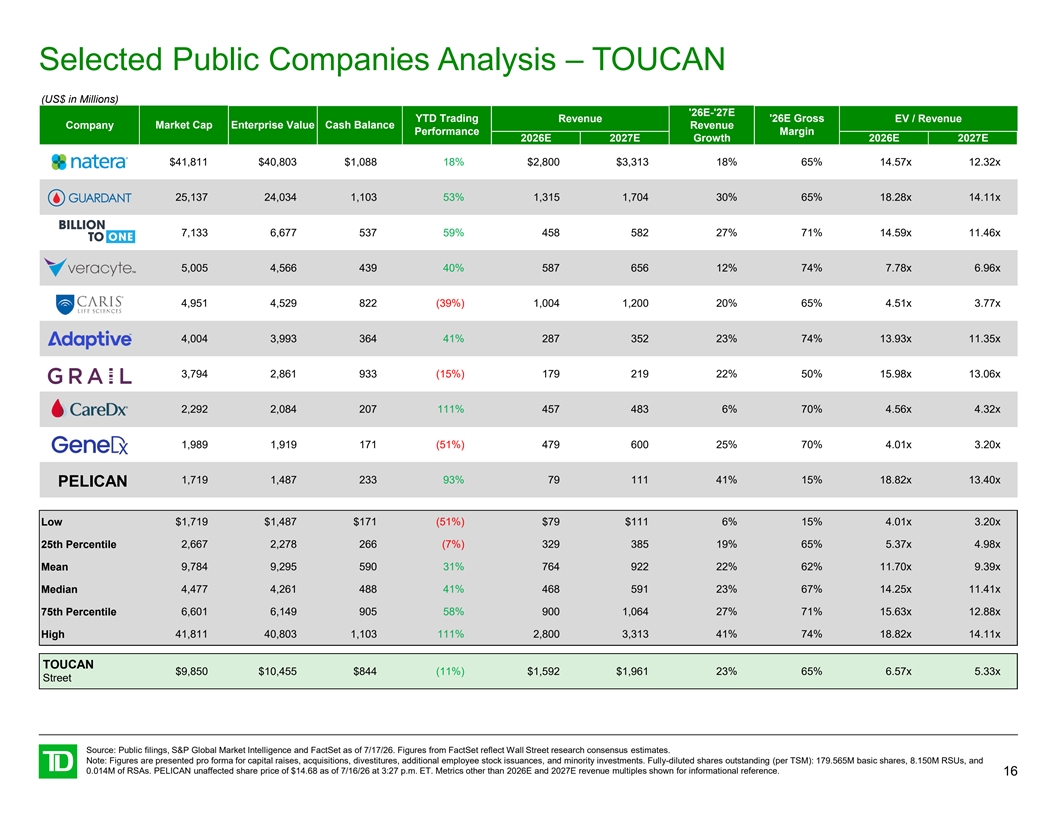
Selected Public Companies Analysis – TOUCAN (US$ in Millions) '26E-'27E YTD Trading Revenue '26E Gross EV / Revenue Company Market Cap Enterprise Value Cash Balance Revenue Performance Margin 2026E 2027E Growth 2026E 2027E $41,811 $40,803 $1,088 18% $2,800 $3,313 18% 65% 14.57x 12.32x 25,137 24,034 1,103 53% 1,315 1,704 30% 65% 18.28x 14.11x 7,133 6,677 537 59% 458 582 27% 71% 14.59x 11.46x 5,005 4,566 439 40% 587 656 12% 74% 7.78x 6.96x 4,951 4,529 822 (39%) 1,004 1,200 20% 65% 4.51x 3.77x 4,004 3,993 364 41% 287 352 23% 74% 13.93x 11.35x 3,794 2,861 933 (15%) 179 219 22% 50% 15.98x 13.06x 2,292 2,084 207 111% 457 483 6% 70% 4.56x 4.32x 1,989 1,919 171 (51%) 479 600 25% 70% 4.01x 3.20x 1,719 1,487 233 93% 79 111 41% 15% 18.82x 13.40x PELICAN Low $1,719 $1,487 $171 (51%) $79 $111 6% 15% 4.01x 3.20x 25th Percentile 2,667 2,278 266 (7%) 329 385 19% 65% 5.37x 4.98x Mean 9,784 9,295 590 31% 764 922 22% 62% 11.70x 9.39x Median 4,477 4,261 488 41% 468 591 23% 67% 14.25x 11.41x 75th Percentile 6,601 6,149 905 58% 900 1,064 27% 71% 15.63x 12.88x High 41,811 40,803 1,103 111% 2,800 3,313 41% 74% 18.82x 14.11x TOUCAN $9,850 $10,455 $844 (11%) $1,592 $1,961 23% 65% 6.57x 5.33x Street Source: Public filings, S&P Global Market Intelligence and FactSet as of 7/17/26. Figures from FactSet reflect Wall Street research consensus estimates. Note: Figures are presented pro forma for capital raises, acquisitions, divestitures, additional employee stock issuances, and minority investments. Fully-diluted shares outstanding (per TSM): 179.565M basic shares, 8.150M RSUs, and 0.014M of RSAs. PELICAN unaffected share price of $14.68 as of 7/16/26 at 3:27 p.m. ET. Metrics other than 2026E and 2027E revenue multiples shown for informational reference. 16
4. Appendix
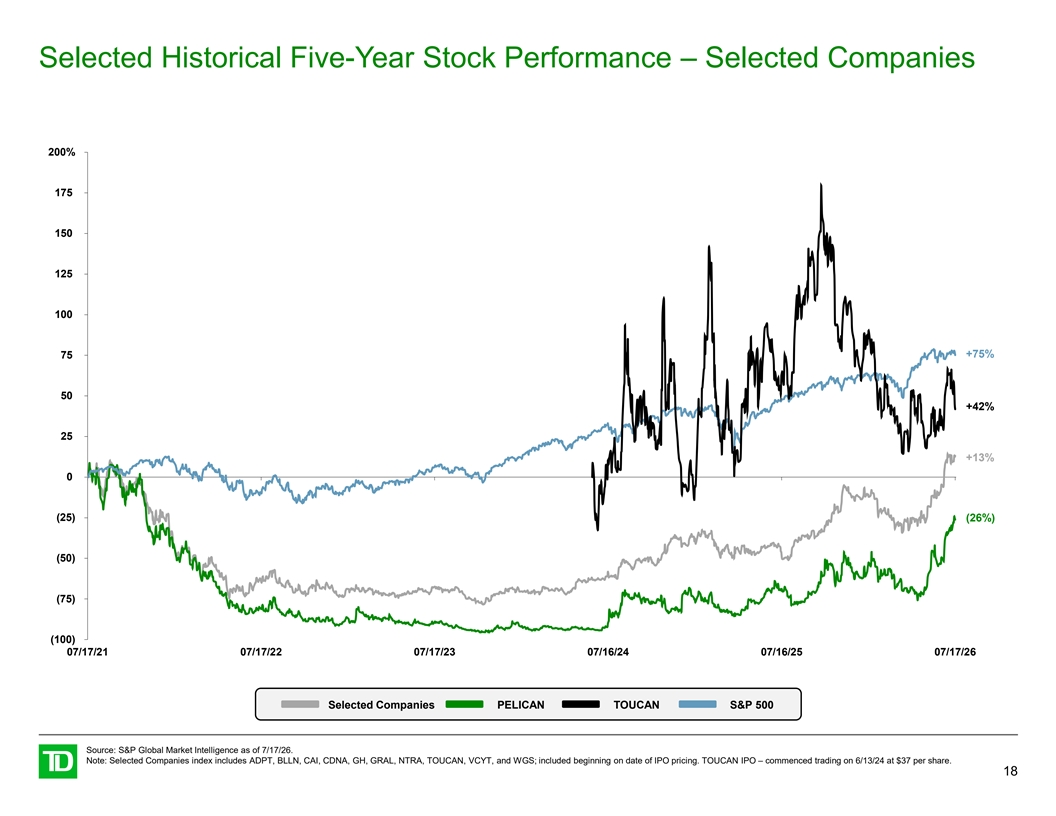
Selected Historical Five-Year Stock Performance – Selected Companies 200% 175 150 125 100 +75% 75 50 +42% 25 +13% 0 (25) (26%) (50) (75) (100) 07/17/21 07/17/22 07/17/23 07/16/24 07/16/25 07/17/26 Selected Companies PELICAN TOUCAN S&P 500 Source: S&P Global Market Intelligence as of 7/17/26. Note: Selected Companies index includes ADPT, BLLN, CAI, CDNA, GH, GRAL, NTRA, TOUCAN, VCYT, and WGS; included beginning on date of IPO pricing. TOUCAN IPO – commenced trading on 6/13/24 at $37 per share. 18
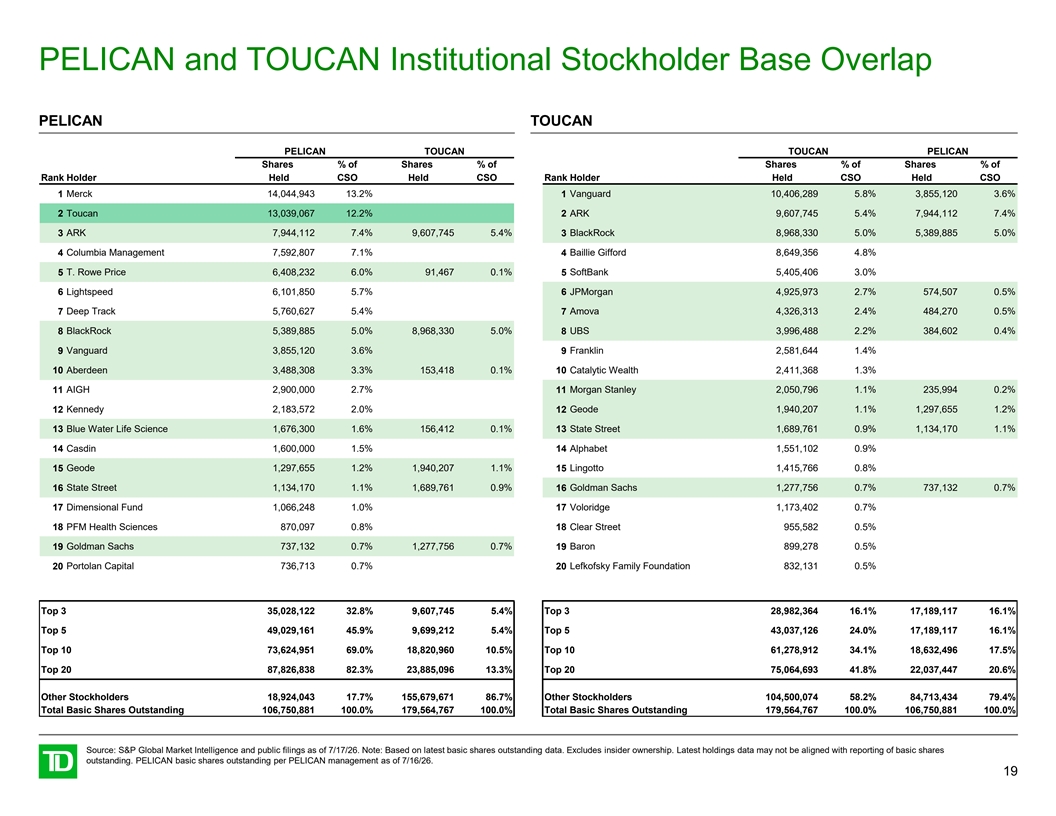
PELICAN and TOUCAN Institutional Stockholder Base Overlap PELICAN TOUCAN PELICAN TOUCAN TOUCAN PELICAN Shares % of Shares % of Shares % of Shares % of Rank Holder Held CSO Held CSO Rank Holder Held CSO Held CSO 1 Merck 14,044,943 13.2% 1 Vanguard 10,406,289 5.8% 3,855,120 3.6% 2 Toucan 13,039,067 12.2% 2 ARK 9,607,745 5.4% 7,944,112 7.4% 3 ARK 7,944,112 7.4% 9,607,745 5.4% 3 BlackRock 8,968,330 5.0% 5,389,885 5.0% 4 Columbia Management 7,592,807 7.1% 4 Baillie Gifford 8,649,356 4.8% 5 T. Rowe Price 6,408,232 6.0% 91,467 0.1% 5 SoftBank 5,405,406 3.0% Lightspeed 6,101,850 5.7% JPMorgan 4,925,973 2.7% 574,507 0.5% 6 6 7 Deep Track 5,760,627 5.4% 7 Amova 4,326,313 2.4% 484,270 0.5% 8 BlackRock 5,389,885 5.0% 8,968,330 5.0% 8 UBS 3,996,488 2.2% 384,602 0.4% 9 Vanguard 3,855,120 3.6% 9 Franklin 2,581,644 1.4% 10 Aberdeen 3,488,308 3.3% 153,418 0.1% 10 Catalytic Wealth 2,411,368 1.3% 11 AIGH 2,900,000 2.7% 11 Morgan Stanley 2,050,796 1.1% 235,994 0.2% 12 Kennedy 2,183,572 2.0% 12 Geode 1,940,207 1.1% 1,297,655 1.2% 13 Blue Water Life Science 1,676,300 1.6% 156,412 0.1% 13 State Street 1,689,761 0.9% 1,134,170 1.1% 14 Casdin 1,600,000 1.5% 14 Alphabet 1,551,102 0.9% 15 Geode 1,297,655 1.2% 1,940,207 1.1% 15 Lingotto 1,415,766 0.8% 16 State Street 1,134,170 1.1% 1,689,761 0.9% 16 Goldman Sachs 1,277,756 0.7% 737,132 0.7% 17 Dimensional Fund 1,066,248 1.0% 17 Voloridge 1,173,402 0.7% 18 PFM Health Sciences 870,097 0.8% 18 Clear Street 955,582 0.5% Goldman Sachs 737,132 0.7% 1,277,756 0.7% Baron 899,278 0.5% 19 19 20 Portolan Capital 736,713 0.7% 20 Lefkofsky Family Foundation 832,131 0.5% Top 3 35,028,122 32.8% 9,607,745 5.4% Top 3 28,982,364 16.1% 17,189,117 16.1% Top 5 49,029,161 45.9% 9,699,212 5.4% Top 5 43,037,126 24.0% 17,189,117 16.1% Top 10 73,624,951 69.0% 18,820,960 10.5% Top 10 61,278,912 34.1% 18,632,496 17.5% Top 20 87,826,838 82.3% 23,885,096 13.3% Top 20 75,064,693 41.8% 22,037,447 20.6% Other Stockholders 18,924,043 17.7% 155,679,671 86.7% Other Stockholders 104,500,074 58.2% 84,713,434 79.4% Total Basic Shares Outstanding 106,750,881 100.0% 179,564,767 100.0% Total Basic Shares Outstanding 179,564,767 100.0% 106,750,881 100.0% Source: S&P Global Market Intelligence and public filings as of 7/17/26. Note: Based on latest basic shares outstanding data. Excludes insider ownership. Latest holdings data may not be aligned with reporting of basic shares outstanding. PELICAN basic shares outstanding per PELICAN management as of 7/16/26. 19
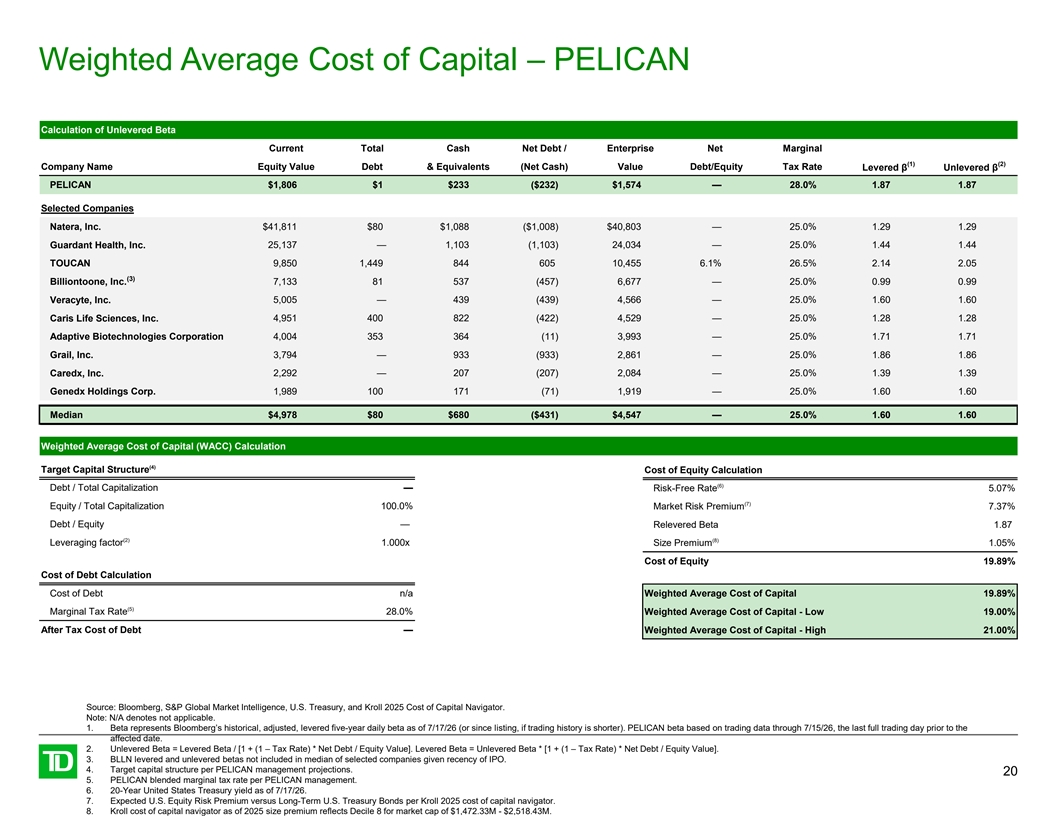
Weighted Average Cost of Capital – PELICAN Calculation of Unlevered Beta Current Total Cash Net Debt / Enterprise Net Marginal (1) (2) Company Name Equity Value Debt & Equivalents (Net Cash) Value Debt/Equity Tax Rate Levered β Unlevered β PELICAN $1,806 $1 $233 ($232) $1,574 — 28.0% 1.87 1.87 Selected Companies Natera, Inc. $41,811 $80 $1,088 ($1,008) $40,803 — 25.0% 1.29 1.29 Guardant Health, Inc. 25,137 — 1,103 (1,103) 24,034 — 25.0% 1.44 1.44 TOUCAN 9,850 1,449 844 605 10,455 6.1% 26.5% 2.14 2.05 (3) Billiontoone, Inc. 7,133 81 537 (457) 6,677 — 25.0% 0.99 0.99 5,005 — 439 (439) 4,566 — 25.0% 1.60 1.60 Veracyte, Inc. Caris Life Sciences, Inc. 4,951 400 822 (422) 4,529 — 25.0% 1.28 1.28 Adaptive Biotechnologies Corporation 4,004 353 364 (11) 3,993 — 25.0% 1.71 1.71 Grail, Inc. 3,794 — 933 (933) 2,861 — 25.0% 1.86 1.86 2,292 — 207 (207) 2,084 — 25.0% 1.39 1.39 Caredx, Inc. Genedx Holdings Corp. 1,989 100 171 (71) 1,919 — 25.0% 1.60 1.60 Median $4,978 $80 $680 ($431) $4,547 — 25.0% 1.60 1.60 Weighted Average Cost of Capital (WACC) Calculation (4) Target Capital Structure Cost of Equity Calculation (6) Debt / Total Capitalization — Risk-Free Rate 5.07% (7) Equity / Total Capitalization 100.0% Market Risk Premium 7.37% Debt / Equity — Relevered Beta 1.87 (2) (8) Leveraging factor 1.000x Size Premium 1.05% Cost of Equity 19.89% Cost of Debt Calculation Cost of Debt n/a Weighted Average Cost of Capital 19.89% (5) Marginal Tax Rate 28.0% Weighted Average Cost of Capital - Low 19.00% After Tax Cost of Debt — Weighted Average Cost of Capital - High 21.00% Source: Bloomberg, S&P Global Market Intelligence, U.S. Treasury, and Kroll 2025 Cost of Capital Navigator. Note: N/A denotes not applicable. 1. Beta represents Bloomberg’s historical, adjusted, levered five-year daily beta as of 7/17/26 (or since listing, if trading history is shorter). PELICAN beta based on trading data through 7/15/26, the last full trading day prior to the affected date. 2. Unlevered Beta = Levered Beta / [1 + (1 – Tax Rate) * Net Debt / Equity Value]. Levered Beta = Unlevered Beta * [1 + (1 – Tax Rate) * Net Debt / Equity Value]. 3. BLLN levered and unlevered betas not included in median of selected companies given recency of IPO. 4. Target capital structure per PELICAN management projections. 20 5. PELICAN blended marginal tax rate per PELICAN management. 6. 20-Year United States Treasury yield as of 7/17/26. 7. Expected U.S. Equity Risk Premium versus Long-Term U.S. Treasury Bonds per Kroll 2025 cost of capital navigator. 8. Kroll cost of capital navigator as of 2025 size premium reflects Decile 8 for market cap of $1,472.33M - $2,518.43M.
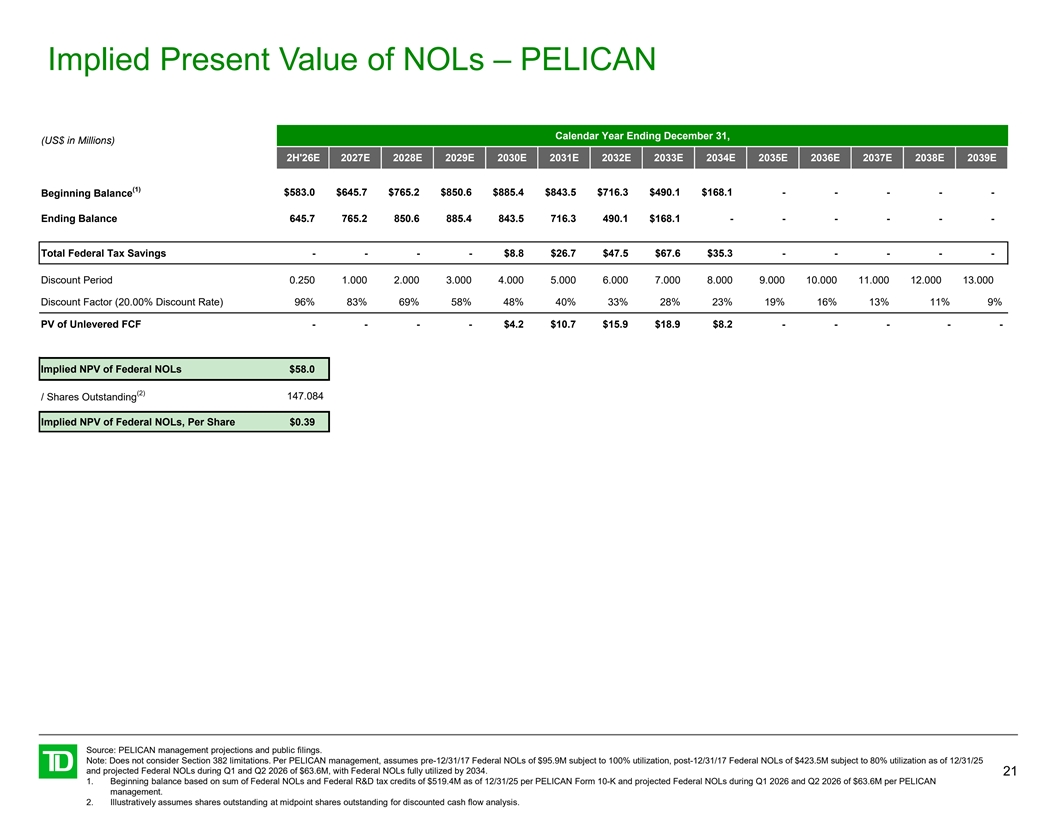
Implied Present Value of NOLs – PELICAN Calendar Year Ending December 31, (US$ in Millions) 2H'26E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E 2036E 2037E 2038E 2039E (1) $583.0 $645.7 $765.2 $850.6 $885.4 $843.5 $716.3 $490.1 $168.1 - - - - - Beginning Balance Ending Balance 645.7 765.2 850.6 885.4 843.5 716.3 490.1 $168.1 - - - - - - Total Federal Tax Savings - - - - $8.8 $26.7 $47.5 $67.6 $35.3 - - - - - Discount Period 0.250 1.000 2.000 3.000 4.000 5.000 6.000 7.000 8.000 9.000 10.000 11.000 12.000 13.000 Discount Factor (20.00% Discount Rate) 96% 83% 69% 58% 48% 40% 33% 28% 23% 19% 16% 13% 11% 9% PV of Unlevered FCF - - - - $4.2 $10.7 $15.9 $18.9 $8.2 - - - - - Implied NPV of Federal NOLs $58.0 (2) 147.084 / Shares Outstanding Implied NPV of Federal NOLs, Per Share $0.39 Source: PELICAN management projections and public filings. Note: Does not consider Section 382 limitations. Per PELICAN management, assumes pre-12/31/17 Federal NOLs of $95.9M subject to 100% utilization, post-12/31/17 Federal NOLs of $423.5M subject to 80% utilization as of 12/31/25 and projected Federal NOLs during Q1 and Q2 2026 of $63.6M, with Federal NOLs fully utilized by 2034. 21 1. Beginning balance based on sum of Federal NOLs and Federal R&D tax credits of $519.4M as of 12/31/25 per PELICAN Form 10-K and projected Federal NOLs during Q1 2026 and Q2 2026 of $63.6M per PELICAN management. 2. Illustratively assumes shares outstanding at midpoint shares outstanding for discounted cash flow analysis.
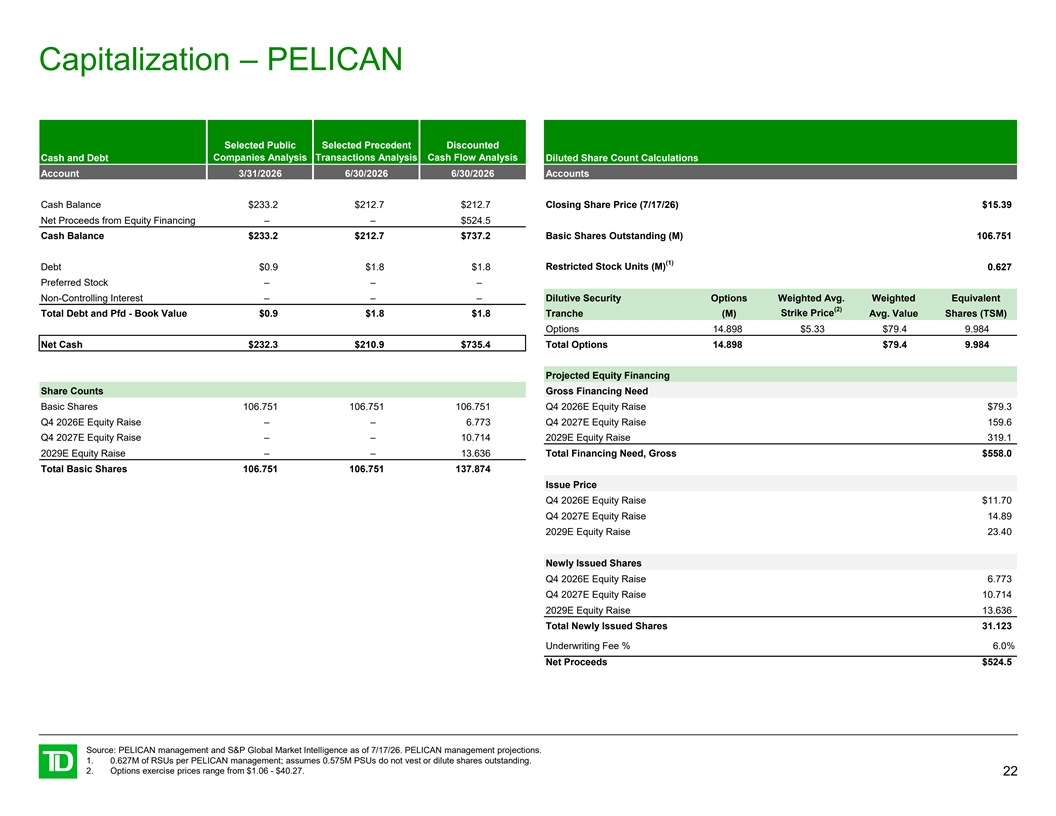
Capitalization – PELICAN Selected Public Selected Precedent Discounted Cash and Debt Companies Analysis Transactions Analysis Cash Flow Analysis Diluted Share Count Calculations Account 3/31/2026 6/30/2026 6/30/2026 Accounts Cash Balance $233.2 $212.7 $212.7 Closing Share Price (7/17/26) $15.39 Net Proceeds from Equity Financing – – $524.5 Cash Balance $233.2 $212.7 $737.2 Basic Shares Outstanding (M) 106.751 (1) Restricted Stock Units (M) Debt $0.9 $1.8 $1.8 0.627 Preferred Stock – – – Non-Controlling Interest – – – Dilutive Security Options Weighted Avg. Weighted Equivalent (2) Strike Price Total Debt and Pfd - Book Value $0.9 $1.8 $1.8 Tranche (M) Avg. Value Shares (TSM) Options 14.898 $5.33 $79.4 9.984 Net Cash $232.3 $210.9 $735.4 Total Options 14.898 $79.4 9.984 Projected Equity Financing Share Counts Gross Financing Need Basic Shares 106.751 106.751 106.751 Q4 2026E Equity Raise $79.3 Q4 2026E Equity Raise – – 6.773 Q4 2027E Equity Raise 159.6 Q4 2027E Equity Raise – – 10.714 2029E Equity Raise 319.1 2029E Equity Raise – – 13.636 Total Financing Need, Gross $558.0 Total Basic Shares 106.751 106.751 137.874 Issue Price Q4 2026E Equity Raise $11.70 Q4 2027E Equity Raise 14.89 2029E Equity Raise 23.40 Newly Issued Shares Q4 2026E Equity Raise 6.773 Q4 2027E Equity Raise 10.714 2029E Equity Raise 13.636 Total Newly Issued Shares 31.123 Underwriting Fee % 6.0% Net Proceeds $524.5 Source: PELICAN management and S&P Global Market Intelligence as of 7/17/26. PELICAN management projections. 1. 0.627M of RSUs per PELICAN management; assumes 0.575M PSUs do not vest or dilute shares outstanding. 2. Options exercise prices range from $1.06 - $40.27. 22
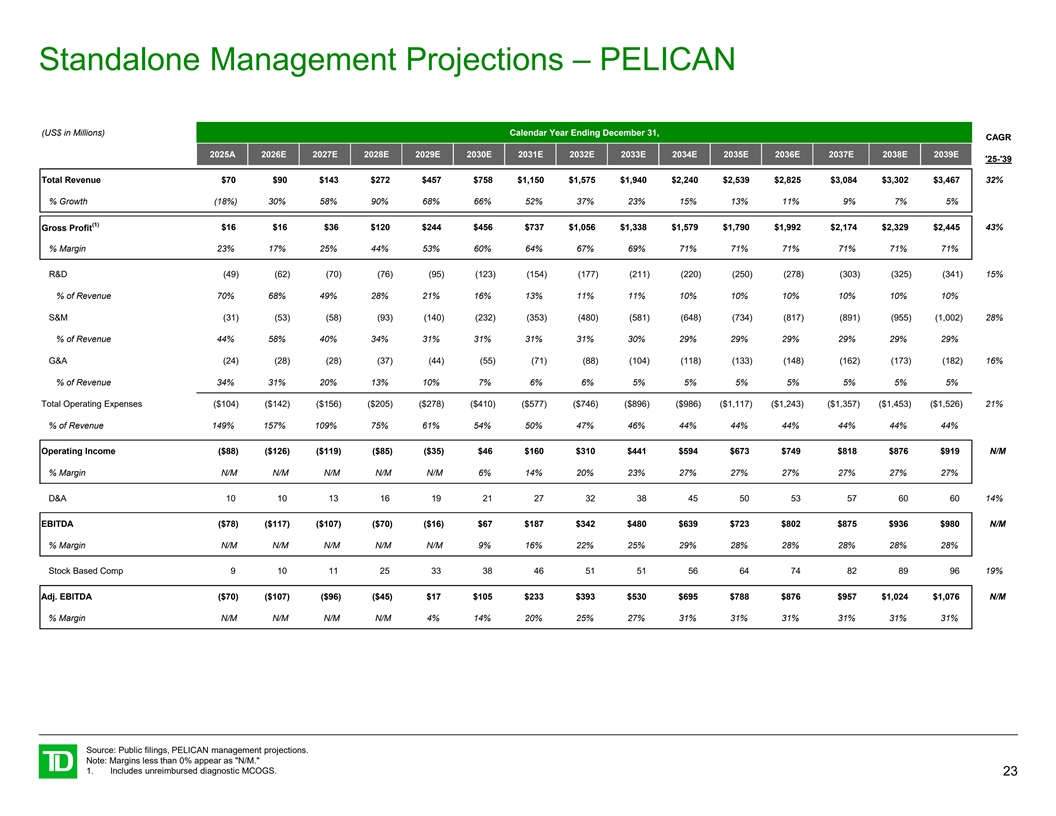
Standalone Management Projections – PELICAN (US$ in Millions) Calendar Year Ending December 31, CAGR 2025A 2026E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E 2036E 2037E 2038E 2039E '25-'39 Total Revenue $70 $90 $143 $272 $457 $758 $1,150 $1,575 $1,940 $2,240 $2,539 $2,825 $3,084 $3,302 $3,467 32% % Growth (18%) 30% 58% 90% 68% 66% 52% 37% 23% 15% 13% 11% 9% 7% 5% (1) Gross Profit $16 $16 $36 $120 $244 $456 $737 $1,056 $1,338 $1,579 $1,790 $1,992 $2,174 $2,329 $2,445 43% % Margin 23% 17% 25% 44% 53% 60% 64% 67% 69% 71% 71% 71% 71% 71% 71% R&D (49) (62) (70) (76) (95) (123) (154) (177) (211) (220) (250) (278) (303) (325) (341) 15% % of Revenue 70% 68% 49% 28% 21% 16% 13% 11% 11% 10% 10% 10% 10% 10% 10% S&M (31) (53) (58) (93) (140) (232) (353) (480) (581) (648) (734) (817) (891) (955) (1,002) 28% % of Revenue 44% 58% 40% 34% 31% 31% 31% 31% 30% 29% 29% 29% 29% 29% 29% G&A (24) (28) (28) (37) (44) (55) (71) (88) (104) (118) (133) (148) (162) (173) (182) 16% % of Revenue 34% 31% 20% 13% 10% 7% 6% 6% 5% 5% 5% 5% 5% 5% 5% Total Operating Expenses ($104) ($142) ($156) ($205) ($278) ($410) ($577) ($746) ($896) ($986) ($1,117) ($1,243) ($1,357) ($1,453) ($1,526) 21% % of Revenue 149% 157% 109% 75% 61% 54% 50% 47% 46% 44% 44% 44% 44% 44% 44% Operating Income ($88) ($126) ($119) ($85) ($35) $46 $160 $310 $441 $594 $673 $749 $818 $876 $919 N/M % Margin N/M N/M N/M N/M N/M 6% 14% 20% 23% 27% 27% 27% 27% 27% 27% D&A 10 10 13 16 19 21 27 32 38 45 50 53 57 60 60 14% EBITDA ($78) ($117) ($107) ($70) ($16) $67 $187 $342 $480 $639 $723 $802 $875 $936 $980 N/M % Margin N/M N/M N/M N/M N/M 9% 16% 22% 25% 29% 28% 28% 28% 28% 28% Stock Based Comp 9 10 11 25 33 38 46 51 51 56 64 74 82 89 96 19% Adj. EBITDA ($70) ($107) ($96) ($45) $17 $105 $233 $393 $530 $695 $788 $876 $957 $1,024 $1,076 N/M % Margin N/M N/M N/M N/M 4% 14% 20% 25% 27% 31% 31% 31% 31% 31% 31% Source: Public filings, PELICAN management projections. Note: Margins less than 0% appear as N/M. 1. Includes unreimbursed diagnostic MCOGS. 23
Exhibit (c)(18) Polaris Financial Forecast Project Polaris July 18, 2026
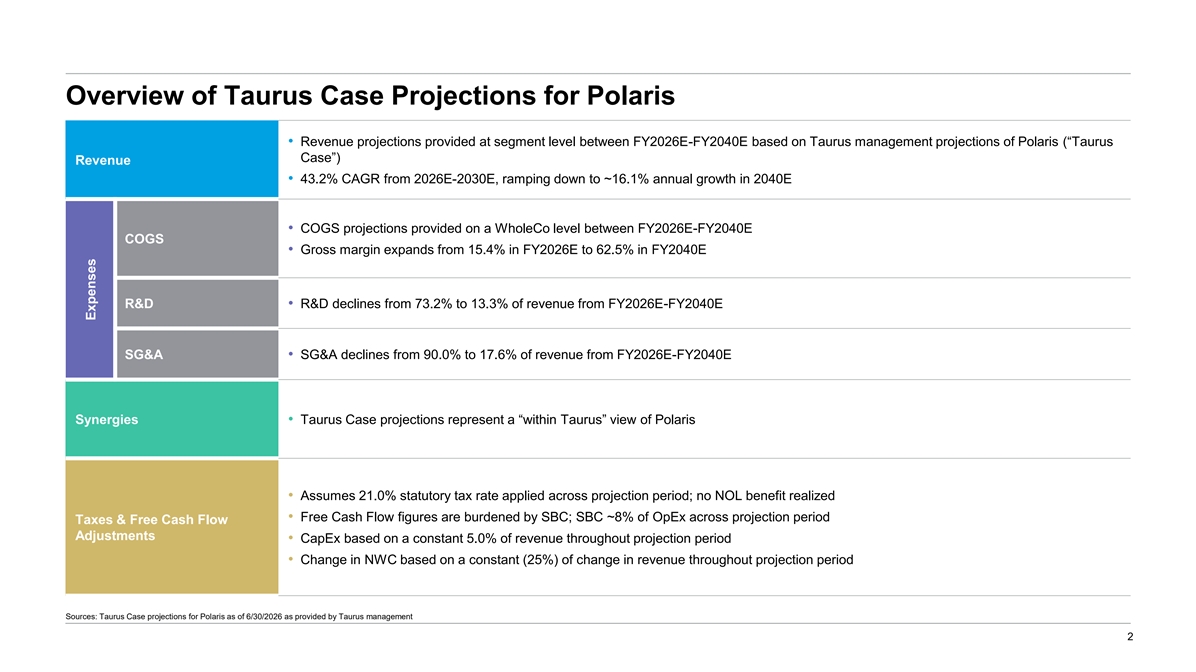
Overview of Taurus Case Projections for Polaris • Revenue projections provided at segment level between FY2026E-FY2040E based on Taurus management projections of Polaris (“Taurus Case”) Revenue • 43.2% CAGR from 2026E-2030E, ramping down to ~16.1% annual growth in 2040E • COGS projections provided on a WholeCo level between FY2026E-FY2040E COGS • Gross margin expands from 15.4% in FY2026E to 62.5% in FY2040E R&D • R&D declines from 73.2% to 13.3% of revenue from FY2026E-FY2040E SG&A • SG&A declines from 90.0% to 17.6% of revenue from FY2026E-FY2040E Synergies • Taurus Case projections represent a “within Taurus” view of Polaris • Assumes 21.0% statutory tax rate applied across projection period; no NOL benefit realized • Free Cash Flow figures are burdened by SBC; SBC ~8% of OpEx across projection period Taxes & Free Cash Flow Adjustments • CapEx based on a constant 5.0% of revenue throughout projection period • Change in NWC based on a constant (25%) of change in revenue throughout projection period Sources: Taurus Case projections for Polaris as of 6/30/2026 as provided by Taurus management 2 Expenses
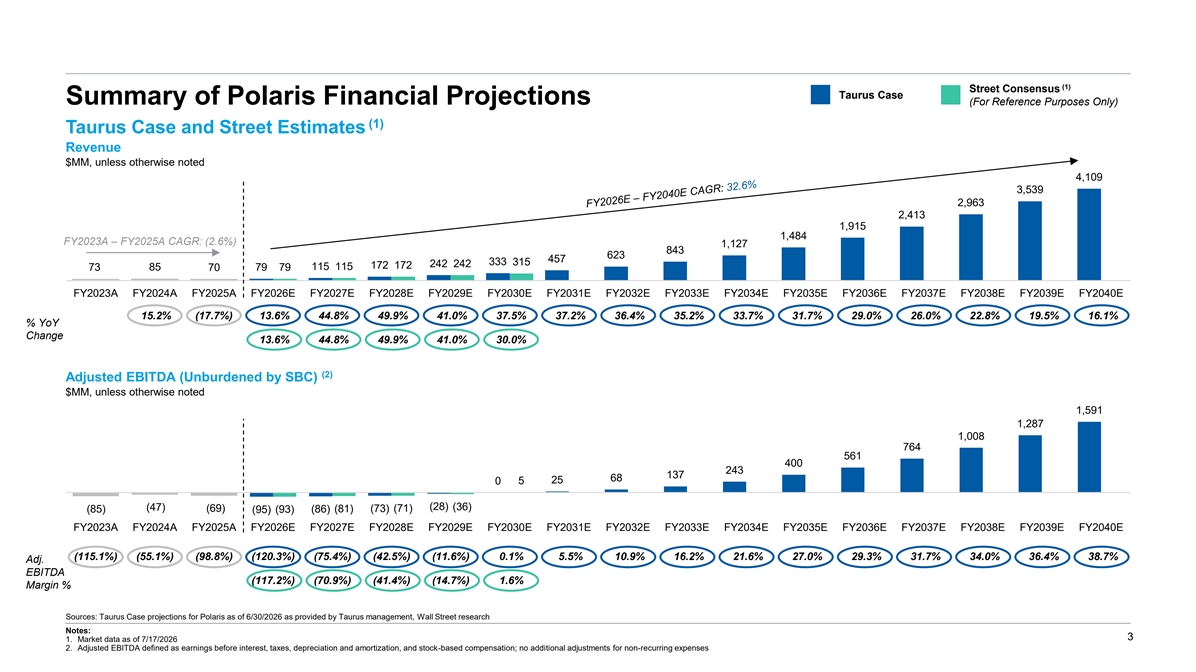
(1) Street Consensus Taurus Case Summary of Polaris Financial Projections (For Reference Purposes Only) (1) Taurus Case and Street Estimates Revenue $MM, unless otherwise noted 4,109 3,539 2,963 2,413 1,915 1,484 FY2023A – FY2025A CAGR: (2.6%) 1,127 843 623 457 333 315 242 242 172 172 73 85 70 79 79 115 115 FY2023A FY2024A FY2025A FY2026E FY2027E FY2028E FY2029E FY2030E FY2031E FY2032E FY2033E FY2034E FY2035E FY2036E FY2037E FY2038E FY2039E FY2040E 15.2% (17.7%) 13.6% 44.8% 49.9% 41.0% 37.5% 37.2% 36.4% 35.2% 33.7% 31.7% 29.0% 26.0% 22.8% 19.5% 16.1% % YoY Change 13.6% 44.8% 49.9% 41.0% 30.0% (2) Adjusted EBITDA (Unburdened by SBC) $MM, unless otherwise noted 1,591 1,287 1,008 764 561 400 243 137 68 5 25 0 (47) (28) (36) (69) (81) (73) (71) (85) (95) (93) (86) FY2023A FY2024A FY2025A FY2026E FY2027E FY2028E FY2029E FY2030E FY2031E FY2032E FY2033E FY2034E FY2035E FY2036E FY2037E FY2038E FY2039E FY2040E (115.1%) (55.1%) (98.8%) (120.3%) (75.4%) (42.5%) (11.6%) 0.1% 5.5% 10.9% 16.2% 21.6% 27.0% 29.3% 31.7% 34.0% 36.4% 38.7% Adj. EBITDA (117.2%) (70.9%) (41.4%) (14.7%) 1.6% Margin % Sources: Taurus Case projections for Polaris as of 6/30/2026 as provided by Taurus management, Wall Street research Notes: 3 1. Market data as of 7/17/2026 2. Adjusted EBITDA defined as earnings before interest, taxes, depreciation and amortization, and stock-based compensation; no additional adjustments for non-recurring expenses
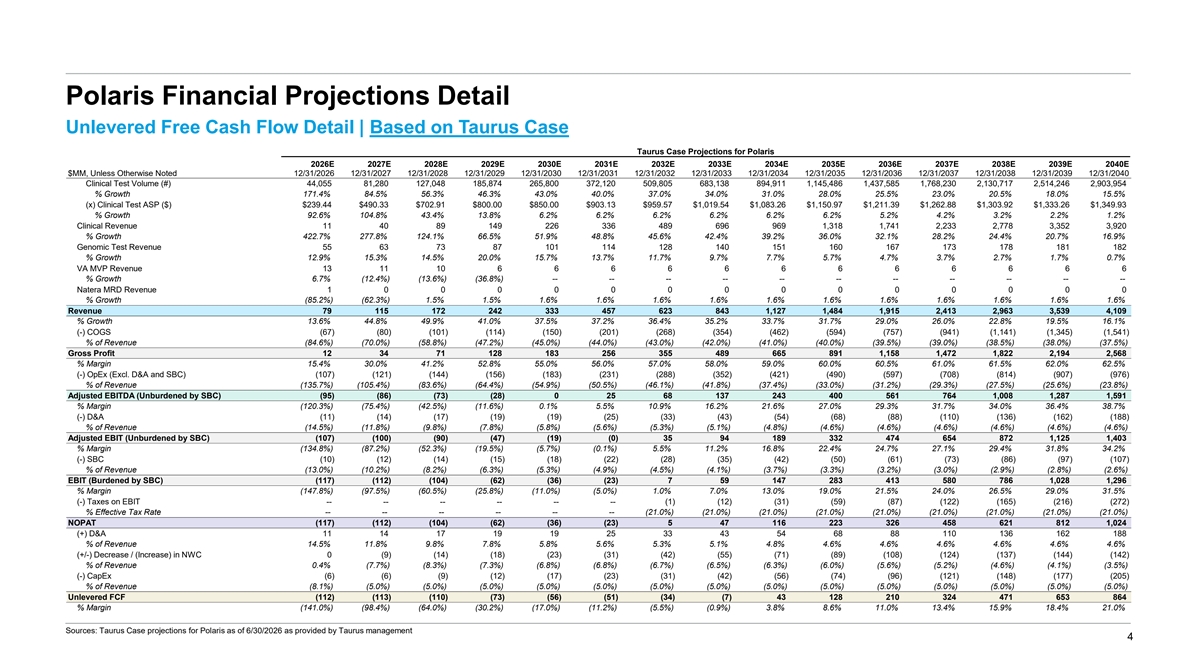
Polaris Financial Projections Detail Unlevered Free Cash Flow Detail | Based on Taurus Case Taurus Case Projections for Polaris 2026E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E 2036E 2037E 2038E 2039E 2040E $MM, Unless Otherwise Noted 12/31/2026 12/31/2027 12/31/2028 12/31/2029 12/31/2030 12/31/2031 12/31/2032 12/31/2033 12/31/2034 12/31/2035 12/31/2036 12/31/2037 12/31/2038 12/31/2039 12/31/2040 Clinical Test Volume (#) 44,055 81,280 127,048 185,874 265,800 372,120 509,805 683,138 894,911 1,145,486 1,437,585 1,768,230 2,130,717 2,514,246 2,903,954 % Growth 171.4% 84.5% 56.3% 46.3% 43.0% 40.0% 37.0% 34.0% 31.0% 28.0% 25.5% 23.0% 20.5% 18.0% 15.5% (x) Clinical Test ASP ($) $239.44 $490.33 $702.91 $800.00 $850.00 $903.13 $959.57 $1,019.54 $1,083.26 $1,150.97 $1,211.39 $1,262.88 $1,303.92 $1,333.26 $1,349.93 % Growth 92.6% 104.8% 43.4% 13.8% 6.2% 6.2% 6.2% 6.2% 6.2% 6.2% 5.2% 4.2% 3.2% 2.2% 1.2% Clinical Revenue 11 40 89 149 226 336 489 696 969 1,318 1,741 2,233 2,778 3,352 3,920 % Growth 422.7% 277.8% 124.1% 66.5% 51.9% 48.8% 45.6% 42.4% 39.2% 36.0% 32.1% 28.2% 24.4% 20.7% 16.9% Genomic Test Revenue 55 63 73 87 101 114 128 140 151 160 167 173 178 181 182 % Growth 12.9% 15.3% 14.5% 20.0% 15.7% 13.7% 11.7% 9.7% 7.7% 5.7% 4.7% 3.7% 2.7% 1.7% 0.7% VA MVP Revenue 13 11 10 6 6 6 6 6 6 6 6 6 6 6 6 % Growth 6.7% (12.4%) (13.6%) (36.8%) -- -- -- -- -- -- -- -- -- -- -- Natera MRD Revenue 1 0 0 0 0 0 0 0 0 0 0 0 0 0 0 % Growth (85.2%) (62.3%) 1.5% 1.5% 1.6% 1.6% 1.6% 1.6% 1.6% 1.6% 1.6% 1.6% 1.6% 1.6% 1.6% Revenue 79 115 172 242 333 457 623 843 1,127 1,484 1,915 2,413 2,963 3,539 4,109 % Growth 13.6% 44.8% 49.9% 41.0% 37.5% 37.2% 36.4% 35.2% 33.7% 31.7% 29.0% 26.0% 22.8% 19.5% 16.1% (-) COGS (67) (80) (101) (114) (150) (201) (268) (354) (462) (594) (757) (941) (1,141) (1,345) (1,541) % of Revenue (84.6%) (70.0%) (58.8%) (47.2%) (45.0%) (44.0%) (43.0%) (42.0%) (41.0%) (40.0%) (39.5%) (39.0%) (38.5%) (38.0%) (37.5%) Gross Profit 12 34 71 128 183 256 355 489 665 891 1,158 1,472 1,822 2,194 2,568 % Margin 15.4% 30.0% 41.2% 52.8% 55.0% 56.0% 57.0% 58.0% 59.0% 60.0% 60.5% 61.0% 61.5% 62.0% 62.5% (-) OpEx (Excl. D&A and SBC) (107) (121) (144) (156) (183) (231) (288) (352) (421) (490) (597) (708) (814) (907) (976) % of Revenue (135.7%) (105.4%) (83.6%) (64.4%) (54.9%) (50.5%) (46.1%) (41.8%) (37.4%) (33.0%) (31.2%) (29.3%) (27.5%) (25.6%) (23.8%) Adjusted EBITDA (Unburdened by SBC) (95) (86) (73) (28) 0 25 68 137 243 400 561 764 1,008 1,287 1,591 % Margin (120.3%) (75.4%) (42.5%) (11.6%) 0.1% 5.5% 10.9% 16.2% 21.6% 27.0% 29.3% 31.7% 34.0% 36.4% 38.7% (-) D&A (11) (14) (17) (19) (19) (25) (33) (43) (54) (68) (88) (110) (136) (162) (188) % of Revenue (14.5%) (11.8%) (9.8%) (7.8%) (5.8%) (5.6%) (5.3%) (5.1%) (4.8%) (4.6%) (4.6%) (4.6%) (4.6%) (4.6%) (4.6%) Adjusted EBIT (Unburdened by SBC) (107) (100) (90) (47) (19) (0) 35 94 189 332 474 654 872 1,125 1,403 % Margin (134.8%) (87.2%) (52.3%) (19.5%) (5.7%) (0.1%) 5.5% 11.2% 16.8% 22.4% 24.7% 27.1% 29.4% 31.8% 34.2% (-) SBC (10) (12) (14) (15) (18) (22) (28) (35) (42) (50) (61) (73) (86) (97) (107) % of Revenue (13.0%) (10.2%) (8.2%) (6.3%) (5.3%) (4.9%) (4.5%) (4.1%) (3.7%) (3.3%) (3.2%) (3.0%) (2.9%) (2.8%) (2.6%) EBIT (Burdened by SBC) (117) (112) (104) (62) (36) (23) 7 59 147 283 413 580 786 1,028 1,296 % Margin (147.8%) (97.5%) (60.5%) (25.8%) (11.0%) (5.0%) 1.0% 7.0% 13.0% 19.0% 21.5% 24.0% 26.5% 29.0% 31.5% (-) Taxes on EBIT -- -- -- -- -- -- (1) (12) (31) (59) (87) (122) (165) (216) (272) % Effective Tax Rate -- -- -- -- -- -- (21.0%) (21.0%) (21.0%) (21.0%) (21.0%) (21.0%) (21.0%) (21.0%) (21.0%) NOPAT (117) (112) (104) (62) (36) (23) 5 47 116 223 326 458 621 812 1,024 (+) D&A 11 14 17 19 19 25 33 43 54 68 88 110 136 162 188 % of Revenue 14.5% 11.8% 9.8% 7.8% 5.8% 5.6% 5.3% 5.1% 4.8% 4.6% 4.6% 4.6% 4.6% 4.6% 4.6% (+/-) Decrease / (Increase) in NWC 0 (9) (14) (18) (23) (31) (42) (55) (71) (89) (108) (124) (137) (144) (142) % of Revenue 0.4% (7.7%) (8.3%) (7.3%) (6.8%) (6.8%) (6.7%) (6.5%) (6.3%) (6.0%) (5.6%) (5.2%) (4.6%) (4.1%) (3.5%) (-) CapEx (6) (6) (9) (12) (17) (23) (31) (42) (56) (74) (96) (121) (148) (177) (205) % of Revenue (8.1%) (5.0%) (5.0%) (5.0%) (5.0%) (5.0%) (5.0%) (5.0%) (5.0%) (5.0%) (5.0%) (5.0%) (5.0%) (5.0%) (5.0%) Unlevered FCF (112) (113) (110) (73) (56) (51) (34) (7) 43 128 210 324 471 653 864 % Margin (141.0%) (98.4%) (64.0%) (30.2%) (17.0%) (11.2%) (5.5%) (0.9%) 3.8% 8.6% 11.0% 13.4% 15.9% 18.4% 21.0% Sources: Taurus Case projections for Polaris as of 6/30/2026 as provided by Taurus management 4
Exhibit (c)(19) Fairness Opinion Discussion Materials Project Polaris July 19, 2026
Legal Disclaimer We have prepared this document solely for informational purposes. You should not definitively rely upon it or use it to form the definitive basis for any decision, contract, commitment or action whatsoever, with respect to any proposed transaction or otherwise. You and your directors, officers, employees, agents and affiliates must hold this document and any oral information provided in connection with this document in strict confidence and may not communicate, reproduce, distribute or disclose it to any other person, or refer to it publicly, in whole or in part at any time except with our prior written consent. If you are not the intended recipient of this document, please delete and destroy all copies immediately. We have prepared this document and the analyses contained in it based, in part, on certain assumptions and information obtained by us from the recipient, its directors, officers, employees, agents, affiliates and/or from other sources. Our use of such assumptions and information does not imply that we have independently verified or necessarily agree with any of such assumptions or information, and we have assumed and relied upon the accuracy and completeness of such assumptions and information for purposes of this document. Neither we nor any of our affiliates, or our or their respective officers, employees or agents, make any representation or warranty, express or implied, in relation to the accuracy or completeness of the information contained in this document or any oral information provided in connection herewith, or any data it generates and accept no responsibility, obligation or liability (whether direct or indirect, in contract, tort or otherwise) in relation to any of such information. We and our affiliates and our and their respective officers, employees and agents expressly disclaim any and all liability which may be based on this document and any errors therein or omissions therefrom. Neither we nor any of our affiliates, or our or their respective officers, employees or agents, make any representation or warranty, express or implied, that any transaction has been or may be effected on the terms or in the manner stated in this document, or as to the achievement or reasonableness of future projections, management targets, estimates, prospects or returns, if any. Any views or terms contained herein are based on financial, economic, market and other conditions prevailing as of the date of this document and are therefore subject to change. We undertake no obligation or responsibility to update any of the information contained in this document. Past performance does not guarantee or predict future performance. We have (i) assumed that any forecasted financial information contained herein reflects the best available estimates of future financial performance, and (ii) not made any independent valuation or appraisal of the assets or liabilities of any company involved in any proposed transaction, nor have we been furnished with any such valuations or appraisals. The purpose of this document is to provide the recipient with an explanation of the basis upon which Morgan Stanley is issuing a financial opinion letter in relation to the proposed transaction. This document should be read in conjunction with and is subject to the terms of such financial opinion. This document supersedes any previous documents or presentations delivered by Morgan Stanley to the recipient in connection with the proposed transaction. This document and the information contained herein do not constitute an offer to sell or the solicitation of an offer to buy any security, commodity or instrument or related derivative, nor do they constitute an offer or commitment to lend, syndicate or arrange a financing, underwrite or purchase or act as an agent or advisor or in any other capacity with respect to any transaction, or commit capital, or to participate in any trading strategies, and do not constitute legal, regulatory, accounting or tax advice to the recipient. We recommend that the recipient seek independent third party legal, regulatory, accounting and tax advice regarding the contents of this document. This document is not a research report and was not prepared by the research department of Morgan Stanley or any of its affiliates. Notwithstanding anything herein to the contrary, each recipient hereof (and their employees, representatives, and other agents) may disclose to any and all persons, without limitation of any kind from the commencement of discussions, the U.S. federal and state income tax treatment and tax structure of the proposed transaction and all materials of any kind (including opinions or other tax analyses) that are provided relating to the tax treatment and tax structure. For this purpose, tax structure is limited to facts relevant to the U.S. federal and state income tax treatment of the proposed transaction and does not include information relating to the identity of the parties, their affiliates, agents or advisors. This document is provided by Morgan Stanley & Co. LLC and/or certain of its affiliates, which may include Morgan Stanley Realty Incorporated, Morgan Stanley Senior Funding, Inc., Morgan Stanley Bank, N.A., Morgan Stanley & Co. International plc, Morgan Stanley & Co. Limited, Morgan Stanley Bank International (Milan Branch), Morgan Stanley Saudi Arabia, Morgan Stanley South Africa (PTY) Limited, Morgan Stanley Securities Limited, Morgan Stanley Bank AG, Morgan Stanley MUFG Securities Co., Ltd, Mitsubishi UFJ Morgan Stanley Securities Co., Ltd, Morgan Stanley India Company Private Limited, Morgan Stanley Asia Limited, Morgan Stanley Australia Limited, Morgan Stanley Asia (Singapore) Pte., Morgan Stanley Services Limited, Morgan Stanley & Co. International plc, Seoul Branch, Morgan Stanley Canada Limited and/or Morgan Stanley, SV, SAU. Unless governing law permits otherwise, you must contact an authorized Morgan Stanley entity in your jurisdiction regarding this document or any of the information contained herein. © Morgan Stanley and/or certain of its affiliates. All rights reserved. 2
Table of Contents Section 1 Transaction Overview 4 Section 2 Valuation Analysis 6 Appendix Supplemental Materials 11 3
SECTION 1 Transaction Overview 4
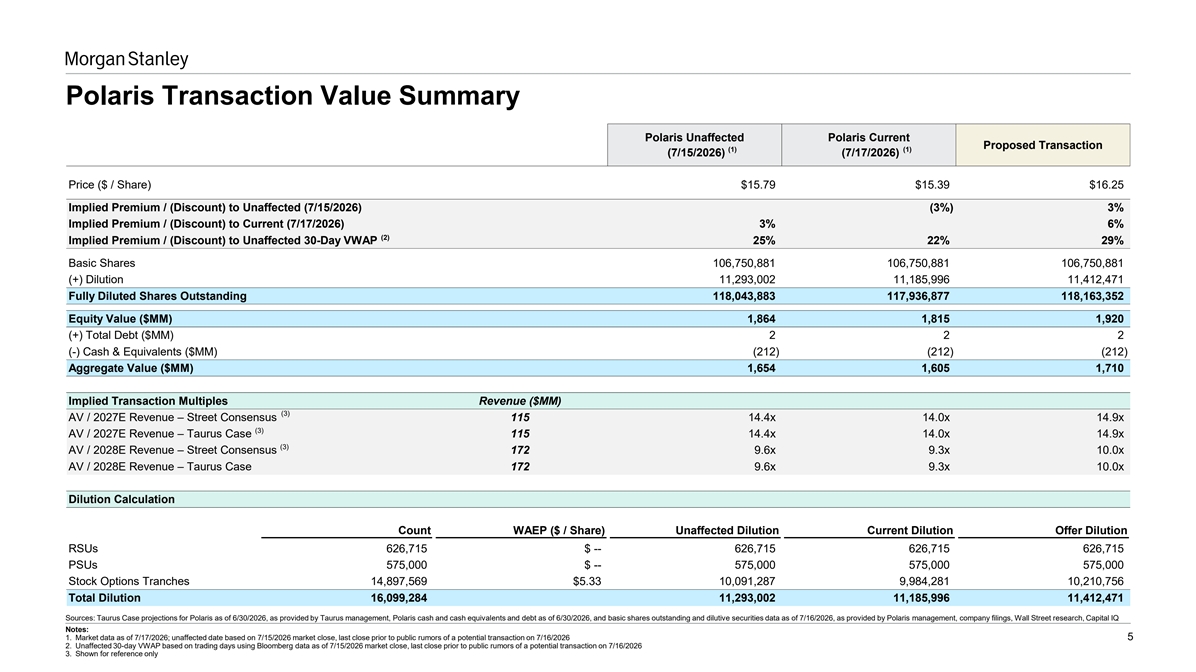
Polaris Transaction Value Summary Polaris Unaffected Polaris Current Proposed Transaction (1) (1) (7/15/2026) (7/17/2026) Price ($ / Share) $15.79 $15.39 $16.25 Implied Premium / (Discount) to Unaffected (7/15/2026) (3%) 3% Implied Premium / (Discount) to Current (7/17/2026) 3% 6% (2) Implied Premium / (Discount) to Unaffected 30-Day VWAP 25% 22% 29% Basic Shares 106,750,881 106,750,881 106,750,881 (+) Dilution 11,293,002 11,185,996 11,412,471 Fully Diluted Shares Outstanding 118,043,883 117,936,877 118,163,352 Equity Value ($MM) 1,864 1,815 1,920 (+) Total Debt ($MM) 2 2 2 (-) Cash & Equivalents ($MM) (212) (212) (212) Aggregate Value ($MM) 1,654 1,605 1,710 Implied Transaction Multiples Revenue ($MM) (3) AV / 2027E Revenue – Street Consensus 115 14.4x 14.0x 14.9x (3) AV / 2027E Revenue – Taurus Case 115 14.4x 14.0x 14.9x (3) AV / 2028E Revenue – Street Consensus 172 9.6x 9.3x 10.0x AV / 2028E Revenue – Taurus Case 172 9.6x 9.3x 10.0x Dilution Calculation Count WAEP ($ / Share) Unaffected Dilution Current Dilution Offer Dilution RSUs 626,715 $ -- 626,715 626,715 626,715 PSUs 575,000 $ -- 575,000 575,000 575,000 Stock Options Tranches 14,897,569 $5.33 10,091,287 9,984,281 10,210,756 Total Dilution 16,099,284 11,293,002 11,185,996 11,412,471 Sources: Taurus Case projections for Polaris as of 6/30/2026, as provided by Taurus management, Polaris cash and cash equivalents and debt as of 6/30/2026, and basic shares outstanding and dilutive securities data as of 7/16/2026, as provided by Polaris management, company filings, Wall Street research, Capital IQ Notes: 1. Market data as of 7/17/2026; unaffected date based on 7/15/2026 market close, last close prior to public rumors of a potential transaction on 7/16/2026 5 2. Unaffected 30-day VWAP based on trading days using Bloomberg data as of 7/15/2026 market close, last close prior to public rumors of a potential transaction on 7/16/2026 3. Shown for reference only
SECTION 2 Valuation Analysis 6
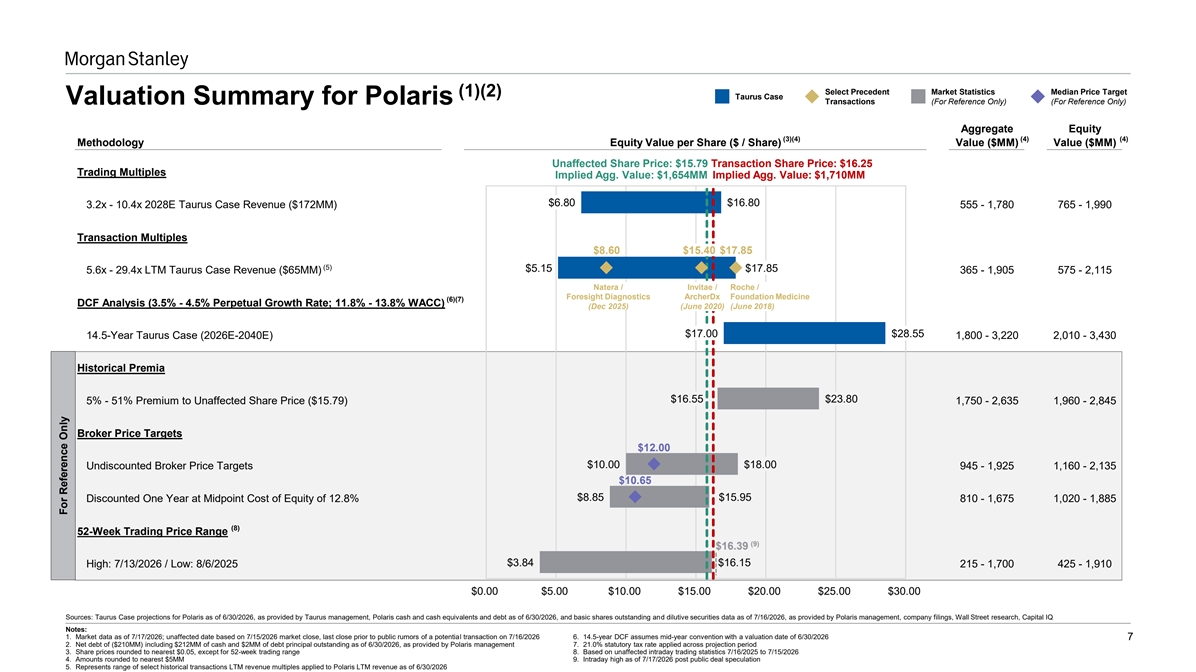
Select Precedent Market Statistics Median Price Target (1)(2) Taurus Case Transactions (For Reference Only) (For Reference Only) Valuation Summary for Polaris Aggregate Equity (3)(4) (4) (4) Methodology Equity Value per Share ($ / Share) Value ($MM) Value ($MM) Unaffected Share Price: $15.79 Transaction Share Price: $16.25 Trading Multiples Implied Agg. Value: $1,654MM Implied Agg. Value: $1,710MM $6.80 $16.80 3.2x - 10.4x 2028E Taurus Case Revenue ($172MM) 555 - 1,780 765 - 1,990 Transaction Multiples $8.60 $15.40 $17.85 (5) $5.15 $17.85 5.6x - 29.4x LTM Taurus Case Revenue ($65MM) 365 - 1,905 575 - 2,115 Natera / Invitae / Roche / Foresight Diagnostics ArcherDx Foundation Medicine (6)(7) DCF Analysis (3.5% - 4.5% Perpetual Growth Rate; 11.8% - 13.8% WACC) (Dec 2025) (June 2020) (June 2018) $17.00 $28.55 14.5-Year Taurus Case (2026E-2040E) 1,800 - 3,220 2,010 - 3,430 Historical Premia $16.55 $23.80 5% - 51% Premium to Unaffected Share Price ($15.79) 1,750 - 2,635 1,960 - 2,845 Broker Price Targets $12.00 $10.00 $18.00 Undiscounted Broker Price Targets 945 - 1,925 1,160 - 2,135 $10.65 $8.85 $15.95 Discounted One Year at Midpoint Cost of Equity of 12.8% 810 - 1,675 1,020 - 1,885 (8) 52-Week Trading Price Range (9) $16.39 $3.84 $16.15 High: 7/13/2026 / Low: 8/6/2025 215 - 1,700 425 - 1,910 $0.00 $5.00 $10.00 $15.00 $20.00 $25.00 $30.00 Sources: Taurus Case projections for Polaris as of 6/30/2026, as provided by Taurus management, Polaris cash and cash equivalents and debt as of 6/30/2026, and basic shares outstanding and dilutive securities data as of 7/16/2026, as provided by Polaris management, company filings, Wall Street research, Capital IQ Notes: 1. Market data as of 7/17/2026; unaffected date based on 7/15/2026 market close, last close prior to public rumors of a potential transaction on 7/16/2026 6. 14.5-year DCF assumes mid-year convention with a valuation date of 6/30/2026 7 2. Net debt of ($210MM) including $212MM of cash and $2MM of debt principal outstanding as of 6/30/2026, as provided by Polaris management 7. 21.0% statutory tax rate applied across projection period 3. Share prices rounded to nearest $0.05, except for 52-week trading range 8. Based on unaffected intraday trading statistics 7/16/2025 to 7/15/2026 4. Amounts rounded to nearest $5MM 9. Intraday high as of 7/17/2026 post public deal speculation 5. Represents range of select historical transactions LTM revenue multiples applied to Polaris LTM revenue as of 6/30/2026 For Reference Only
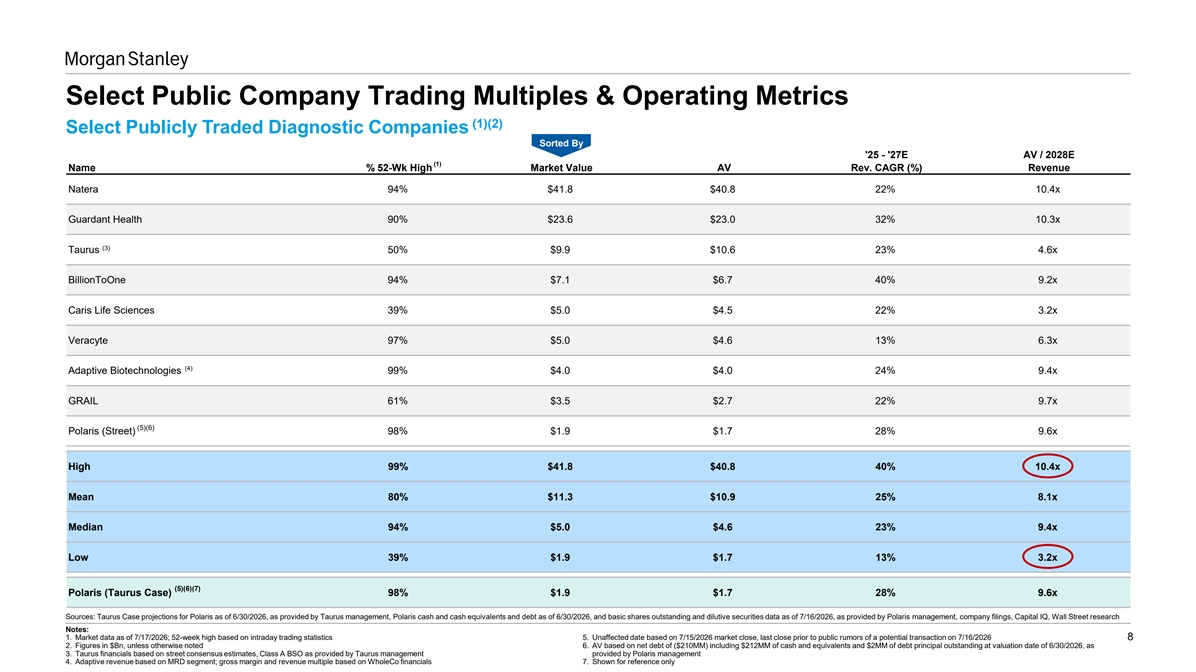
Select Public Company Trading Multiples & Operating Metrics (1)(2) Select Publicly Traded Diagnostic Companies Sorted By '25 - '27E AV / 2028E (1) Name % 52-Wk High Market Value AV Rev. CAGR (%) Revenue Natera 94% $41.8 $40.8 22% 10.4x Guardant Health 90% $23.6 $23.0 32% 10.3x (3) Taurus 50% $9.9 $10.6 23% 4.6x BillionToOne 94% $7.1 $6.7 40% 9.2x Caris Life Sciences 39% $5.0 $4.5 22% 3.2x Veracyte 97% $5.0 $4.6 13% 6.3x (4) Adaptive Biotechnologies 99% $4.0 $4.0 24% 9.4x GRAIL 61% $3.5 $2.7 22% 9.7x (5)(6) Polaris (Street) 98% $1.9 $1.7 28% 9.6x High 99% $41.8 $40.8 40% 10.4x Mean 80% $11.3 $10.9 25% 8.1x Median 94% $5.0 $4.6 23% 9.4x Low 39% $1.9 $1.7 13% 3.2x (5)(6)(7) Polaris (Taurus Case) 98% $1.9 $1.7 28% 9.6x Sources: Taurus Case projections for Polaris as of 6/30/2026, as provided by Taurus management, Polaris cash and cash equivalents and debt as of 6/30/2026, and basic shares outstanding and dilutive securities data as of 7/16/2026, as provided by Polaris management, company filings, Capital IQ, Wall Street research Notes: 1. Market data as of 7/17/2026; 52-week high based on intraday trading statistics 5. Unaffected date based on 7/15/2026 market close, last close prior to public rumors of a potential transaction on 7/16/2026 8 2. Figures in $Bn, unless otherwise noted 6. AV based on net debt of ($210MM) including $212MM of cash and equivalents and $2MM of debt principal outstanding at valuation date of 6/30/2026, as 3. Taurus financials based on street consensus estimates, Class A BSO as provided by Taurus management provided by Polaris management 4. Adaptive revenue based on MRD segment; gross margin and revenue multiple based on WholeCo financials 7. Shown for reference only
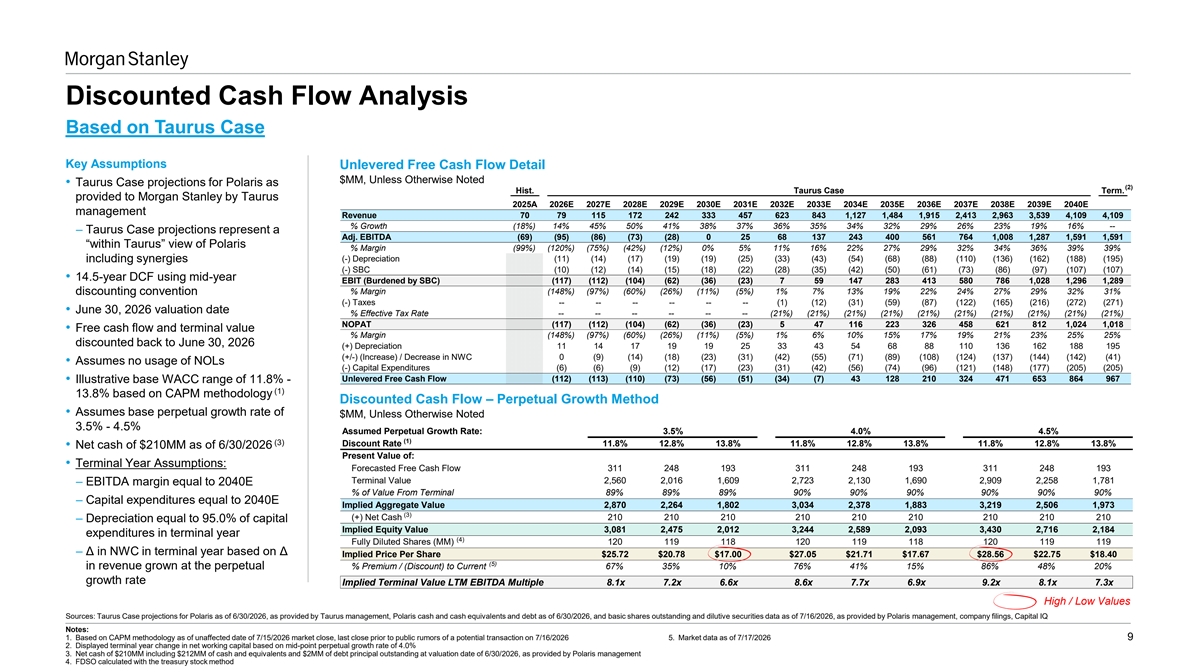
Discounted Cash Flow Analysis Based on Taurus Case Key Assumptions Unlevered Free Cash Flow Detail $MM, Unless Otherwise Noted • Taurus Case projections for Polaris as (2) Hist. Taurus Case Term. provided to Morgan Stanley by Taurus 2025A 2026E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E 2036E 2037E 2038E 2039E 2040E management Revenue 70 79 115 172 242 333 457 623 843 1,127 1,484 1,915 2,413 2,963 3,539 4,109 4,109 % Growth (18%) 14% 45% 50% 41% 38% 37% 36% 35% 34% 32% 29% 26% 23% 19% 16% -- – Taurus Case projections represent a Adj. EBITDA (69) (95) (86) (73) (28) 0 25 68 137 243 400 561 764 1,008 1,287 1,591 1,591 “within Taurus” view of Polaris % Margin (99%) (120%) (75%) (42%) (12%) 0% 5% 11% 16% 22% 27% 29% 32% 34% 36% 39% 39% (-) Depreciation (11) (14) (17) (19) (19) (25) (33) (43) (54) (68) (88) (110) (136) (162) (188) (195) including synergies (-) SBC (10) (12) (14) (15) (18) (22) (28) (35) (42) (50) (61) (73) (86) (97) (107) (107) • 14.5-year DCF using mid-year EBIT (Burdened by SBC) (117) (112) (104) (62) (36) (23) 7 59 147 283 413 580 786 1,028 1,296 1,289 % Margin (148%) (97%) (60%) (26%) (11%) (5%) 1% 7% 13% 19% 22% 24% 27% 29% 32% 31% discounting convention (-) Taxes -- -- -- -- -- -- (1) (12) (31) (59) (87) (122) (165) (216) (272) (271) • June 30, 2026 valuation date % Effective Tax Rate -- -- -- -- -- -- (21%) (21%) (21%) (21%) (21%) (21%) (21%) (21%) (21%) (21%) NOPAT (117) (112) (104) (62) (36) (23) 5 47 116 223 326 458 621 812 1,024 1,018 • Free cash flow and terminal value % Margin (148%) (97%) (60%) (26%) (11%) (5%) 1% 6% 10% 15% 17% 19% 21% 23% 25% 25% discounted back to June 30, 2026 (+) Depreciation 11 14 17 19 19 25 33 43 54 68 88 110 136 162 188 195 (+/-) (Increase) / Decrease in NWC 0 (9) (14) (18) (23) (31) (42) (55) (71) (89) (108) (124) (137) (144) (142) (41) • Assumes no usage of NOLs (-) Capital Expenditures (6) (6) (9) (12) (17) (23) (31) (42) (56) (74) (96) (121) (148) (177) (205) (205) Unlevered Free Cash Flow (112) (113) (110) (73) (56) (51) (34) (7) 43 128 210 324 471 653 864 967 • Illustrative base WACC range of 11.8% - (1) 13.8% based on CAPM methodology Discounted Cash Flow – Perpetual Growth Method • Assumes base perpetual growth rate of $MM, Unless Otherwise Noted 3.5% - 4.5% Assumed Perpetual Growth Rate: 3.5% 4.0% 4.5% (1) (3) Discount Rate 11.8% 12.8% 13.8% 11.8% 12.8% 13.8% 11.8% 12.8% 13.8% • Net cash of $210MM as of 6/30/2026 Present Value of: • Terminal Year Assumptions: Forecasted Free Cash Flow 311 248 193 311 248 193 311 248 193 Terminal Value 2,560 2,016 1,609 2,723 2,130 1,690 2,909 2,258 1,781 – EBITDA margin equal to 2040E % of Value From Terminal 89% 89% 89% 90% 90% 90% 90% 90% 90% – Capital expenditures equal to 2040E Implied Aggregate Value 2,870 2,264 1,802 3,034 2,378 1,883 3,219 2,506 1,973 (3) (+) Net Cash 210 210 210 210 210 210 210 210 210 – Depreciation equal to 95.0% of capital Implied Equity Value 3,081 2,475 2,012 3,244 2,589 2,093 3,430 2,716 2,184 expenditures in terminal year (4) Fully Diluted Shares (MM) 120 119 118 120 119 118 120 119 119 – Δ in NWC in terminal year based on Δ Implied Price Per Share $25.72 $20.78 $17.00 $27.05 $21.71 $17.67 $28.56 $22.75 $18.40 (5) in revenue grown at the perpetual % Premium / (Discount) to Current 67% 35% 10% 76% 41% 15% 86% 48% 20% growth rate Implied Terminal Value LTM EBITDA Multiple 8.1x 7.2x 6.6x 8.6x 7.7x 6.9x 9.2x 8.1x 7.3x High / Low Values Sources: Taurus Case projections for Polaris as of 6/30/2026, as provided by Taurus management, Polaris cash and cash equivalents and debt as of 6/30/2026, and basic shares outstanding and dilutive securities data as of 7/16/2026, as provided by Polaris management, company filings, Capital IQ Notes: 1. Based on CAPM methodology as of unaffected date of 7/15/2026 market close, last close prior to public rumors of a potential transaction on 7/16/2026 5. Market data as of 7/17/2026 9 2. Displayed terminal year change in net working capital based on mid-point perpetual growth rate of 4.0% 3. Net cash of $210MM including $212MM of cash and equivalents and $2MM of debt principal outstanding at valuation date of 6/30/2026, as provided by Polaris management 4. FDSO calculated with the treasury stock method
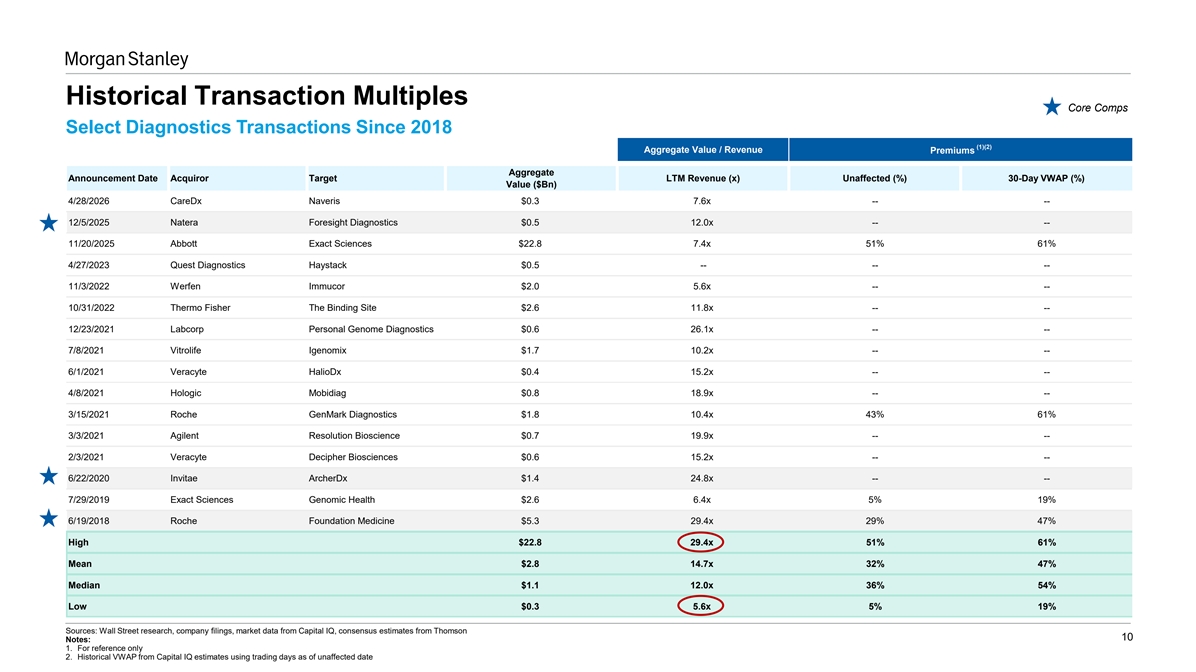
Historical Transaction Multiples Core Comps Select Diagnostics Transactions Since 2018 (1)(2) Aggregate Value / Revenue Premiums Aggregate Announcement Date Acquiror Target LTM Revenue (x) Unaffected (%) 30-Day VWAP (%) Value ($Bn) 4/28/2026 CareDx Naveris $0.3 7.6x -- -- 12/5/2025 Natera Foresight Diagnostics $0.5 12.0x -- -- 11/20/2025 Abbott Exact Sciences $22.8 7.4x 51% 61% 4/27/2023 Quest Diagnostics Haystack $0.5 -- -- -- 11/3/2022 Werfen Immucor $2.0 5.6x -- -- 10/31/2022 Thermo Fisher The Binding Site $2.6 11.8x -- -- 12/23/2021 Labcorp Personal Genome Diagnostics $0.6 26.1x -- -- 7/8/2021 Vitrolife Igenomix $1.7 10.2x -- -- 6/1/2021 Veracyte HalioDx $0.4 15.2x -- -- 4/8/2021 Hologic Mobidiag $0.8 18.9x -- -- 3/15/2021 Roche GenMark Diagnostics $1.8 10.4x 43% 61% 3/3/2021 Agilent Resolution Bioscience $0.7 19.9x -- -- 2/3/2021 Veracyte Decipher Biosciences $0.6 15.2x -- -- 6/22/2020 Invitae ArcherDx $1.4 24.8x -- -- 7/29/2019 Exact Sciences Genomic Health $2.6 6.4x 5% 19% 6/19/2018 Roche Foundation Medicine $5.3 29.4x 29% 47% High $22.8 29.4x 51% 61% Mean $2.8 14.7x 32% 47% Median $1.1 12.0x 36% 54% Low $0.3 5.6x 5% 19% Sources: Wall Street research, company filings, market data from Capital IQ, consensus estimates from Thomson 10 Notes: 1. For reference only 2. Historical VWAP from Capital IQ estimates using trading days as of unaffected date
APPENDIX Supplemental Materials 11
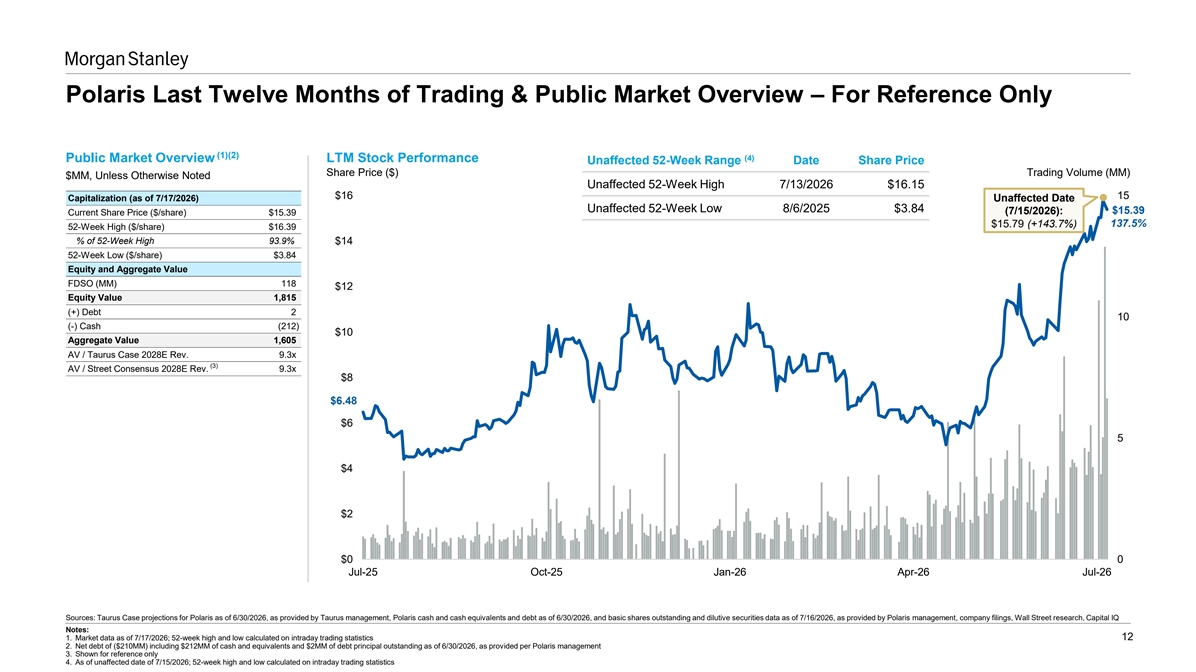
Polaris Last Twelve Months of Trading & Public Market Overview – For Reference Only (1)(2) (4) Public Market Overview LTM Stock Performance Unaffected 52-Week Range Date Share Price Share Price ($) Trading Volume (MM) $MM, Unless Otherwise Noted Unaffected 52-Week High 7/13/2026 $16.15 $16 15 Capitalization (as of 7/17/2026) Unaffected Date Unaffected 52-Week Low 8/6/2025 $3.84 (7/15/2026): $15.39 Current Share Price ($/share) $15.39 137.5% $15.79 (+143.7%) 52-Week High ($/share) $16.39 % of 52-Week High 93.9% $14 52-Week Low ($/share) $3.84 Equity and Aggregate Value FDSO (MM) 118 $12 Equity Value 1,815 (+) Debt 2 10 (-) Cash (212) $10 Aggregate Value 1,605 AV / Taurus Case 2028E Rev. 9.3x (3) AV / Street Consensus 2028E Rev. 9.3x $8 $6.48 $6 5 $4 $2 $0 0 Jul-25 Oct-25 Jan-26 Apr-26 Jul-26 Sources: Taurus Case projections for Polaris as of 6/30/2026, as provided by Taurus management, Polaris cash and cash equivalents and debt as of 6/30/2026, and basic shares outstanding and dilutive securities data as of 7/16/2026, as provided by Polaris management, company filings, Wall Street research, Capital IQ Notes: 12 1. Market data as of 7/17/2026; 52-week high and low calculated on intraday trading statistics 2. Net debt of ($210MM) including $212MM of cash and equivalents and $2MM of debt principal outstanding as of 6/30/2026, as provided per Polaris management 3. Shown for reference only 4. As of unaffected date of 7/15/2026; 52-week high and low calculated on intraday trading statistics
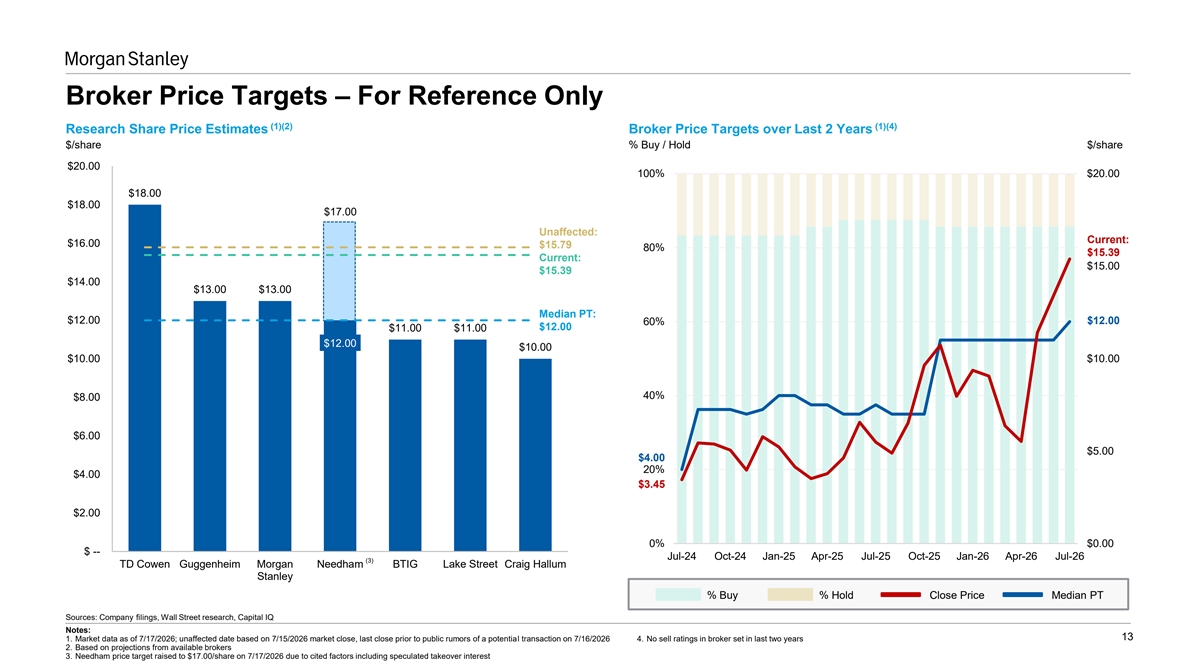
Broker Price Targets – For Reference Only (1)(2) (1)(4) Research Share Price Estimates Broker Price Targets over Last 2 Years $/share % Buy / Hold $/share $20.00 100% $20.00 $18.00 $18.00 $17.00 Unaffected: Current: $16.00 $15.79 80% $15.39 Current: $15.00 $15.39 $14.00 $13.00 $13.00 Median PT: $12.00 $12.00 60% $12.00 $11.00 $11.00 $12.00 $10.00 $10.00 $10.00 40% $8.00 $6.00 $5.00 $4.00 20% $4.00 $3.45 $2.00 0% $0.00 $ -- Jul-24 Oct-24 Jan-25 Apr-25 Jul-25 Oct-25 Jan-26 Apr-26 Jul-26 (3) TD Cowen Guggenheim Morgan Needham BTIG Lake Street Craig Hallum Stanley % Buy % Hold Close Price Median PT Sources: Company filings, Wall Street research, Capital IQ Notes: 13 1. Market data as of 7/17/2026; unaffected date based on 7/15/2026 market close, last close prior to public rumors of a potential transaction on 7/16/2026 4. No sell ratings in broker set in last two years 2. Based on projections from available brokers 3. Needham price target raised to $17.00/share on 7/17/2026 due to cited factors including speculated takeover interest
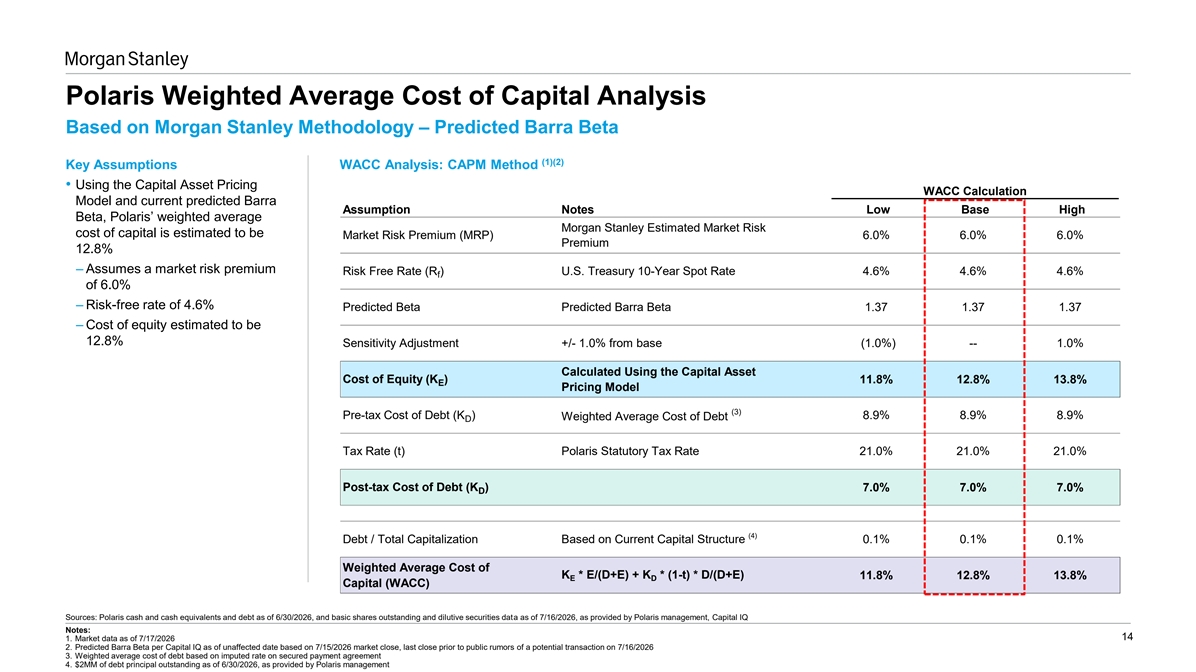
Polaris Weighted Average Cost of Capital Analysis Based on Morgan Stanley Methodology – Predicted Barra Beta (1)(2) Key Assumptions WACC Analysis: CAPM Method • Using the Capital Asset Pricing WACC Calculation Model and current predicted Barra Assumption Notes Low Base High Beta, Polaris’ weighted average Morgan Stanley Estimated Market Risk cost of capital is estimated to be Market Risk Premium (MRP) 6.0% 6.0% 6.0% Premium 12.8% – Assumes a market risk premium Risk Free Rate (R ) U.S. Treasury 10-Year Spot Rate 4.6% 4.6% 4.6% f of 6.0% – Risk-free rate of 4.6% Predicted Beta Predicted Barra Beta 1.37 1.37 1.37 – Cost of equity estimated to be 12.8% Sensitivity Adjustment +/- 1.0% from base (1.0%) -- 1.0% Calculated Using the Capital Asset Cost of Equity (K ) 11.8% 12.8% 13.8% E Pricing Model (3) Pre-tax Cost of Debt (K ) 8.9% 8.9% 8.9% Weighted Average Cost of Debt D Tax Rate (t) Polaris Statutory Tax Rate 21.0% 21.0% 21.0% Post-tax Cost of Debt (K ) 7.0% 7.0% 7.0% D (4) Debt / Total Capitalization Based on Current Capital Structure 0.1% 0.1% 0.1% Weighted Average Cost of K * E/(D+E) + K * (1-t) * D/(D+E) 11.8% 12.8% 13.8% E D Capital (WACC) Sources: Polaris cash and cash equivalents and debt as of 6/30/2026, and basic shares outstanding and dilutive securities data as of 7/16/2026, as provided by Polaris management, Capital IQ Notes: 14 1. Market data as of 7/17/2026 2. Predicted Barra Beta per Capital IQ as of unaffected date based on 7/15/2026 market close, last close prior to public rumors of a potential transaction on 7/16/2026 3. Weighted average cost of debt based on imputed rate on secured payment agreement 4. $2MM of debt principal outstanding as of 6/30/2026, as provided by Polaris management
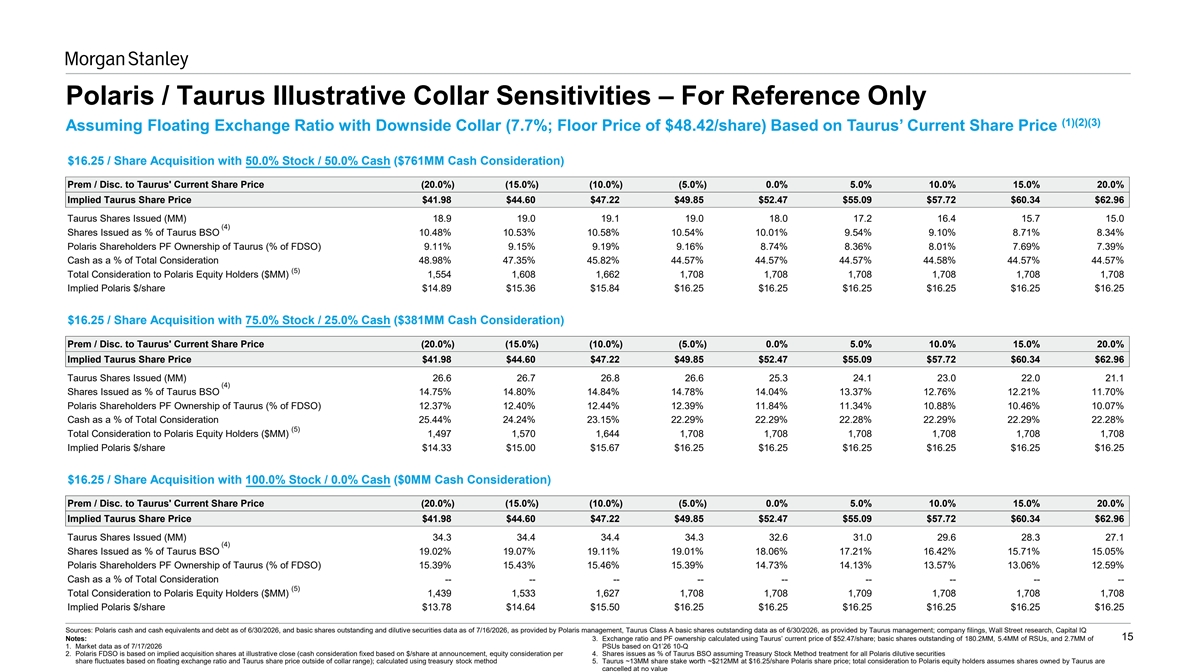
Polaris / Taurus Illustrative Collar Sensitivities – For Reference Only (1)(2)(3) Assuming Floating Exchange Ratio with Downside Collar (7.7%; Floor Price of $48.42/share) Based on Taurus’ Current Share Price $16.25 / Share Acquisition with 50.0% Stock / 50.0% Cash ($761MM Cash Consideration) Prem / Disc. to Taurus' Current Share Price (20.0%) (15.0%) (10.0%) (5.0%) 0.0% 5.0% 10.0% 15.0% 20.0% Implied Taurus Share Price $41.98 $44.60 $47.22 $49.85 $52.47 $55.09 $57.72 $60.34 $62.96 Taurus Shares Issued (MM) 18.9 19.0 19.1 19.0 18.0 17.2 16.4 15.7 15.0 (4) Shares Issued as % of Taurus BSO 10.48% 10.53% 10.58% 10.54% 10.01% 9.54% 9.10% 8.71% 8.34% Polaris Shareholders PF Ownership of Taurus (% of FDSO) 9.11% 9.15% 9.19% 9.16% 8.74% 8.36% 8.01% 7.69% 7.39% Cash as a % of Total Consideration 48.98% 47.35% 45.82% 44.57% 44.57% 44.57% 44.58% 44.57% 44.57% (5) Total Consideration to Polaris Equity Holders ($MM) 1,554 1,608 1,662 1,708 1,708 1,708 1,708 1,708 1,708 Implied Polaris $/share $14.89 $15.36 $15.84 $16.25 $16.25 $16.25 $16.25 $16.25 $16.25 $16.25 / Share Acquisition with 75.0% Stock / 25.0% Cash ($381MM Cash Consideration) Prem / Disc. to Taurus' Current Share Price (20.0%) (15.0%) (10.0%) (5.0%) 0.0% 5.0% 10.0% 15.0% 20.0% Implied Taurus Share Price $41.98 $44.60 $47.22 $49.85 $52.47 $55.09 $57.72 $60.34 $62.96 Taurus Shares Issued (MM) 26.6 26.7 26.8 26.6 25.3 24.1 23.0 22.0 21.1 (4) Shares Issued as % of Taurus BSO 14.75% 14.80% 14.84% 14.78% 14.04% 13.37% 12.76% 12.21% 11.70% Polaris Shareholders PF Ownership of Taurus (% of FDSO) 12.37% 12.40% 12.44% 12.39% 11.84% 11.34% 10.88% 10.46% 10.07% Cash as a % of Total Consideration 25.44% 24.24% 23.15% 22.29% 22.29% 22.28% 22.29% 22.29% 22.28% (5) Total Consideration to Polaris Equity Holders ($MM) 1,497 1,570 1,644 1,708 1,708 1,708 1,708 1,708 1,708 Implied Polaris $/share $14.33 $15.00 $15.67 $16.25 $16.25 $16.25 $16.25 $16.25 $16.25 $16.25 / Share Acquisition with 100.0% Stock / 0.0% Cash ($0MM Cash Consideration) Prem / Disc. to Taurus' Current Share Price (20.0%) (15.0%) (10.0%) (5.0%) 0.0% 5.0% 10.0% 15.0% 20.0% Implied Taurus Share Price $41.98 $44.60 $47.22 $49.85 $52.47 $55.09 $57.72 $60.34 $62.96 Taurus Shares Issued (MM) 34.3 34.4 34.4 34.3 32.6 31.0 29.6 28.3 27.1 (4) Shares Issued as % of Taurus BSO 19.02% 19.07% 19.11% 19.01% 18.06% 17.21% 16.42% 15.71% 15.05% Polaris Shareholders PF Ownership of Taurus (% of FDSO) 15.39% 15.43% 15.46% 15.39% 14.73% 14.13% 13.57% 13.06% 12.59% Cash as a % of Total Consideration -- -- -- -- -- -- -- -- -- (5) Total Consideration to Polaris Equity Holders ($MM) 1,439 1,533 1,627 1,708 1,708 1,709 1,708 1,708 1,708 Implied Polaris $/share $13.78 $14.64 $15.50 $16.25 $16.25 $16.25 $16.25 $16.25 $16.25 Sources: Polaris cash and cash equivalents and debt as of 6/30/2026, and basic shares outstanding and dilutive securities data as of 7/16/2026, as provided by Polaris management, Taurus Class A basic shares outstanding data as of 6/30/2026, as provided by Taurus management; company filings, Wall Street research, Capital IQ 15 Notes: 3. Exchange ratio and PF ownership calculated using Taurus’ current price of $52.47/share; basic shares outstanding of 180.2MM, 5.4MM of RSUs, and 2.7MM of 1. Market data as of 7/17/2026 PSUs based on Q1’26 10-Q 2. Polaris FDSO is based on implied acquisition shares at illustrative close (cash consideration fixed based on $/share at announcement, equity consideration per 4. Shares issues as % of Taurus BSO assuming Treasury Stock Method treatment for all Polaris dilutive securities share fluctuates based on floating exchange ratio and Taurus share price outside of collar range); calculated using treasury stock method 5. Taurus ~13MM share stake worth ~$212MM at $16.25/share Polaris share price; total consideration to Polaris equity holders assumes shares owned by Taurus are cancelled at no value
| Calculation of Filing Fee Tables |
| Table 1: Transaction Valuation |
|---|
| Transaction Valuation |
Fee Rate |
Amount of Filing Fee | ||
|---|---|---|---|---|
| |
1 | $ |
|
$ |
| Fees Previously Paid | ||||
| Total Transaction Valuation: |
$ |
|||
| Total Fees Due for Filing: |
$ | |||
| Total Fees Previously Paid: |
$ | |||
| Total Fee Offsets: |
$ | |||
| Net Fee Due: |
$ |
| Offering Note |
| 1 |
| ||||||
| | |||||||
| Table 2: Fee Offset Claims and Sources |
|---|
| Registrant or Filer Name | Form or Filing Type | File Number | Initial Filing Date | Filing Date | Fee Offset Claimed | Fee Paid with Fee Offset Source | ||
|---|---|---|---|---|---|---|---|---|
| |
1 | |
|
|
$ |
|||
| |
|
|
|
|
$ |
| Explanation of the basis for claimed offset: |
| 1 |
| ||||||
| | |||||||